Topic Summary
What Filing First Audited Dubai Actually Requires
Filing first audited Dubai means submitting independently audited financial statements prepared under IFRS to your free zone authority and, where applicable, to the Federal Tax Authority. Every free zone company must do this regardless of revenue, with accounts due within 90 days
Key Dates and the Corporate Tax Filing Deadline
For most Dubai free zone companies with a 31 December year-end, audited accounts are due by 31 March. The corporate tax return must be filed within nine months of the financial year-end, 30 September for a December year-end, giving founders a separate but equally firm filing firs
The Revenue Threshold That Changes Your Obligations
The UAE corporate tax rate is 9% on taxable income above AED 375,000. Below that threshold, the rate is 0%. However, the obligation to register, file a return, and maintain audited accounts applies regardless of revenue level. This filing first Dubai guide covers a point many fou
Step-by-Step Guide to Filing First Audited Dubai Accounts
Filing first audited Dubai accounts involves six sequential steps: choosing a Ministry of Economy-registered auditor, closing your books under IFRS, commissioning the audit engagement, receiving and reviewing the signed audit report, submitting to your free zone authority, and fi
Penalties and Exposure You Need to Know
The Federal Tax Authority charges AED 10,000 for late corporate tax registration. Additional administrative penalties apply for late filing and incorrect returns. Your free zone authority can block license renewal for missing audited accounts. Combined, these exposures can cost a
Most first-time free zone founders in Dubai don't realise their audited financial statements are due within 90 days of their financial year-end, and missing that window carries a fixed AED 10,000 penalty (Federal Tax Authority, 2024). Filing your first audited accounts in Dubai is not optional, not deferred for new companies, and not something you can quietly push back. The obligation kicks in from the first financial year your license is active, regardless of whether you invoiced a single dirham. The corporate tax return deadline sits nine months after year-end. The late registration penalty is AED 10,000. The voluntary disclosure penalty for understated income is 50%. These are fixed figures, not estimates.
This guide covers exactly what filing first audited Dubai requires: the legal basis, the precise deadlines, the revenue threshold that triggers corporate tax filing, the penalty structure, and a stage-by-stage table showing what applies at each point in your first year.
What Filing First Audited Dubai Actually Requires
Filing first audited Dubai means submitting independently audited financial statements prepared under IFRS to your free zone authority and, where applicable, to the Federal Tax Authority. Every free zone company must do this regardless of revenue, with accounts due within 90 days of the financial year-end and a corporate tax return due within nine months.
The Legal Basis for Audit Obligations in a Free Zone
Two separate legal instruments create the audit obligation. First, your free zone authority requires audited financial statements as a condition of annual license renewal. Second, Federal Decree-Law No. 47 of 2022 (the UAE Corporate Tax Law) independently requires Qualifying Free Zone Persons and all taxable persons to maintain audited accounts (tax.gov.ae, 2022). Neither obligation waits for the other.
IFRS or IFRS for SMEs is the accepted reporting standard. Management accounts, internal spreadsheets, or bookkeeping records alone don't satisfy either authority. The obligation begins from the first financial year in which the company holds a valid license, not from the year it generates revenue.
Take a practical example: a technology consultancy licensed at a Dubai free zone in March with a 31 December year-end must have its first audited accounts ready by 31 March of the following year, even if it invoiced nothing in those nine months of trading. Zero revenue is not a valid reason for deferral.
How Free Zone Authorities Enforce the Requirement
Most free zone authorities will block license renewal if prior-year audited accounts haven't been submitted and accepted. Some request the audit report at renewal; others require it uploaded to their portal at the 90-day mark, irrespective of when renewal falls. The distinction matters.
A founder who incorporated in January and renews in February the following year may assume they have a full year before the audit matters. They don't. The 90-day submission clock runs from 31 December, not from the renewal date. That's a gap of roughly six weeks, and Q1 audit capacity in Dubai fills fast.
The auditor you appoint must be registered with the UAE Ministry of Economy. Using an unregistered firm invalidates the submission entirely. The approved register is publicly available at moet.gov.ae. For help identifying approved auditors and managing the process, business support services at Dubai South Business Hub Free Zone can point you in the right direction from day one.
Key Dates and the Corporate Tax Filing Deadline
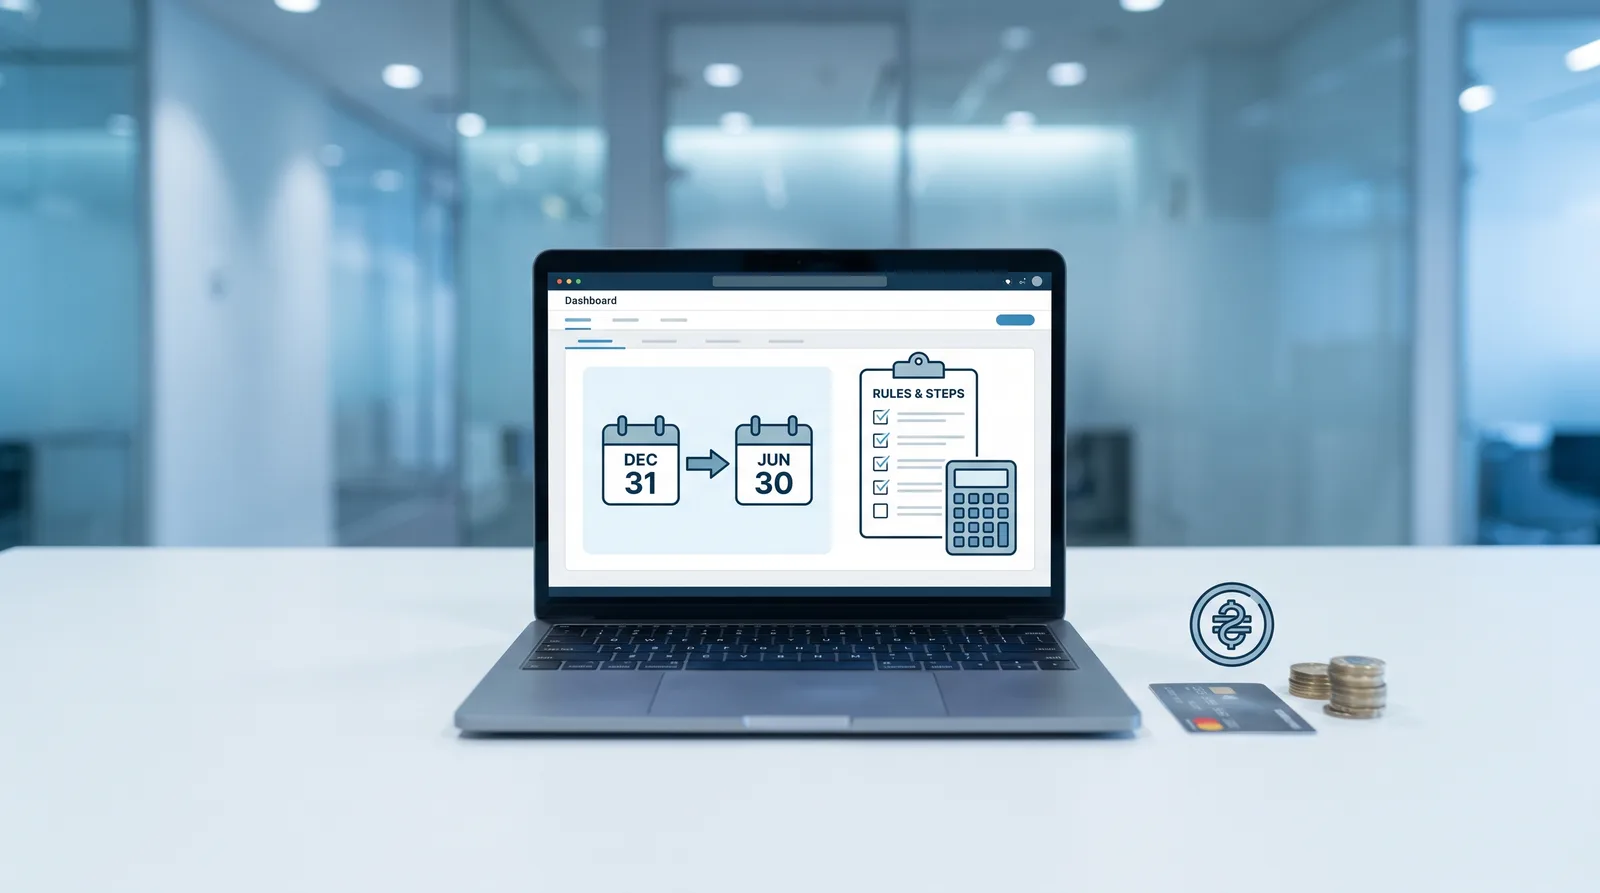
For most Dubai free zone companies with a 31 December year-end, audited accounts are due by 31 March. The corporate tax return must be filed within nine months of the financial year-end, 30 September for a December year-end, giving founders a separate but equally firm filing first Dubai deadline that carries its own AED 10,000 late-registration penalty.
The 90-Day Audit Submission Window
The 90-day clock starts on the last day of the financial year, not your incorporation date. Key dates by year-end:
31 December year-end: audit due by 31 March
31 March year-end: audit due by 29 June
30 June year-end: audit due by 28 September
Book an approved auditor at least 60 days before year-end. Q1 is peak audit season across the UAE, and auditor slots fill by mid-January most years. An e-commerce company incorporated in June with a 31 December year-end will have only six months of activity in its first accounts, but the 31 March audit deadline still applies in full. There's no shortened window for a partial first year.
The Nine-Month Corporate Tax Return Window
Under Federal Decree-Law No. 47 of 2022, Article 51, the UAE corporate tax return must be filed within nine months of the end of the relevant tax period. For a 31 December year-end, that's 30 September of the following year. The return requires the audited accounts as a supporting document, so the audit must be complete before the return can be submitted.
A professional services firm with a December year-end faces two hard deadlines: audited accounts by 31 March, corporate tax return by 30 September. Two separate portals, two separate penalty authorities. For a broader view of how banking and tax obligations interact, the banking and taxation services page covers both in detail.
Late registration for corporate tax carries a fixed AED 10,000 penalty from the Federal Tax Authority. That penalty applies even if your taxable income is zero (tax.gov.ae, 2023).
The Revenue Threshold That Changes Your Obligations
The UAE corporate tax rate is 9% on taxable income above AED 375,000. Below that threshold, the rate is 0%. However, the obligation to register, file a return, and maintain audited accounts applies regardless of revenue level. This filing first Dubai guide covers a point many founders miss: the 0% rate is not automatic, and for Qualifying Free Zone Persons, it comes with four statutory conditions.
The AED 375,000 Taxable Income Threshold
Corporate tax of 9% applies to net taxable income exceeding AED 375,000 per tax period. Income at or below AED 375,000 is taxed at 0%, but that doesn't remove the filing obligation. The threshold is calculated on net taxable profit, not gross revenue, so a high-revenue business with large allowable deductions may fall below it.
Consider a trading company with AED 2 million in revenue but AED 1.7 million in allowable costs. Taxable income is AED 300,000, below the threshold, so 0% tax applies. But the return must still be filed, and audited accounts must still be produced. First-year founders often underestimate profitability mid-year and find themselves scrambling to register before the deadline.
If your revenue is below AED 50 million, IFRS for SMEs is a permissible and simpler reporting alternative to full IFRS.
The Four Conditions for Qualifying Free Zone Person Status
A Qualifying Free Zone Person (QFZP) may access a 0% rate on qualifying income, but only if all four conditions under the Corporate Tax Law are met simultaneously. Partial compliance isn't sufficient.
Adequate substance: The entity must maintain genuine economic substance in the UAE.
Qualifying income: Income must meet the definition in Ministerial Decision No. 139 of 2023.
No standard tax election: The entity must not have elected to be subject to standard corporate tax.
Compliance: Transfer pricing rules must be followed and audited financial statements maintained.
A free zone consultancy that earns income from a UAE mainland client may find that income classified as non-qualifying, pulling it out of QFZP status for the entire year unless the structure is carefully planned. This is a nuance that regularly catches founders off guard at audit time (tax.gov.ae, 2023).
Step-by-Step Guide to Filing First Audited Dubai Accounts
Filing first audited Dubai accounts involves six sequential steps: choosing a Ministry of Economy-registered auditor, closing your books under IFRS, commissioning the audit engagement, receiving and reviewing the signed audit report, submitting to your free zone authority, and filing the corporate tax return within nine months of year-end.
Step 1: Appoint a Registered Auditor Early
Only auditors registered with the UAE Ministry of Economy are accepted by free zone authorities and the Federal Tax Authority. Appoint no later than 60 days before year-end to allow adequate time for planning and fieldwork. Audit fieldwork for a new SME typically takes three to six weeks.
A founder who waits until January to appoint an auditor for a December year-end risks missing the 31 March deadline, Q1 audit capacity in Dubai is fully booked by mid-January most years. Agree the scope in writing: the engagement letter should specify IFRS or IFRS for SMEs, the reporting period, and the fee. The approved register is at moet.gov.ae.
Step 2: Close Your Books and Prepare Financial Statements
Before handing records to the auditor, prepare a trial balance, profit and loss statement, balance sheet, and cash flow statement under IFRS. Reconcile all bank accounts and clear any suspense items. Document all related-party transactions, these are scrutinised under transfer pricing rules.
Reconcile every bank account to the closing balance
Clear suspense and unallocated items
List all intercompany transactions with supporting agreements
Confirm whether IFRS for SMEs applies (revenue below AED 50 million)
A two-partner advisory firm with straightforward invoicing can typically close its books in two weeks using cloud accounting software, cutting audit time and cost significantly.
Step 3: Submit Accounts and File the Corporate Tax Return
Upload the signed audited accounts to your free zone authority portal within 90 days of year-end. If you haven't already registered on the Federal Tax Authority's EmaraTax platform, do it immediately, late registration carries an AED 10,000 penalty. File the corporate tax return within nine months of year-end using the audited accounts as the base document.
A December year-end company submits its audit to the free zone by 31 March, then files its corporate tax return on EmaraTax by 30 September. Two portals, two deadlines, both mandatory. Retain all audit working papers and financial records for seven years as required by the Corporate Tax Law (tax.gov.ae, 2022).
Penalties and Exposure You Need to Know
The Federal Tax Authority charges AED 10,000 for late corporate tax registration. Additional administrative penalties apply for late filing and incorrect returns. Your free zone authority can block license renewal for missing audited accounts. Combined, these exposures can cost a first-year company AED 20,000 or more before any tax liability is assessed. Meeting the filing first Dubai deadline isn't just good practice, it's the difference between operating and being shut down.
Federal Tax Authority Penalties: Fixed and Percentage-Based
Late corporate tax registration: AED 10,000 fixed penalty
Late VAT registration (if applicable): AED 10,000 fixed penalty, charged separately
Late filing of corporate tax return: administrative penalty as a percentage of unpaid tax
Voluntary disclosure of understated income: 50% penalty on the understated amount
FTA-discovered understatement: 100% penalty on the understated amount
A founder who misses both the corporate tax registration deadline and the VAT registration threshold in the same year faces AED 20,000 in fixed penalties before a single return is filed. That's a straightforward, avoidable cost (tax.gov.ae, 2023).
Free Zone Authority Exposure: License Renewal Risk
A free zone authority will not renew a license if prior-year audited accounts haven't been submitted. A lapsed license puts every visa tied to that license at risk of cancellation. If you have employees or partners on UAE residency visas linked to your company, the exposure extends well beyond a regulatory fine.
Operating on a lapsed license is a regulatory violation that can result in fines and business suspension. UAE banks regularly request audited accounts for account maintenance and credit facilities, so the reputational exposure with banking partners is real. A company with a lapsed license because its audit wasn't submitted risks visa cancellations, a flagged bank account, and counterparties questioning its ability to execute contracts.
Filing First Audited Dubai: Obligations by Company Stage
Stage | Key Obligation | Document Required | Deadline | Authority |
|---|---|---|---|---|
Year 0 to 1 (Active trading year) | Maintain IFRS-compliant bookkeeping; register for corporate tax on EmaraTax | Chart of accounts, bank statements, invoices | Before first tax period ends | Federal Tax Authority |
Day 90 after year-end | Submit audited financial statements to free zone authority | Signed audit report (IFRS or IFRS for SMEs), management accounts | 90 days from year-end (e.g., 31 March for December year-end) | Free Zone Authority |
Month 9 after year-end | File corporate tax return with audited accounts attached | Corporate tax return, audited financials, transfer pricing documentation | 9 months from year-end (e.g., 30 September for December year-end) | Federal Tax Authority via EmaraTax |
License renewal (Year 2) | Submit prior-year audited accounts if not already done; renew license | Audited accounts, renewal application | Before license expiry date | Free Zone Authority |
Ongoing (VAT-registered entities) | File VAT returns quarterly or monthly; reconcile with audited accounts | Tax invoices, VAT return, reconciliation schedule |
References
Frequently Asked Questions