Topic Summary
Can a Non-Resident Withdraw Cash From a UAE Business Account? Why Signatory Status Matters
Yes, in most cases a non-resident can withdraw cash from a UAE business account if they are a registered authorised signatory and the bank has verified their identity. Residency isn't the test. The mandate, the KYC (know your customer) file and expected cash activity decide approval.
Who Can Authorise Cash Withdrawals and What Banks Check
Who Can Authorise Cash Withdrawals and What Banks Check
How Major UAE Banks Handle Cash Withdrawals for Non-Residents
Emirates NBD, Mashreq, RAKBank, FAB and ADCB generally allow signatory cash withdrawals in branch, subject to KYC and limits. Wio and other digital banks lean on cards, transfers and ATMs. Policies change, so confirm with your relationship manager first.
Step-by-Step Guide to Non-Resident Withdraw Cash From a UAE Business Account
To withdraw cash as a non-resident, confirm you're a signatory, update the mandate if needed, gather documents, give notice for larger sums, visit with original ID, state the purpose and keep the receipt. Routine withdrawals usually complete the same day.
Practical Tips to Avoid Rejection and Account Freezes
Keep KYC current, match cash activity to your declared business, give notice for larger sums and prefer transfers. Expired documents and mandate mismatches are the usual triggers for holds. Review the common reasons for rejection.
Common Mistakes Non-Resident Founders Make With Business Account Cash
Common mistakes include arriving without being a named signatory, carrying expired passports, withdrawing large sums without notice and mixing personal and company cash. Any can cause refusal or a review.
Next Steps Before You Fly In
A non-resident can usually withdraw cash from a UAE business account when they're a verified signatory with valid ID and a transaction that fits the declared activity. Preparation, notice and clean records decide the outcome. Speak with the Dubai South Business Hub team about banking support, so your mandate and KYC file are ready before you travel. You may also want the guide on opening a corporate bank account before your residence visa.
Can a non-resident withdraw cash from a UAE business account? Usually yes. The UAE has 40+ licensed banks supervised by the Central Bank of the UAE [1], yet about 40% of first-time founders hit a delay or decline when operating from abroad. This guide is for free zone owners who want to withdraw cash without a hold. Corporate tax is 9% above AED 375,000 of profit [2], so clean records matter too.
Can a Non-Resident Withdraw Cash From a UAE Business Account? Why Signatory Status Matters
Yes, in most cases a non-resident can withdraw cash from a UAE business account if they are a registered authorised signatory and the bank has verified their identity. Residency isn't the test. The mandate, the KYC (know your customer) file and expected cash activity decide approval.
Residency Status Versus Signatory Status
Banks check signing authority on the board resolution, not your visa. A UK-based founder of a Dubai South Business Hub company who is sole signatory can collect cash in branch with a valid passport. A shareholder who owns 100% but isn't on the mandate can't.
Why Cash Withdrawals Get Extra Scrutiny
Cash is the highest-risk channel under UAE anti-money-laundering rules.
Banks compare withdrawals with declared activity and turnover.
Non-resident cash requests trigger source and purpose questions more often.
Picture a service consultancy asking for AED 200,000 in cash. Expect a compliance call before release. See our guide on a corporate bank account for non-residents in the UAE.
Who Can Authorise Cash Withdrawals and What Banks Check
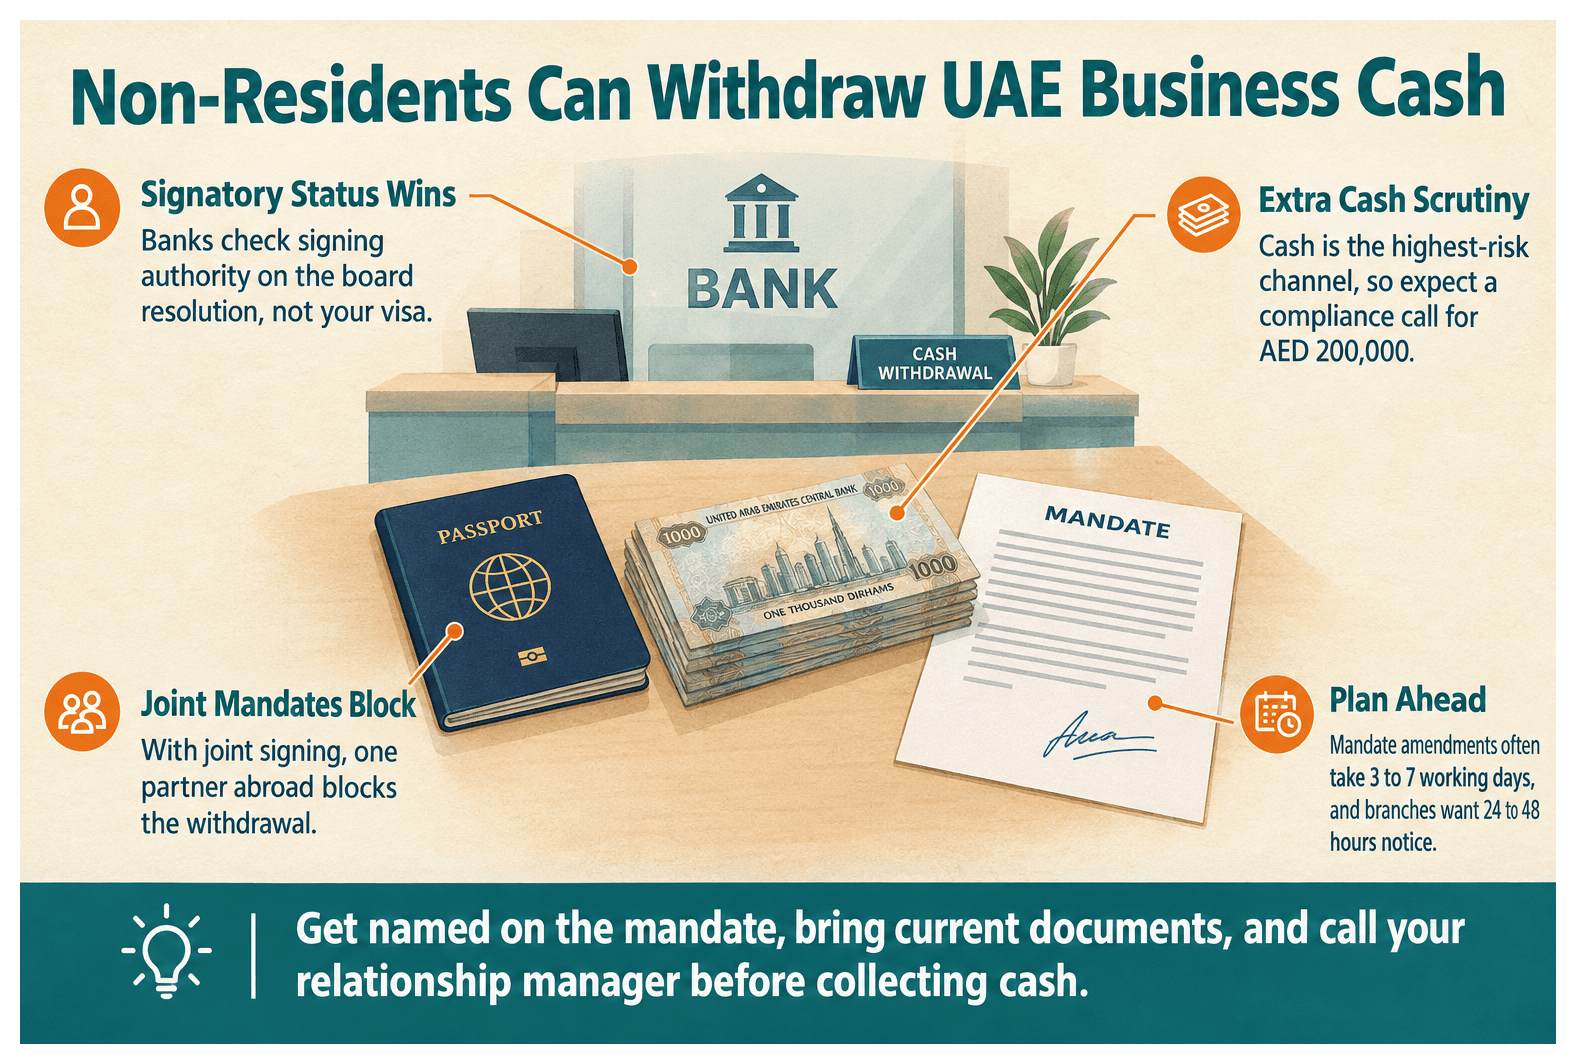
Only individuals named in the bank mandate can authorise cash withdrawals. Banks verify the passport, Emirates ID if held, specimen signature and board resolution. Non-residents are usually accepted when documents are current, though limits or in-branch presence may apply.
Mandates, Board Resolutions and Signing Rules
Joint mandates matter. In a two-partner company with joint signing, one partner abroad blocks the withdrawal. Mandate amendments often take 3 to 7 working days, so update before travelling, not at the counter.
Cash Withdrawal Options for Non-Resident Signatories
Feature | Branch Withdrawal | ATM or Card Withdrawal |
|---|---|---|
Typical limit size | Higher, set by account tier and bank approval | Lower, capped by the daily card limit |
Documents required | Original passport, license copy, signatory proof | Card and PIN only |
Notice needed for larger amounts | Often 24 to 48 hours | None, but the cap can't be exceeded |
Audit trail | Signed slip plus recorded purpose | Automatic statement entry, no purpose recorded |
Best use case | Larger planned payments during a visit | Small day-to-day cash needs |
Identity Documents Banks Ask For
Original passport with entry stamp or visit evidence.
Emirates ID, if you're a resident.
Trade license, share certificate and updated KYC form.
KYC refreshes are commonly requested every 1 to 3 years. Banks may also set advance notice (often 24 to 48 hours) and daily limits. Digital banks such as Wio focus on cards and transfers, not branch cash.
How Major UAE Banks Handle Cash Withdrawals for Non-Residents
Emirates NBD, Mashreq, RAKBank, FAB and ADCB generally allow signatory cash withdrawals in branch, subject to KYC and limits. Wio and other digital banks lean on cards, transfers and ATMs. Policies change, so confirm with your relationship manager first.
Traditional Banks and Digital Options
A Mashreq account holder who contacts the relationship manager a day ahead collects cash without delay. Minimum balances commonly run AED 10,000 to AED 50,000, and tier affects limits. Free zone status rarely changes the rules; your KYC file and signatory status do. For Wio, ATM limits sit below branch limits, so a founder abroad can cover small needs by card. Read how to open a business bank account in the UAE for bank requirements.
Step-by-Step Guide to Non-Resident Withdraw Cash From a UAE Business Account
To withdraw cash as a non-resident, confirm you're a signatory, update the mandate if needed, gather documents, give notice for larger sums, visit with original ID, state the purpose and keep the receipt. Routine withdrawals usually complete the same day.
Confirm signatory status and limits. Email your relationship manager. Confirmation usually takes one working day, and you'll learn any notice period.
Prepare documents and notify the bank. Bring passport, license, board resolution and KYC form. Allow 2 to 3 working days if the mandate needs updating. Check you can visit your UAE company without a visa.
Withdraw in branch and record it. State the purpose, keep the receipt and file it with the invoice. The Federal Tax Authority expects supportable records.
Practical Tips to Avoid Rejection and Account Freezes
Keep KYC current, match cash activity to your declared business, give notice for larger sums and prefer transfers. Expired documents and mandate mismatches are the usual triggers for holds. Review the common reasons for rejection.
Keep Cash Activity Consistent
Declare realistic cash use at onboarding.
Never split withdrawals to dodge limits. It looks like structuring.
Keep invoices ready. Reviews can take 5 to 10 working days.
Use Safer Alternatives to Cash
Transfers, cheques and business cards leave a clean trail. Travellers must declare cash above AED 60,000 at UAE borders (Central Bank of the UAE). Dubai South Business Hub holders can ask the team about banking support.
Common Mistakes Non-Resident Founders Make With Business Account Cash
Common mistakes include arriving without being a named signatory, carrying expired passports, withdrawing large sums without notice and mixing personal and company cash. Any can cause refusal or a review.
Mixing Personal and Company Funds
Record cash as an expense, salary or shareholder distribution. A founder who takes travel cash with no loan entry will face questions from the accountant.
Ignoring Mandate and KYC Updates
Report shareholder or passport changes.
Dormancy limits often apply after 6 to 12 months.
An expired passport can restrict the account.
Next Steps Before You Fly In
A non-resident can usually withdraw cash from a UAE business account when they're a verified signatory with valid ID and a transaction that fits the declared activity. Preparation, notice and clean records decide the outcome. Speak with the Dubai South Business Hub team about banking support, so your mandate and KYC file are ready before you travel. You may also want the guide on opening a corporate bank account before your residence visa.
References
Frequently Asked Questions