Topic Summary
What Is a Swift Code and Why Your Dubai Account Needs One
A Swift code, also called a BIC, is an 8 or 11-character identifier that tells international payment networks which bank and branch should receive funds. Your Dubai account needs one because overseas clients, suppliers and platforms use it to route wires to the right UAE bank.
Why a Swift Code Matters for Free Zone Companies
Why a Swift Code Matters for Free Zone Companies
How to Find Your Swift Code Step by Step
To find your Swift code, check your account opening letter, online banking profile or bank statement, then confirm it with your relationship manager. Match it to your IBAN and test it with a small transfer.
Swift Code vs IBAN: What Each One Does for Your Dubai Account
A Swift code identifies the bank, while an IBAN identifies your account. International wires usually need both, and a UAE IBAN starts with AE and has 23 characters.
Common Swift Code Mistakes and How to Avoid Rejection
The most common mistakes are a wrong branch code, a mismatched account name, a missing IBAN and mixed-up currencies. Copy details from your bank and match the name to your trade license.
Choosing a Bank for International Payments in the UAE
Compare transfer fees, currencies, minimum balances, onboarding time and digital tools. Emirates NBD, Mashreq, RAKBank, FAB, ADCB and Wio suit different needs, from established trade banking to fast digital onboarding.
Next Steps for Your Account
A swift code and why your Dubai account needs one comes down to reliable routing: the code identifies your bank, the IBAN identifies your account, and together they keep wires moving. Share them correctly and test before large transfers.
A swift code and why your Dubai account needs one is a question every free zone founder meets on the first overseas invoice. This guide shows you what the code is, where to find it, and how to avoid payment delays.
What Is a Swift Code and Why Your Dubai Account Needs One
A Swift code, also called a BIC, is an 8 or 11-character identifier that tells international payment networks which bank and branch should receive funds. Your Dubai account needs one because overseas clients, suppliers and platforms use it to route wires to the right UAE bank.
How the Swift Network Routes Your Money
SWIFT is a messaging network, not a bank. It carries payment instructions between institutions, and correspondent banks use the code to forward funds. Picture a UK client paying your Dubai South invoice in USD: without the right code, the wire is returned or parked for manual repair.
Anatomy of a Swift Code in the UAE
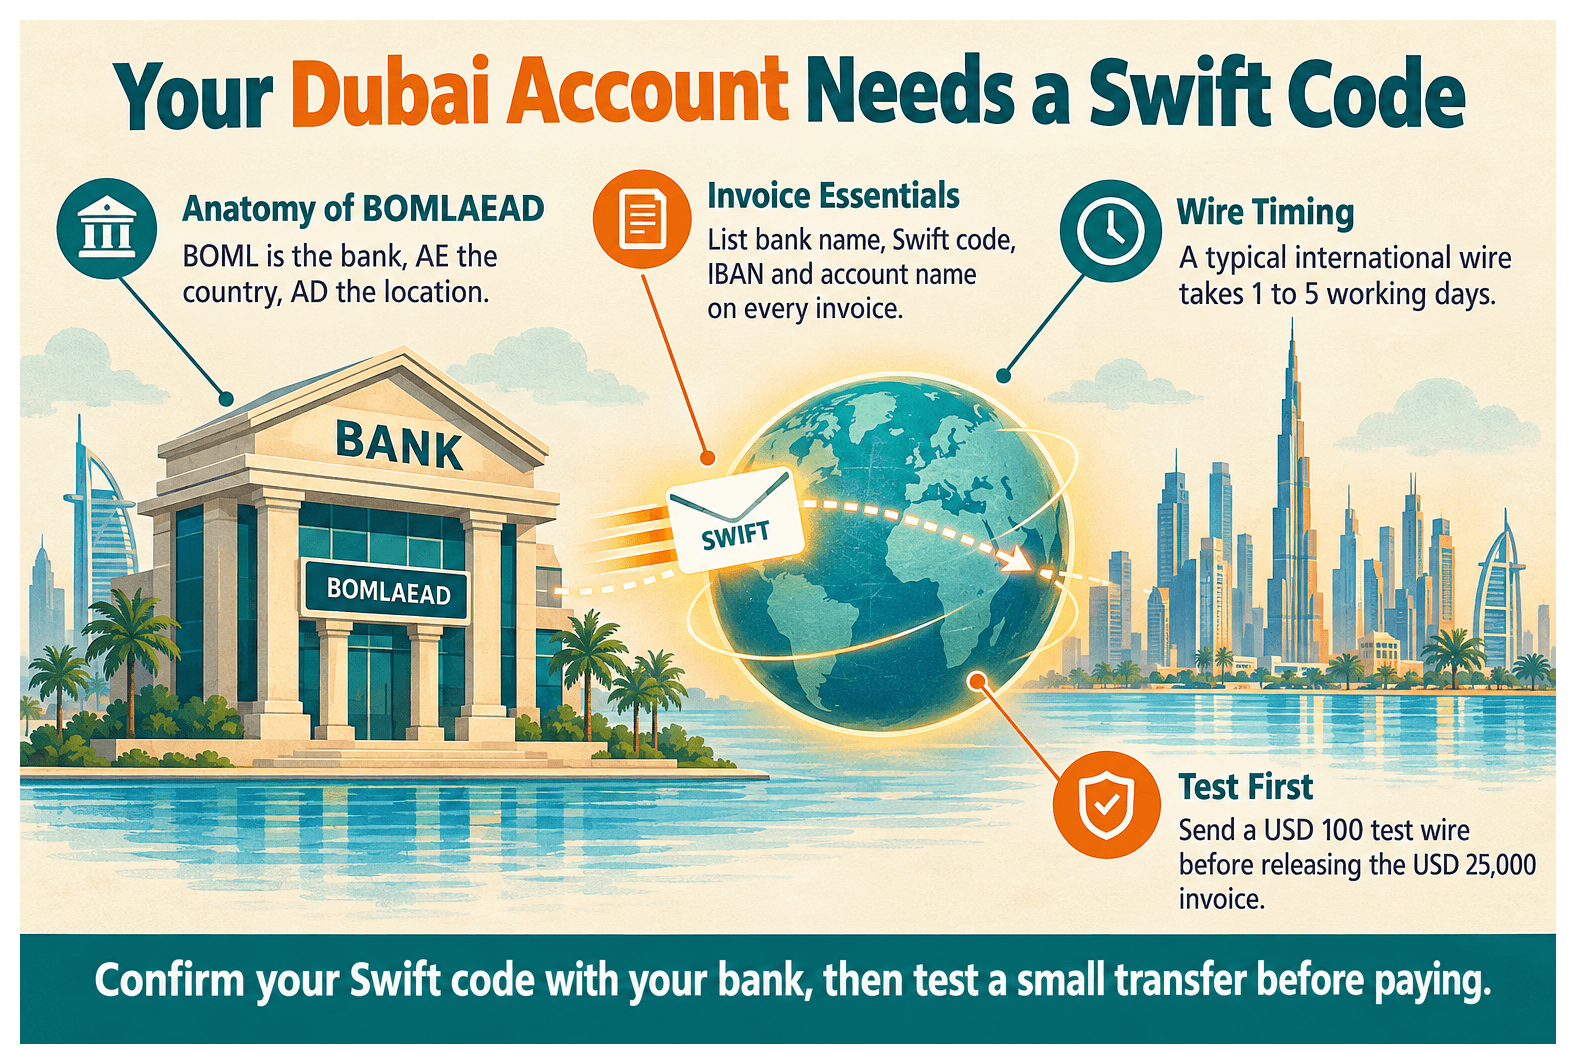
Take Mashreq's code, BOMLAEAD, as an example (always confirm yours with your bank).
BOML: the bank code.
AE: the UAE country code.
AD: the location code.
Optional three characters: a branch, with XXX meaning head office.
Why a Swift Code Matters for Free Zone Companies
Free zone companies trade across borders, so they depend on international wires. A correct Swift code speeds settlement, cuts returned payments and lets banks verify the beneficiary quickly, which supports smoother compliance checks and healthier cash flow.
Getting Paid by Overseas Clients
List bank name, Swift code, IBAN and account name on every invoice. Missing details are a leading cause of delayed receipts, and a typical international wire takes 1 to 5 working days even when everything is right. Add them to your invoice template on day one.
Paying Suppliers and Compliance Checks
Outgoing wires need the beneficiary bank's code, so a trader paying a supplier in China can't release funds without it. Banks also screen payments against sanctions lists, and the Central Bank of the UAE supervises licensed banks (Central Bank of the UAE, 2025). Keep contracts handy in case a wire is queried. The code is assigned by your bank, not the free zone. Read the banking requirements for Dubai South Business Hub companies before applying.
How to Find Your Swift Code Step by Step
To find your Swift code, check your account opening letter, online banking profile or bank statement, then confirm it with your relationship manager. Match it to your IBAN and test it with a small transfer.
Step 1: Check Your Account Documents
Open your welcome pack.
Check statement headers.
One founder found it on her first Mashreq statement.
Step 2: Look in Online Banking
Emirates NBD, FAB, ADCB and Wio show it under account details.
Share the details as a PDF.
Confirm the right currency account.
Step 3: Confirm With Your Bank
Ask for a signed details letter.
RAKBank and others issue one.
Expect 1 to 3 working days.
Step 4: Test With a Small Transfer
Ask for a USD 100 test wire.
Confirm receipt.
Then release the USD 25,000 invoice.
Swift Code vs IBAN Comparison
Feature | Swift Code | IBAN |
|---|---|---|
What it identifies | The bank and branch | Your specific account |
Length | 8 or 11 characters | 23 characters in the UAE |
Used for local transfers | Usually not needed | Typically all you need |
Used for international wires | Routes funds to your UAE bank | Directs funds to your account |
Where to find it | Welcome letter, statement, app | Statement header, app, bank letter |
Swift Code vs IBAN: What Each One Does for Your Dubai Account
A Swift code identifies the bank, while an IBAN identifies your account. International wires usually need both, and a UAE IBAN starts with AE and has 23 characters.
When You Need Both and When You Need Only One
A domestic AED transfer between Wio and ADCB needs only the IBAN. An overseas wire needs both, and an account number alone won't do. If a client sends the IBAN with a wrong Swift code, the wire bounces. Some marketplaces ask for just one, so check their form (World Bank payment systems resources explain the standards).
Common Swift Code Mistakes and How to Avoid Rejection
The most common mistakes are a wrong branch code, a mismatched account name, a missing IBAN and mixed-up currencies. Copy details from your bank and match the name to your trade license.
Use the exact licensed company name, never a shortened one.
Copy and paste, and watch for letter O versus zero.
Confirm which currency account the client is paying into.
Keep a standard bank details sheet ready.
Currency and Account Type Errors
A euro payment sent to an AED account can be converted at a poor rate. Over 40% of UAE companies transact in two or more currencies, so read about multiple currency corporate bank accounts in the UAE. Some plans cost roughly AED 99 to AED 199 monthly, excluding VAT (see business bank account cost in Dubai).
Choosing a Bank for International Payments in the UAE
Compare transfer fees, currencies, minimum balances, onboarding time and digital tools. Emirates NBD, Mashreq, RAKBank, FAB, ADCB and Wio suit different needs, from established trade banking to fast digital onboarding.
What to Compare and Which Documents Help
More than 40 licensed banks operate in the UAE (Central Bank of the UAE, 2025), and over 40% of new free zone companies face account delays. Bring your trade license, incorporation documents, passports, visas and proof of address. Add a one-page profile with expected monthly inflows and key counterparties. Our guide to opening a corporate bank account for your Dubai free zone company covers the process, and opening a corporate bank account after licensing covers timing. Approval rests with each bank.
Next Steps for Your Account
A swift code and why your Dubai account needs one comes down to reliable routing: the code identifies your bank, the IBAN identifies your account, and together they keep wires moving. Share them correctly and test before large transfers.
Speak with Dubai South Business Hub about company formation, your trade license and residency package, and get support with banking requirements so your account is ready for international payments.
References
Frequently Asked Questions