Topic Summary
What Is Islamic vs Conventional Banking: Which Is Better for a UAE Business and Why It Matters
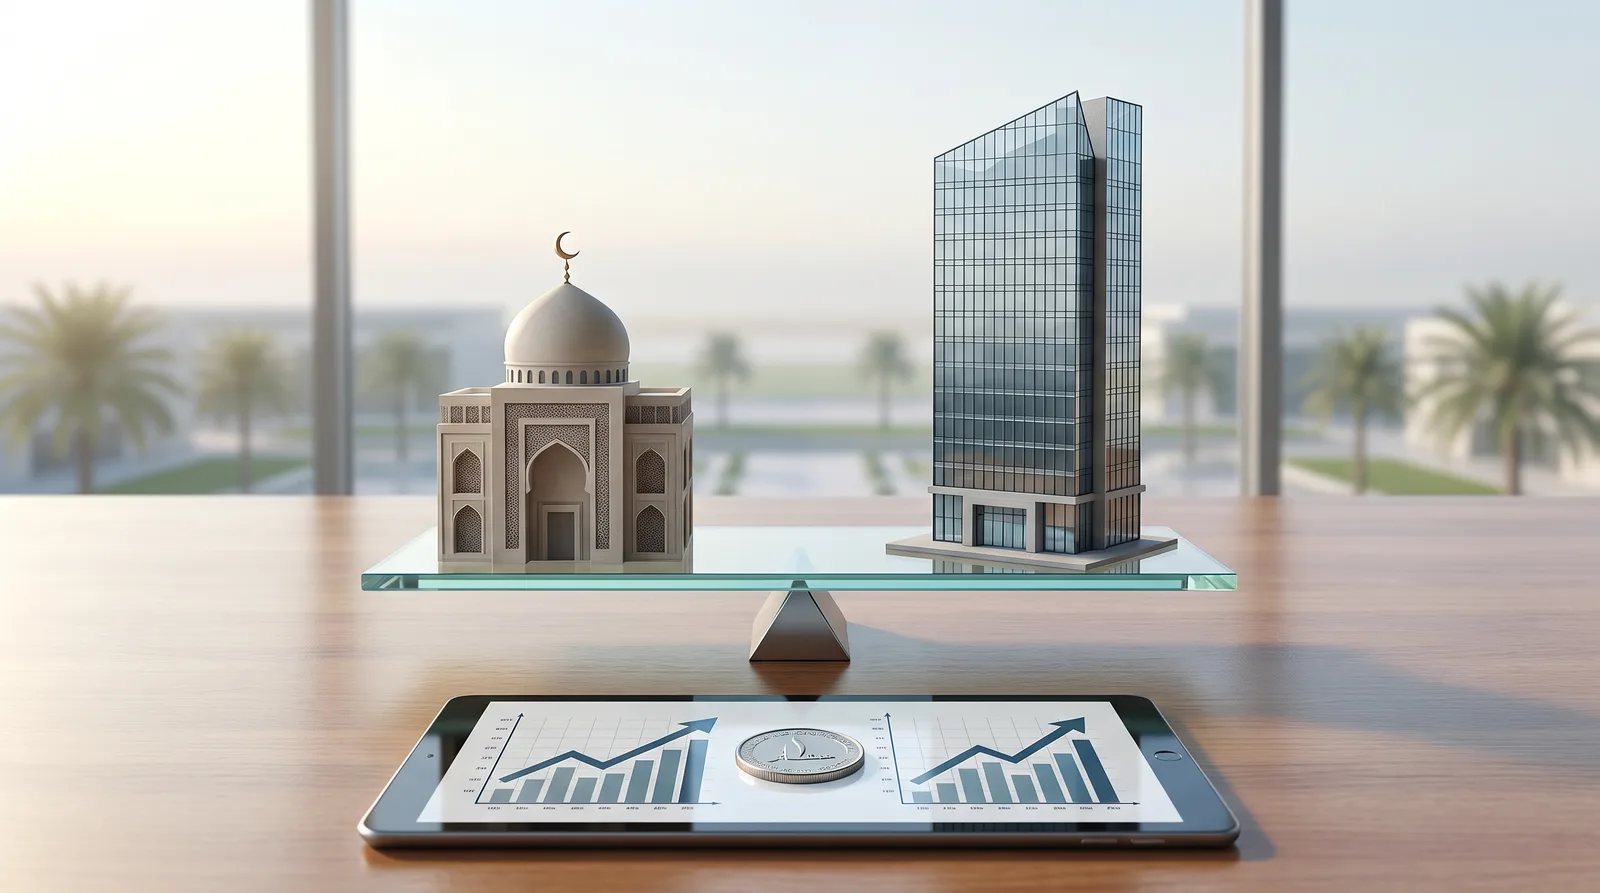
Islamic banking follows Sharia principles: no interest (riba), profit-sharing or asset-backed financing, and Sharia board oversight. Conventional banking earns and charges interest. Both are regulated by the Central Bank of the UAE. Neither is universally better; the right fit depends on your financing needs, values, cash flow and banking relationships.
How Islamic and Conventional Business Accounts Differ in Practice
How Islamic and Conventional Business Accounts Differ in Practice
Which UAE Banks Suit Free Zone Companies Best
For islamic vs conventional banking: which is better for a UAE business, the bank matters as much as the model. Emirates NBD, Mashreq, FAB and ADCB suit established companies, RAKBank suits small businesses, and Wio suits digital-first startups.
Steps to Choose and Open the Right Account for a Free Zone Company
Define your financing needs, shortlist two or three banks, prepare consistent documents, and follow up within five working days. A complete, matching document set is the biggest factor in avoiding rejection when weighing islamic vs conventional banking: which is better for a UAE business.
Common Rejection Reasons and How to Avoid Them
Most rejections in islamic vs conventional banking applications come from mismatched documents, unclear models, unclear ownership or unrealistic turnover. Keep documents consistent, show contracts and invoices, and declare source of funds clearly.
Making the Final Decision With DSBH Banking Support
Choose Islamic banking if Sharia compliance or asset-backed financing matters, and conventional banking if you need broad products or flexible credit. Many free zone firms hold both, such as an Islamic account for operations and a conventional line for working capital.
Your Next Move
Islamic vs conventional banking: which is better for a UAE business comes down to financing structure, values and growth plans. Both are Central Bank regulated and both work for free zone companies. Compare tariffs, match the bank to your activity, and consider holding both. Speak with DSBH about company formation and banking support so your license, documents and bank choice align before you apply.
More than 40 licensed banks compete for corporate clients in the UAE [1]. Yet roughly 40% of first-time founders face a delay or decline on their first application [2]. This guide on islamic vs conventional banking: which is better for a UAE business is for free zone owners who want to pick the right account and open it without losing weeks.
What Is Islamic vs Conventional Banking: Which Is Better for a UAE Business and Why It Matters
Islamic banking follows Sharia principles: no interest (riba), profit-sharing or asset-backed financing, and Sharia board oversight. Conventional banking earns and charges interest. Both are regulated by the Central Bank of the UAE. Neither is universally better; the right fit depends on your financing needs, values, cash flow and banking relationships.
How Islamic Banking Works
Islamic banks avoid riba and excessive uncertainty (gharar), and every deal is tied to a real asset. Common contracts include murabaha, ijara, musharaka and wakala. Sharia supervisory boards review products, and the Higher Sharia Authority at the Central Bank sets governance standards (Central Bank of the UAE, 2025).
Picture a trading company that needs a forklift fleet. Instead of a term loan, it signs an ijara (lease-to-own) and the bank owns the equipment until the final payment.
How Conventional Banking Works
Conventional banks offer interest-based loans, overdrafts and deposits, with wider SME product menus. The same Central Bank licensing, AML and KYC rules apply. A consultancy waiting 60 days on client invoices might use an overdraft to cover payroll in the gap.
Islamic vs Conventional Business Banking in the UAE
Feature | Islamic Banking | Conventional Banking |
|---|---|---|
Return and cost model | Profit rates and agreed markups; current accounts usually pay no return | Interest on deposits and loans, with floating or fixed rates |
Financing products | Murabaha, ijara, musharaka; asset-backed and transparent | Overdrafts, term loans, letters of credit, invoice discounting |
Regulatory oversight | Central Bank plus Sharia boards and the Higher Sharia Authority | Central Bank licensing, AML and KYC rules |
Suitability for free zone companies | Strong fit for equipment, inventory and values-led investors | Strong fit for flexible credit and broad trade finance |
Typical onboarding time | 2 to 6 weeks for full corporate accounts | 2 to 6 weeks for full corporate accounts; days at digital banks |
Why the Choice Matters for Free Zone Owners
Your choice shapes fees, financing structure and investor perception. Free zone companies face extra due diligence under either model, so picking wrong can mean re-opening an account and losing weeks. Take a business bank account in the UAE for a Dubai South trading company that needs trade finance within six months: the bank's product menu matters from day one.
How Islamic and Conventional Business Accounts Differ in Practice

Islamic accounts use wakala or qard structures and pay profit rather than interest. Conventional accounts pay interest and offer overdrafts. Payments, IBANs, cards and online banking work almost identically, so islamic vs conventional banking differences show up mainly in financing and paperwork.
Minimum balances commonly range from AED 10,000 to AED 50,000, depending on bank and tier.
Islamic current accounts typically pay no return.
Compare tariff sheets, not product labels.
For inventory, murabaha means the bank buys the goods and sells them to you at an agreed markup. A conventional trade loan hands you cash instead. Invoice discounting can advance up to 80% of invoice value. Digital banks like Wio add faster onboarding; see this digital banking vs traditional banking in the UAE comparison.
Does Islamic banking cost more than conventional banking?
Not by default. Fees and minimum balances are similar across both models. The cost difference sits in the financing markup or rate, so request written quotes from each bank and compare the total repayment, not the label.
Which UAE Banks Suit Free Zone Companies Best
For islamic vs conventional banking: which is better for a UAE business, the bank matters as much as the model. Emirates NBD, Mashreq, FAB and ADCB suit established companies, RAKBank suits small businesses, and Wio suits digital-first startups.
Established banks offer trade finance and multi-currency accounts, with higher scrutiny and balances.
Several groups run Islamic windows or subsidiaries; verify per bank.
Full corporate decisions typically take 2 to 6 weeks.
A new consultancy could open a Wio account in days, then apply to a larger bank with transaction history. Wio has fewer complex financing options, though. Founders who need fully Sharia-compliant operations should ask any bank for its Sharia board certificate and product list, and read our guide to Islamic banking Sharia compliance. See also the best banks for startups in UAE.
Steps to Choose and Open the Right Account for a Free Zone Company
Define your financing needs, shortlist two or three banks, prepare consistent documents, and follow up within five working days. A complete, matching document set is the biggest factor in avoiding rejection when weighing islamic vs conventional banking: which is better for a UAE business.
Define priorities: trade finance, overdraft, equipment, payroll, and whether Sharia compliance is a requirement or preference.
Shortlist 2 to 3 banks and request Islamic and conventional tariff sheets side by side.
Prepare documents in 3 to 5 working days: trade license, MOA, UBO details, passports, Emirates ID or visa copies, proof of address, contracts.
Apply, explain suppliers, customers and volumes, and answer compliance queries within 24 to 48 hours.
One logistics startup, for instance, prioritised equipment ijara plus multi-currency receipts and shortlisted Mashreq, RAKBank and Wio. Read what UAE banks look for in a startup application before you submit.
Common Rejection Reasons and How to Avoid Them
Most rejections in islamic vs conventional banking applications come from mismatched documents, unclear models, unclear ownership or unrealistic turnover. Keep documents consistent, show contracts and invoices, and declare source of funds clearly.
A license activity that differs from the pitch deck triggers queries.
Missing UBO or source-of-funds evidence stalls files.
Islamic banks may exclude activities such as alcohol or gambling.
Avoid applying to too many banks in parallel.
Prepare a one-page business summary and keep your UAE address, phone and website consistent. Banks often ask for six months of trading history before financing, so a digital account first can build that record.
Making the Final Decision With DSBH Banking Support
Choose Islamic banking if Sharia compliance or asset-backed financing matters, and conventional banking if you need broad products or flexible credit. Many free zone firms hold both, such as an Islamic account for operations and a conventional line for working capital.
Dubai South Business Hub supports free zone company formation, trade licenses and residency visa packages tied to your license, plus banking introductions. Start with banking 101 for startups in the UAE.
Your Next Move
Islamic vs conventional banking: which is better for a UAE business comes down to financing structure, values and growth plans. Both are Central Bank regulated and both work for free zone companies. Compare tariffs, match the bank to your activity, and consider holding both. Speak with DSBH about company formation and banking support so your license, documents and bank choice align before you apply.
References
Frequently Asked Questions