Topic Summary
What Is the MOHRE Bank Guarantee and Why Every Employer Needs One
The MOHRE bank guarantee Dubai is a financial deposit an employer lodges with a UAE-approved bank, or replaces with an approved insurance policy, to protect workers' end-of-service entitlements and unpaid wages. The standard amount is AED 3,000 per sponsored worker and is held fo
Bank Guarantee vs. Insurance: How Each Route Works
Bank Guarantee vs. Insurance: How Each Route Works
Step-by-Step Guide to Lodging the MOHRE Bank Guarantee Dubai
To lodge the MOHRE bank guarantee in Dubai, open or confirm your corporate bank account, request a guarantee instrument in favour of MOHRE, submit it through a Tasheel centre or the Tasheel portal, and wait for MOHRE to link the guarantee to your establishment file before applyin
Cost Breakdown: What You Pay Once and What Recurs
The MOHRE bank dubai cost has two layers: the guarantee deposit of AED 3,000 per worker (refundable) and the bank's issuance fee (non-refundable, varies by bank). The insurance alternative replaces the deposit with a recurring annual premium per worker. Tasheel transaction fees a
Common Delays and How to Clear Them
The most common MOHRE bank guarantee Dubai delays are an inactive establishment card, a bank account not yet linked to the employer's MOHRE file, missing authorised-signatory documents at the bank, and guarantee amounts that do not match the exact per-worker figure MOHRE expects.
In 2026, the MOHRE bank guarantee Dubai requirement costs AED 3,000 per sponsored worker on the cash deposit route (MOHRE, 2026). Every private-sector employer activating a MOHRE work permit must lodge this guarantee before the permit clears. Non-compliance blocks all new permit applications immediately. The insurance alternative replaces the deposit but carries an annual renewal obligation per worker. Bank account KYC in the UAE takes 5 to 20 working days (Central Bank of the UAE, 2026), so the full compliance sequence from license to first active permit typically runs two to four weeks. This article explains what the MOHRE bank guarantee Dubai obligation covers, how the two routes differ, what each costs, the exact steps to lodge the guarantee, and the delays that most commonly push timelines past the standard window.
What Is the MOHRE Bank Guarantee and Why Every Employer Needs One
The MOHRE bank guarantee Dubai is a financial deposit an employer lodges with a UAE-approved bank, or replaces with an approved insurance policy, to protect workers' end-of-service entitlements and unpaid wages. The standard amount is AED 3,000 per sponsored worker and is held for the duration of employment.
Legal Basis for the Employer Obligation
The guarantee is mandated under UAE Federal Decree-Law No. 33 of 2021 on the Regulation of Labour Relations, with MOHRE as the administering authority (MOHRE, 2026). It applies to all private-sector employers regardless of company size. There's no minimum headcount threshold that exempts small businesses.
MOHRE links permit issuance directly to guarantee status inside its Tasheel portal. If your guarantee isn't confirmed, the system blocks new work permit applications automatically. Fines can also apply for non-compliance, compounding the delay.
A logistics company in Dubai with 12 workers, for example, must lodge AED 36,000 (12 x AED 3,000) before its first batch of work permits clears, or enrol all 12 workers in an approved insurance scheme instead.
Who Is Covered and Who Is Exempt
The obligation covers all private-sector employers sponsoring non-UAE national workers under MOHRE work permits. The following categories fall outside MOHRE's guarantee scope:
Domestic workers (governed under a separate regulatory framework)
Certain government-entity staff
Workers sponsored under DIFC or ADGM authorities rather than MOHRE
Free zone companies that use MOHRE work permits, rather than their free zone's own permit system, are subject to the same guarantee requirement. A company at Dubai South Business Hub Free Zone that hires staff on MOHRE work permits must lodge the guarantee for each of those workers, even though the license is free zone-based. Any exemption thresholds for micro-employers are UNVERIFIED: confirm directly with MOHRE before assuming an exemption applies.
You can check your establishment's current compliance status through the MOHRE inquiry system before you approach the bank.
Bank Guarantee vs. Insurance: How Each Route Works
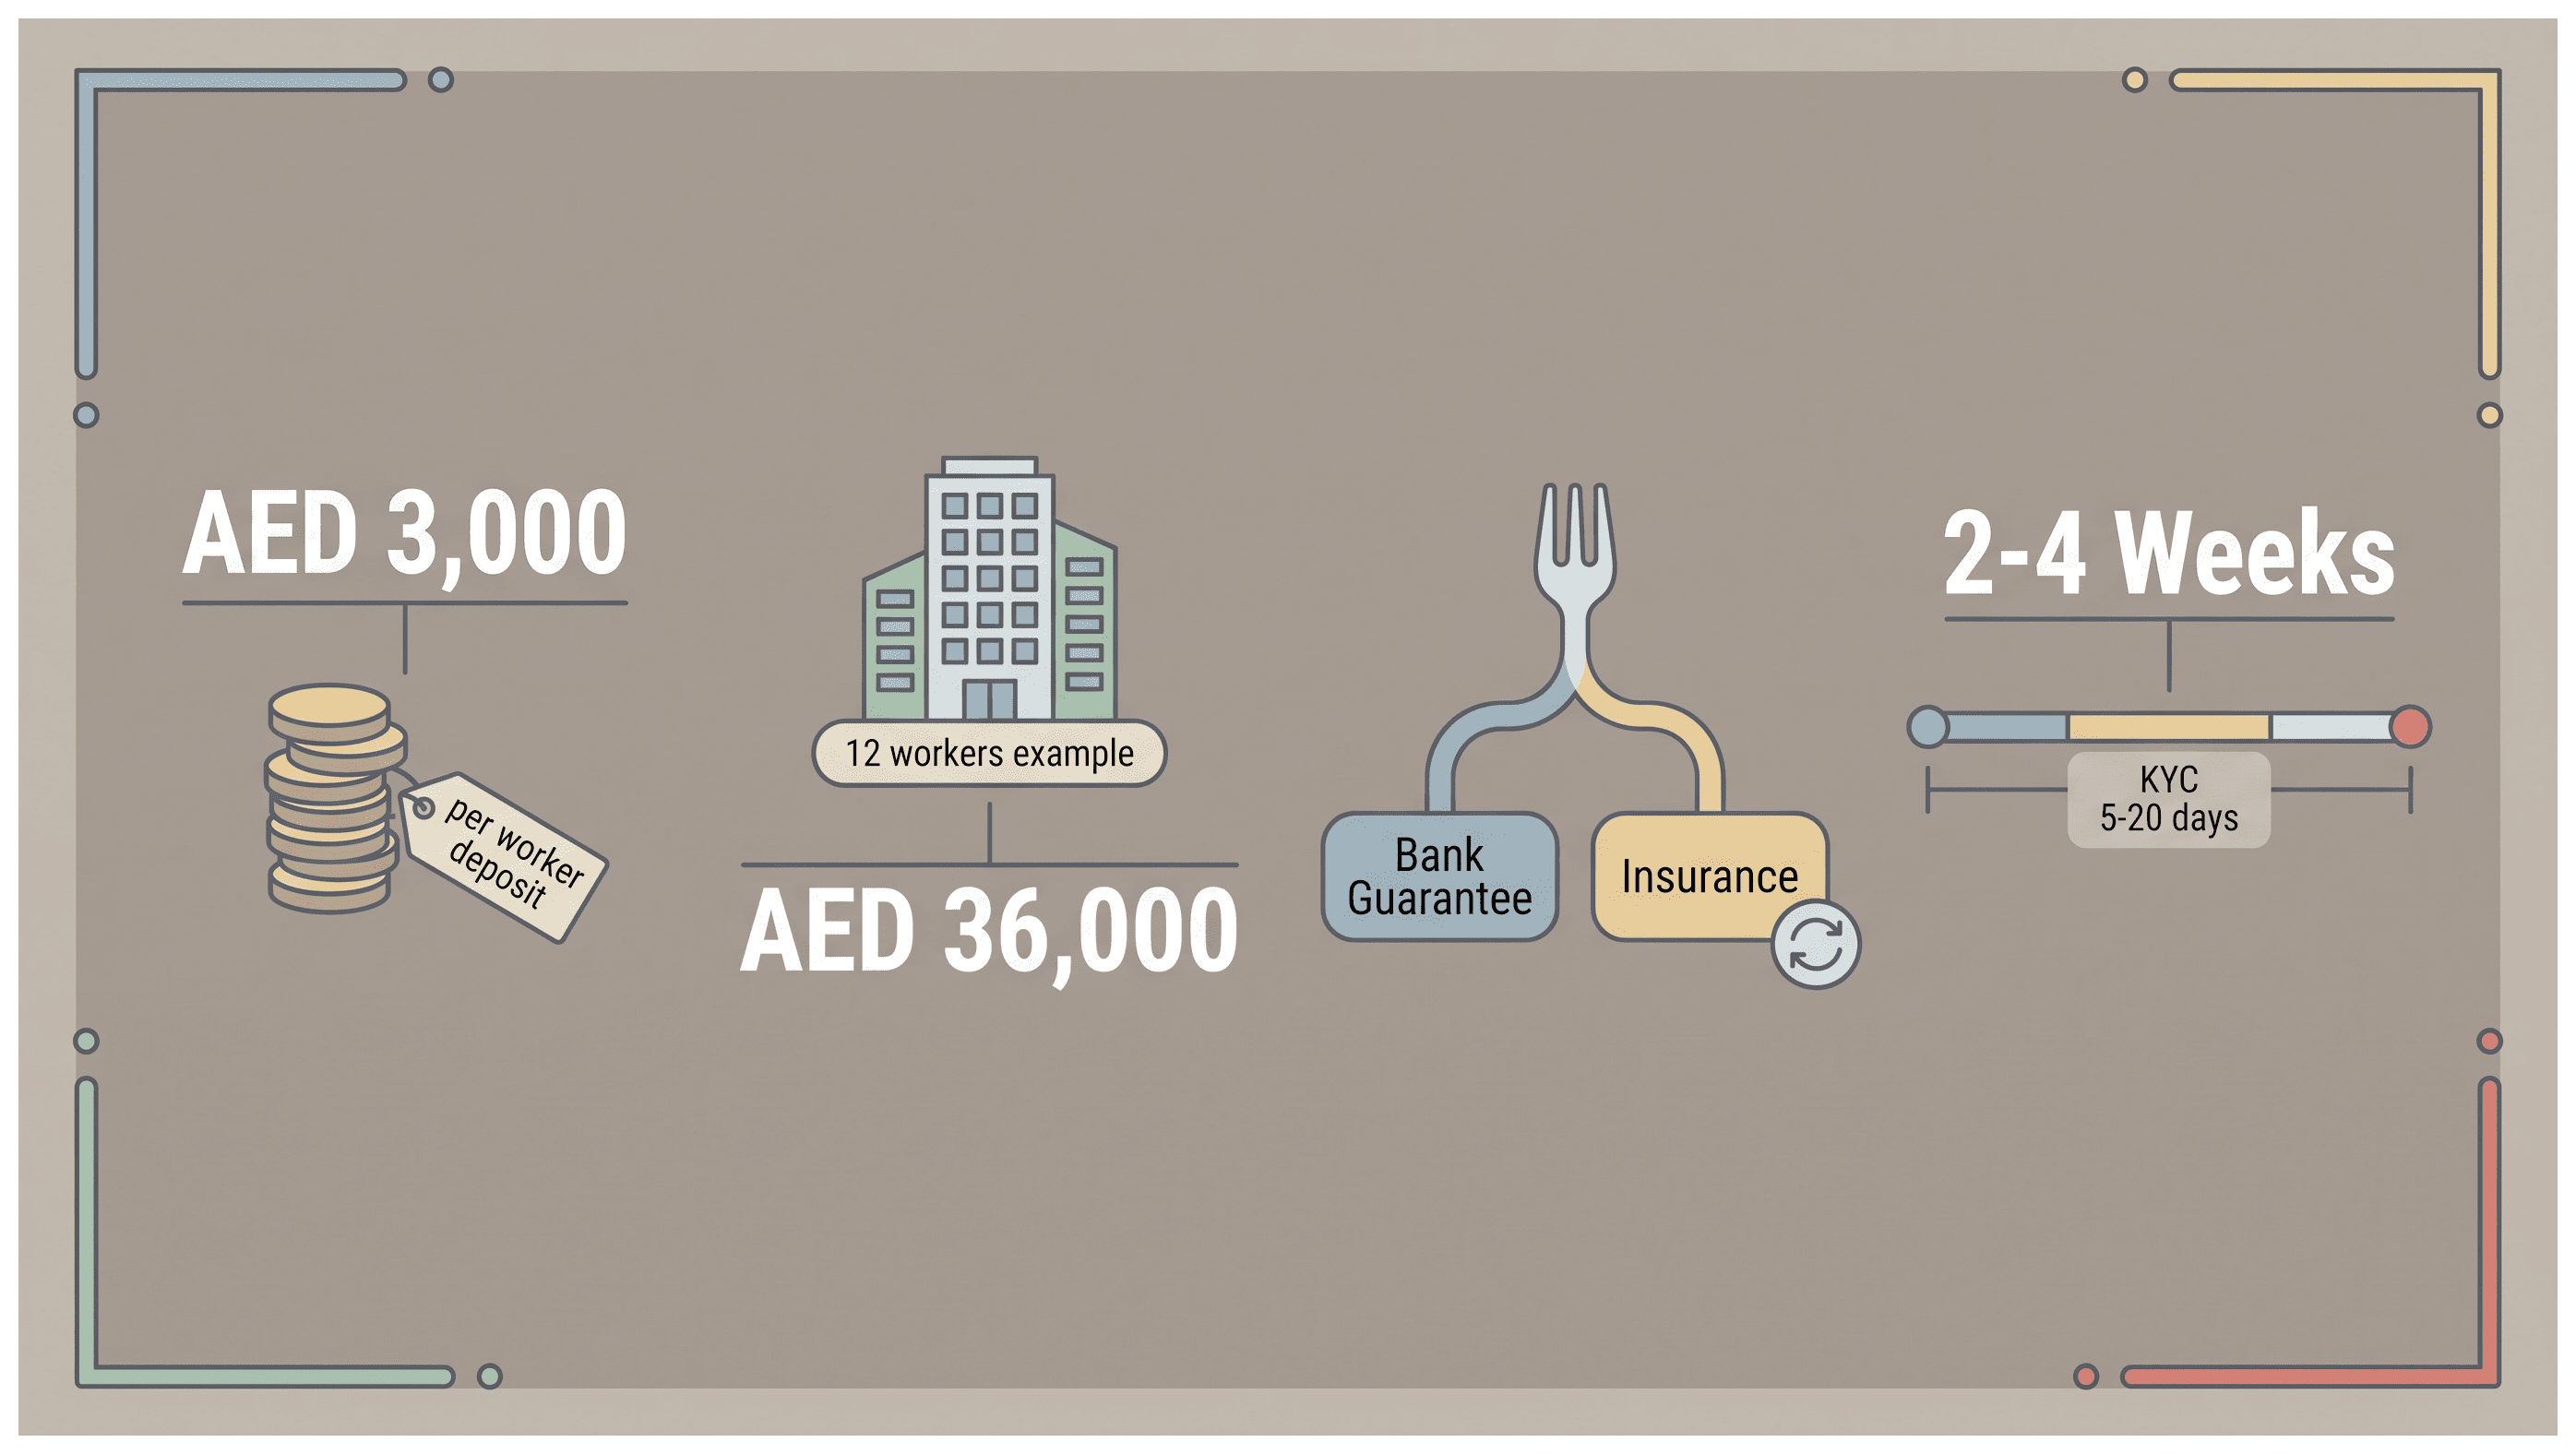
Employers can meet the MOHRE bank guarantee Dubai requirement through a cash or bank-issued guarantee of AED 3,000 per worker, lodged via the Tasheel network, or by enrolling workers in a MOHRE-approved wage protection insurance policy. The insurance route replaces the cash deposit but must be renewed annually per worker.
How the Bank Guarantee Route Works
The employer instructs a UAE-licensed bank to issue a guarantee in favour of MOHRE. The bank holds the equivalent cash or debits the employer's credit facility for the covered amount. The instrument is then lodged through a Tasheel service centre or the Tasheel online portal and linked to the employer's MOHRE establishment file.
The AED 3,000 per-worker figure is the published standard. The bank may charge a separate issuance fee on top of this amount (see the cost section). The guarantee stays in place until the worker's permit is cancelled and end-of-service obligations are settled, at which point the employer applies for a refund.
An employer with a five-person team, for instance, asks their bank for a guarantee of AED 15,000 in favour of MOHRE. The bank issues the instrument; the employer uploads it via Tasheel and receives permit approval within the standard one to three working day processing window.
How the Approved Insurance Alternative Works
MOHRE's approved insurance scheme lets employers pay an annual premium per worker instead of locking up a cash deposit. Premiums vary by insurer and worker category. Note: the per-worker annual premium is UNVERIFIED, confirm the current figure with MOHRE or a MOHRE-approved insurer before committing to this route.
The policy must be renewed before expiry. If it lapses, MOHRE's system flags the establishment as non-compliant and blocks new permit applications immediately. The insurance route is often preferred by employers with large or fast-changing headcounts because it avoids tying up significant capital.
A retail chain with 80 workers, for example, chooses the insurance route to avoid lodging AED 240,000 in bank guarantees. It pays an annual premium per worker to a MOHRE-approved insurer and renews the policy each year. Free zone companies using MOHRE work permits face the same obligation. The free zone license does not create an exemption, so budget for the guarantee from day one of your first work permit application.
Step-by-Step Guide to Lodging the MOHRE Bank Guarantee Dubai
To lodge the MOHRE bank guarantee in Dubai, open or confirm your corporate bank account, request a guarantee instrument in favour of MOHRE, submit it through a Tasheel centre or the Tasheel portal, and wait for MOHRE to link the guarantee to your establishment file before applying for work permits.
MOHRE Bank Guarantee vs. Insurance Alternative: Cost and Key Differences
Feature | Bank Guarantee Route | Insurance Alternative |
|---|---|---|
Deposit amount per worker | AED 3,000 cash deposit per worker (MOHRE, 2026) | No cash deposit; annual premium replaces it (UNVERIFIED: confirm premium with insurer) |
Refundable at end of employment | Yes, AED 3,000 per worker returned after permit cancellation and MOHRE clearance | No, annual premiums paid are not recovered at end of employment |
Annual renewal required | No, guarantee stays in place until permit cancellation | Yes, policy must be renewed before expiry or MOHRE flags non-compliance |
Capital tied up | AED 3,000 per worker locked in bank guarantee for employment duration | No capital locked up; premium is an operating expense |
Best suited for | Small, stable headcounts where capital can be committed long-term | Large or fast-growing teams where tying up capital is impractical |
Key risk if missed | Permit applications blocked; MOHRE may draw on guarantee if wage complaint is upheld | Policy lapse triggers immediate non-compliance flag; all new permits blocked until renewed |
Step 1: Confirm Your Bank Account and Establishment File
You need an active UAE corporate bank account before you can instruct a guarantee. Without one, the bank has no account to debit or secure the instrument against. Confirm your MOHRE establishment card is also active, this is the employer record MOHRE uses to link all guarantees and permits.
If your establishment card has lapsed or was never issued, renew or obtain it through Tasheel first. Guarantee lodgement will be rejected without a valid card. For guidance on bank account opening in the UAE, review the requirements before approaching your bank.
A newly licensed company at Dubai South Business Hub Free Zone, for example, opens its corporate account, receives the establishment card, and then approaches its bank in that exact order to avoid a rejection at the guarantee stage.
Step 2: Instruct Your Bank to Issue the Guarantee
Provide your bank with the MOHRE guarantee wording and the exact amount: AED 3,000 multiplied by the number of workers you intend to sponsor in this batch. The bank issues a guarantee letter addressed to MOHRE. Processing at the bank typically runs two to five working days depending on the institution (UNVERIFIED: confirm with your specific bank).
Some banks require a board resolution or authorised signatory letter before issuing the instrument. Prepare these in advance. An employer sponsoring three workers, for instance, requests a guarantee of AED 9,000, provides a board resolution, and receives the instrument within three working days.
Step 3: Submit Through Tasheel and Await Linkage Confirmation
Upload or present the bank guarantee instrument at a Tasheel service centre or through the Tasheel online portal under your employer account. MOHRE reviews the submission and links the guarantee to your establishment file within one to three working days (MOHRE, 2026).
You'll receive a confirmation notification through the MOHRE portal or Tasheel. Only after this confirmation can you proceed with work permit applications. Keep the reference number, you'll need it when applying for a refund after permit cancellation. After uploading on a Monday, an employer typically receives linkage confirmation by Wednesday and can submit the first work permit application the same afternoon.
Cost Breakdown: What You Pay Once and What Recurs
The MOHRE bank dubai cost has two layers: the guarantee deposit of AED 3,000 per worker (refundable) and the bank's issuance fee (non-refundable, varies by bank). The insurance alternative replaces the deposit with a recurring annual premium per worker. Tasheel transaction fees apply in both routes.
One-Off vs. Recurring Cost Components
Cost Type | One-Off | Recurring |
|---|---|---|
Guarantee deposit | AED 3,000 per worker, refundable on permit cancellation (MOHRE, 2026) | Not applicable (held, not spent) |
Bank issuance fee | UNVERIFIED: confirm with your bank, non-refundable, varies by institution and guarantee size | Not applicable |
Insurance premium | Not applicable | UNVERIFIED: annual per-worker premium, confirm with a MOHRE-approved insurer |
Tasheel service fee | UNVERIFIED: per transaction, confirm at a Tasheel centre | Applies on each submission or renewal transaction |
What the guarantee does NOT cover: end-of-service gratuity payments, work permit fees, visa processing, medical fitness tests, Emirates ID fees, or fines for late lodgement. These are separate costs entirely.
For a team of five workers on the bank guarantee route, an employer locks up AED 15,000 (refundable) and pays a one-off bank issuance fee (UNVERIFIED). On the insurance route, the AED 15,000 deposit is replaced by an annual premium, but that premium is not recovered at the end of employment.
How and When the Guarantee Is Refunded
The employer applies for a refund through Tasheel after the worker's work permit is cancelled and MOHRE confirms no outstanding wage or end-of-service claims. Refund processing time is UNVERIFIED: confirm the current timeline with MOHRE or a Tasheel centre before relying on a specific window.
If a worker files a wage complaint that is upheld, MOHRE may draw on the guarantee to settle the claim before issuing any refund to the employer. Employers switching from the bank guarantee route to the insurance route mid-employment must apply to release the existing deposit separately. An employer whose worker resigns and completes permit cancellation applies for the AED 3,000 refund through Tasheel; the funds return once MOHRE clears the file.
Is the insurance route cheaper than the bank guarantee?
It depends on employment duration and team size. For short contracts, the insurance premium may cost more in total than the refundable AED 3,000 deposit. For large or fast-growing teams, the insurance route avoids locking up significant capital, making cash flow management easier even if the premium is a sunk cost annually.
Common Delays and How to Clear Them
The most common MOHRE bank guarantee Dubai delays are an inactive establishment card, a bank account not yet linked to the employer's MOHRE file, missing authorised-signatory documents at the bank, and guarantee amounts that do not match the exact per-worker figure MOHRE expects. Each can add three to ten working days.
Establishment Card and Portal Mismatches
If the employer's MOHRE establishment card is expired, or the trade name on the card does not match the license exactly, Tasheel rejects the submission. The employer must correct the card before re-submitting. Portal mismatches, an outdated authorised signatory or a wrong Emirates ID linked to the account, add a correction cycle of several working days.
Run a MOHRE portal check before instructing the bank guarantee. The MOHRE inquiry system flags establishment card status in real time, so you can catch issues before the bank is involved (u.ae, 2026).
A company
References
Frequently Asked Questions