Topic Summary
What Is Opening a UAE Corporate Bank Account as a Bangladeshi Entrepreneur and Why It Matters
Opening a UAE corporate bank account as a Bangladeshi entrepreneur means getting a Central Bank-regulated bank to approve your free zone company for banking. You need it to receive client payments, pay visa and license fees, run payroll and keep business funds separate from personal money.
Licensing and Ownership Rules That Shape Your Bank Application
Licensing and Ownership Rules That Shape Your Bank Application
Documents Bangladeshi Entrepreneurs Must Prepare
For a UAE corporate bank account, banks typically ask for the trade license, incorporation documents, passport, Emirates ID or entry stamp, proof of address, a business plan and source-of-funds evidence. Residence details are issued through the Federal Authority for Identity, Citizenship, Customs and Port Security . Many banks accept a valid free zone license as the main corporate document. See the banking requirements for Dubai South Business Hub companies .
Numbered Process for Opening Your Corporate Account
Opening a UAE corporate bank account as a Bangladeshi entrepreneur runs in six stages. Timelines vary by bank, and incomplete files cause most delays. You can also open a corporate bank account before your UAE residence visa .
Compliance Checks Banks Expect From Bangladeshi Founders
Banks run KYC, AML and sanctions screening, then ask about beneficial owners, volumes and counterparties. Declare your corridors honestly, for example inflows from UAE clients and outflows to Bangladeshi suppliers.
Choosing the Right Bank and Account Structure
Pick a bank by fees, minimum balance, onboarding speed and currency options. Over 40% of UAE companies transact in at least two currencies, so consider multiple currency corporate bank accounts in the UAE . An exporter holding USD and AED avoids repeated conversion losses.
Common Rejection Reasons and How to Avoid Them
Banks reject unclear activity, weak source-of-funds evidence, inconsistent documents or high-risk profiles. Opening a UAE corporate bank account as a Bangladeshi entrepreneur goes smoother when your license, contracts and website match. Read why UAE banks reject corporate account applications .
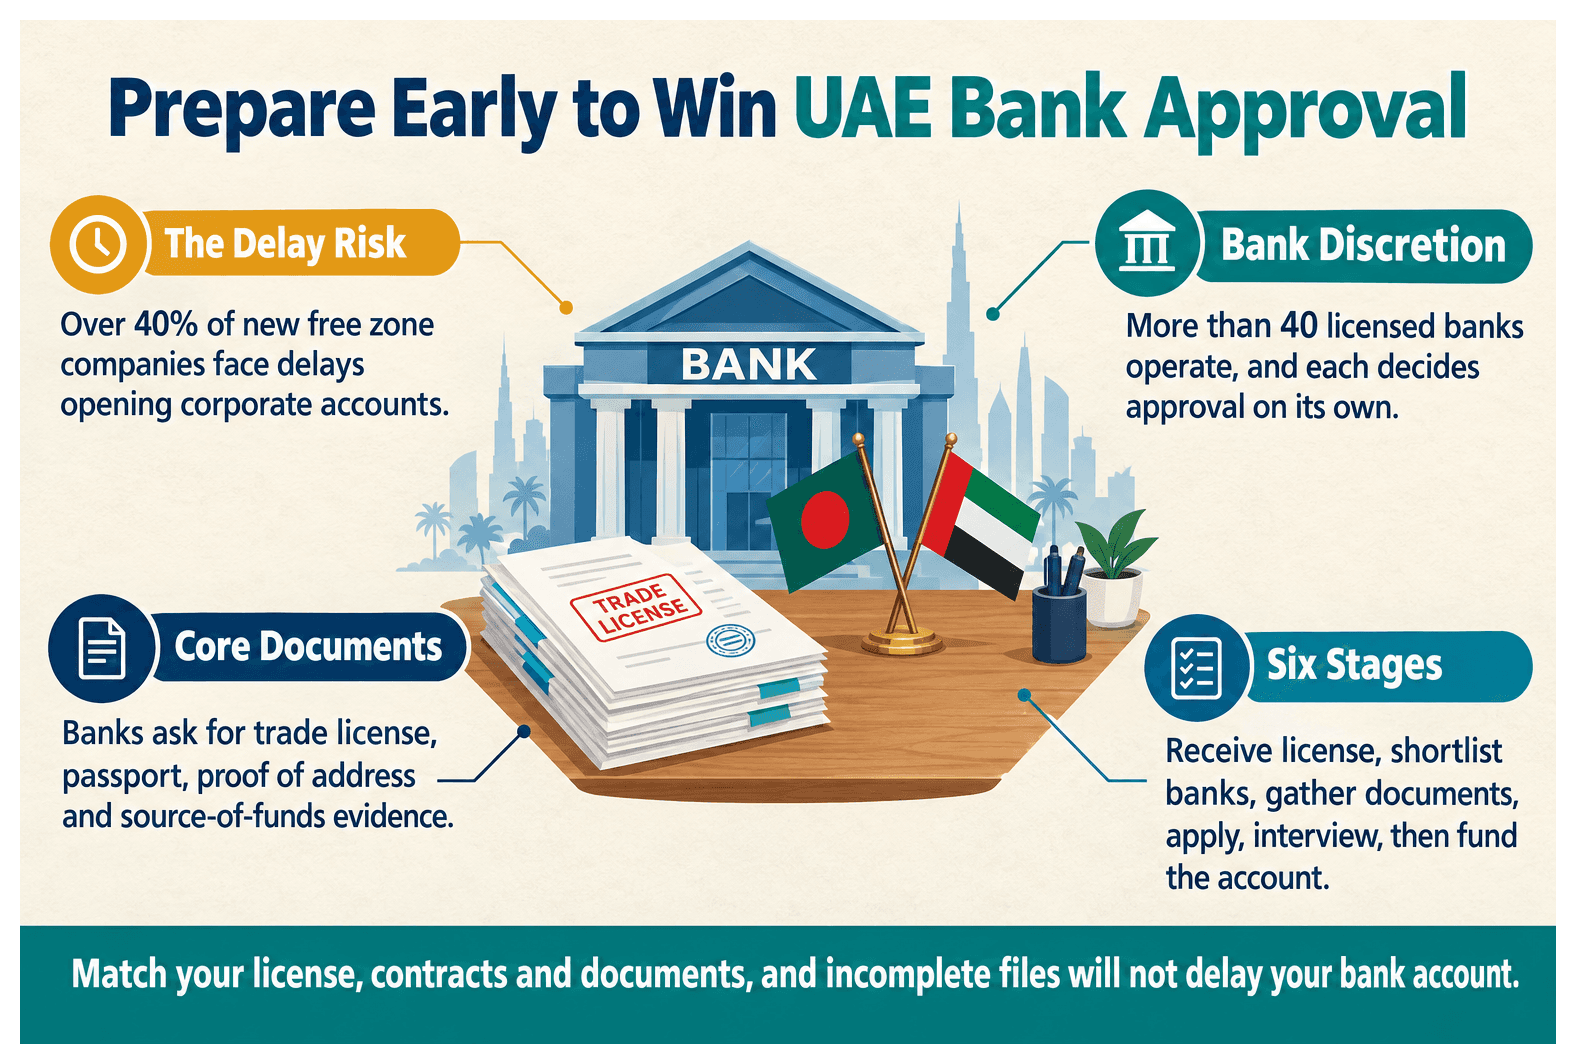
Over 40% of new UAE free zone companies face delays opening a corporate bank account. This guide to opening a UAE corporate bank account as a Bangladeshi entrepreneur covers licensing, documents, compliance and rejection risks, so you can approach banks prepared.
What Is Opening a UAE Corporate Bank Account as a Bangladeshi Entrepreneur and Why It Matters
Opening a UAE corporate bank account as a Bangladeshi entrepreneur means getting a Central Bank-regulated bank to approve your free zone company for banking. You need it to receive client payments, pay visa and license fees, run payroll and keep business funds separate from personal money.
How UAE Banks Regulate Corporate Accounts
More than 40 licensed banks operate in the UAE, all supervised by the Central Bank of the UAE. Onboarding follows KYC (know your customer) and anti-money-laundering rules. Approval stays at each bank's discretion, so a Dhaka-based trader with a fresh license still faces the bank's own risk review.
Why the Account Matters Beyond Payments
Pays visa fees and payroll.
Lets you invoice UAE clients properly.
Keeps accounting records clean.
Builds history for trade finance later.
Licensing and Ownership Rules That Shape Your Bank Application
Your license and ownership structure decide how banks assess you. At Dubai South Business Hub Free Zone, a Bangladeshi entrepreneur can apply for a sole-shareholder license with one visa allocation, used by the shareholder. Our guide to setting up a business in Dubai as a Bangladeshi national explains the visa rules.
Choose an activity banks understand. A garment sourcing founder who licenses trading with supplier contracts to match clears review faster than one with a vague activity. Keep the description identical across your license, invoices and website.
Documents and Purpose for Bangladeshi Applicants
Document | Why Banks Ask For It |
|---|---|
Trade license | Confirms legal existence and approved activity |
Passport and visa or Emirates ID | Verifies the shareholder's identity and status |
Proof of address | Confirms residence in the UAE and Bangladesh |
Source-of-funds evidence | Shows where your capital came from |
Contracts or invoices | Proves the business is real and matches the license |
Documents Bangladeshi Entrepreneurs Must Prepare
For a UAE corporate bank account, banks typically ask for the trade license, incorporation documents, passport, Emirates ID or entry stamp, proof of address, a business plan and source-of-funds evidence. Residence details are issued through the Federal Authority for Identity, Citizenship, Customs and Port Security. Many banks accept a valid free zone license as the main corporate document. See the banking requirements for Dubai South Business Hub companies.
Prepare six months of personal statements and a signed supplier agreement. Those two items answer most compliance queries. Add a utility bill from Dhaka for address proof.
Numbered Process for Opening Your Corporate Account
Opening a UAE corporate bank account as a Bangladeshi entrepreneur runs in six stages. Timelines vary by bank, and incomplete files cause most delays. You can also open a corporate bank account before your UAE residence visa.
Receive your license.
Shortlist banks by balance and fees.
Gather documents.
Submit the application.
Complete the compliance interview.
Fund the account and request online banking.
Expect questions on suppliers, monthly turnover and countries of trade. Review typically takes several weeks.
Compliance Checks Banks Expect From Bangladeshi Founders
Banks run KYC, AML and sanctions screening, then ask about beneficial owners, volumes and counterparties. Declare your corridors honestly, for example inflows from UAE clients and outflows to Bangladeshi suppliers.
Register for corporate tax with the Federal Tax Authority before the review. VAT registration applies once annual taxable supplies reach AED 375,000 (Ministry of Finance).
Choosing the Right Bank and Account Structure
Pick a bank by fees, minimum balance, onboarding speed and currency options. Over 40% of UAE companies transact in at least two currencies, so consider multiple currency corporate bank accounts in the UAE. An exporter holding USD and AED avoids repeated conversion losses.
Digital banks onboard simple profiles faster. Traditional banks offer credit and trade finance. A startup might begin digital, then add a traditional bank later.
Common Rejection Reasons and How to Avoid Them
Banks reject unclear activity, weak source-of-funds evidence, inconsistent documents or high-risk profiles. Opening a UAE corporate bank account as a Bangladeshi entrepreneur goes smoother when your license, contracts and website match. Read why UAE banks reject corporate account applications.
Trading license with no supplier contracts.
Cash-heavy model with unexplained funds.
No website or client evidence.
After a decline, ask for the reason category, fix the gaps and try a better-aligned bank.
Next Steps
Opening a UAE corporate bank account as a Bangladeshi entrepreneur is manageable when your license, documents and story align. Contact Dubai South Business Hub Free Zone to secure your sole-shareholder license and residency visa package, then prepare your banking file.
References
Frequently Asked Questions