Topic Summary
What Is Opening a UAE Corporate Bank Account as a Mexican Entrepreneur and Why It Matters
Opening a UAE Corporate Bank Account as a Mexican Entrepreneur means registering a free zone company, then applying to a Central Bank-regulated bank with your trade license, passports and business plan. The account lets you invoice clients, pay suppliers and receive USD or MXN-linked flows.
Documents and Eligibility Mexican Founders Need Before Applying
Documents and Eligibility Mexican Founders Need Before Applying
Numbered Process for Opening a UAE Corporate Bank Account as a Mexican Entrepreneur
Opening a UAE Corporate Bank Account as a Mexican Entrepreneur follows five stages: license, bank shortlist, documents, application with KYC interview, then activation and funding. Budget several weeks, since first-timers often underestimate by about three weeks.
Compliance, Fees and Tax Points to Plan Around
UAE banks apply AML and KYC rules overseen by the Central Bank, and fees differ by institution. Corporate tax and VAT registration with the Federal Tax Authority also affect banking, so align your corporate bank account and accounting from day one.
Common Rejection Reasons and How Mexican Founders Avoid Them
Applications are usually declined for vague activity, unclear funds, thin documents or license mismatches. A Mexican entrepreneur avoids this with evidence of clients and suppliers and one consistent file.
Next Steps for Your Application
Opening a UAE Corporate Bank Account as a Mexican Entrepreneur works when your license, documents and business story align. Contact Dubai South Business Hub to set up your company, time your residency visa and prepare your bank application.
The UAE has more than 40 licensed banks regulated by the Central Bank of the UAE [1], yet roughly 40% of first-time founders hit a delay or decline. Opening a UAE Corporate Bank Account as a Mexican Entrepreneur is manageable once you know what banks check. This guide shows you the documents, the steps and the pitfalls.
What Is Opening a UAE Corporate Bank Account as a Mexican Entrepreneur and Why It Matters
Opening a UAE Corporate Bank Account as a Mexican Entrepreneur means registering a free zone company, then applying to a Central Bank-regulated bank with your trade license, passports and business plan. The account lets you invoice clients, pay suppliers and receive USD or MXN-linked flows.
How Corporate Banking Works for Mexican Founders
Each bank sets its own risk appetite on top of federal rules. A free zone trade license is the core document, and a residence visa isn't always needed at application. Mexican ownership is welcome. Banks care about source of funds, substance and transparency.
Picture a Guadalajara electronics distributor with a Dubai South Business Hub company, re-exporting to the Gulf. It needs dirham and USD accounts to pay logistics providers. Dubai South offers 100% foreign ownership, a logistics-focused ecosystem, and license plus residency visa packages.
Corporate Bank Account Requirements Checklist for Mexican Founders
Feature | Requirement | What Banks Typically Expect |
|---|---|---|
Trade license and incorporation papers | License, articles, share certificate, lease | Activities matching real operations |
Passports of shareholders and signatories | Valid passport copies | Clear ownership chain |
Proof of address and CV | Mexican address proof, professional CV | Recent, translated if requested |
Business plan and sample contracts | Two-page profile, invoices or contracts | Named clients, suppliers, expected turnover |
Source-of-funds evidence | Bank statements, prior business accounts | Funds traceable to legitimate income |
Why a Local Account Beats Offshore Alternatives
Faster settlement with UAE customers and payroll.
Credibility with landlords and government portals.
Cleaner VAT and corporate tax reporting.
A Monterrey consultancy can pay UAE contractors in dirhams without fees on every transfer. For currency strategy, see multiple currency corporate bank accounts in the UAE.
Documents and Eligibility Mexican Founders Need Before Applying
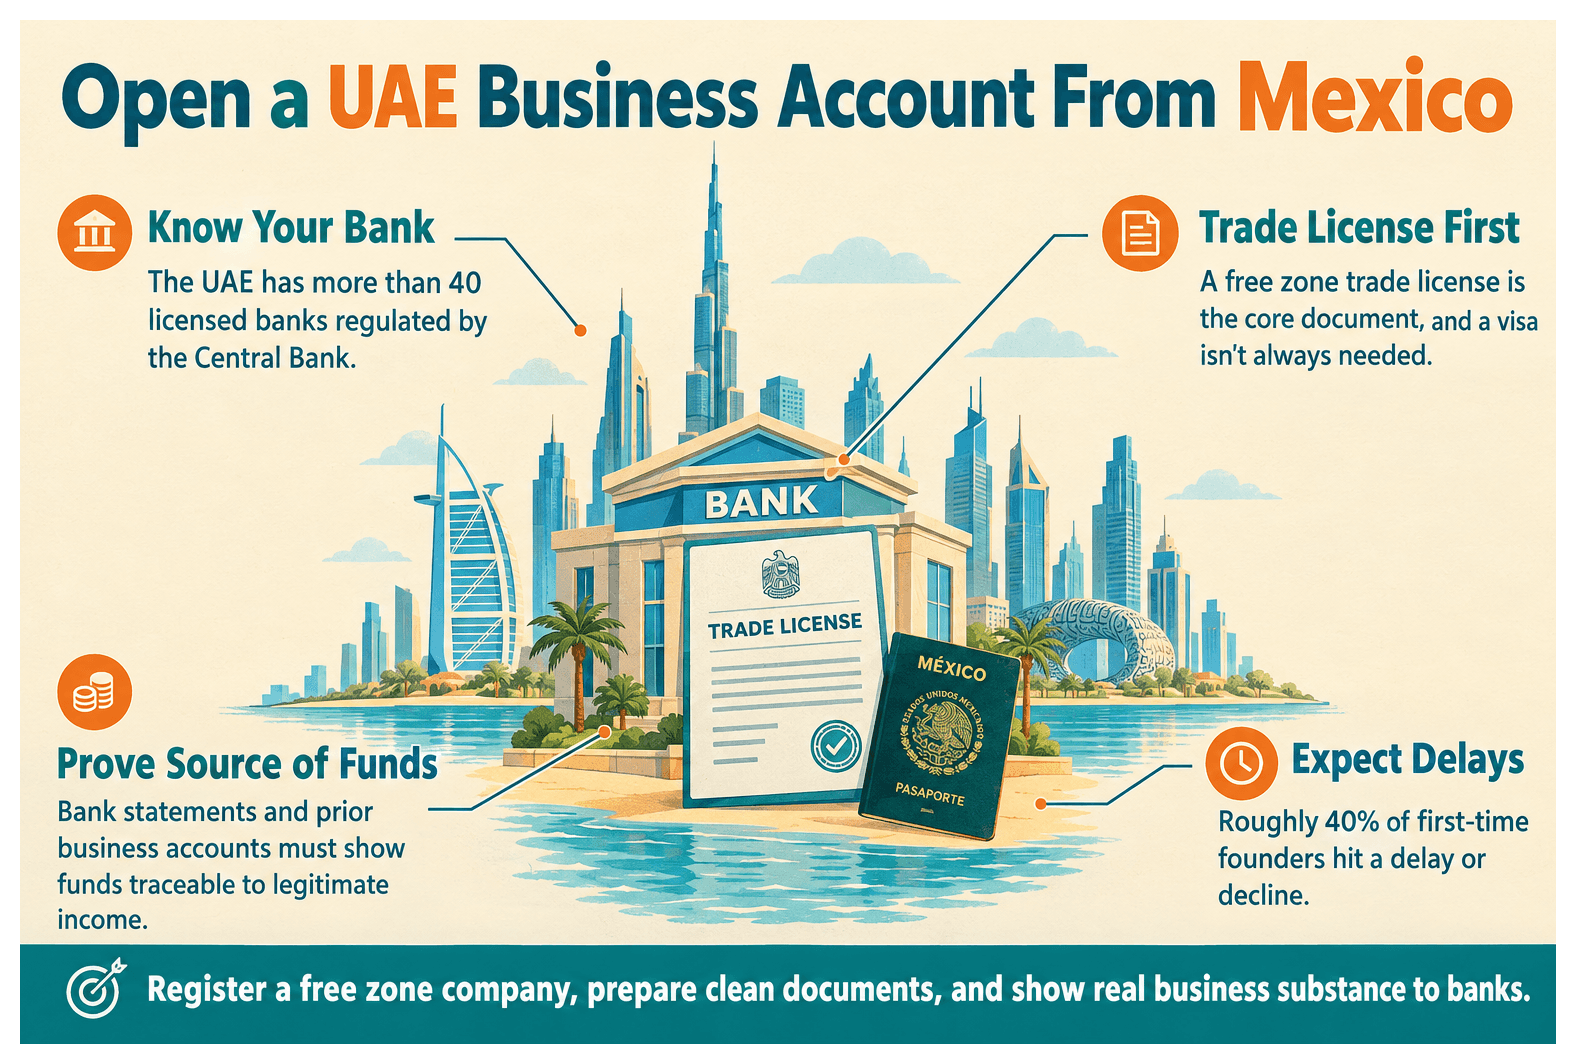
Banks typically ask a Mexican entrepreneur for the trade license, incorporation documents, passports, proof of address, a business plan, contracts and source-of-funds evidence. Requirements vary, so confirm the current corporate bank account checklist, including any attestation or translation of Mexican documents.
Core Company and Personal Documents
Trade license, articles, share certificate and registered lease.
Passports for shareholders and signatories.
Emirates ID once the Federal Authority for Identity, Citizenship, Customs and Port Security issues residency.
Mexican proof of address and a CV.
A Mexico City founder might merge everything into one PDF pack.
Choosing Between Applying Before or After Your Visa
Some banks accept non-residents; others prefer residency in place. Read opening a corporate bank account before your UAE residence visa and corporate bank account for non-residents in the UAE. One founder applied remotely from Mexico, then finished KYC in person once the visa landed.
Numbered Process for Opening a UAE Corporate Bank Account as a Mexican Entrepreneur
Opening a UAE Corporate Bank Account as a Mexican Entrepreneur follows five stages: license, bank shortlist, documents, application with KYC interview, then activation and funding. Budget several weeks, since first-timers often underestimate by about three weeks.
Stage 1: Secure the License and Choose the Right Bank
Obtain your Dubai South trade license with real activities.
Compare banks on balances, fees and multi-currency options.
Pick a fit, such as trade finance for a Mexican agri-food trader.
Stage 2: Submit, Pass KYC and Activate
Submit the pack and answer questions on counterparties and turnover.
Attend the KYC interview and sign mandate forms.
Fund the account and set up dual-authorisation online banking.
One founder attached sample invoices upfront and passed first review. See the UAE corporate bank account opening timeline.
Compliance, Fees and Tax Points to Plan Around
UAE banks apply AML and KYC rules overseen by the Central Bank, and fees differ by institution. Corporate tax and VAT registration with the Federal Tax Authority also affect banking, so align your corporate bank account and accounting from day one.
Fees, Minimum Balances and Currency Choices
Get each bank's tariff in writing.
Compare FX margins on USD and MXN-related flows.
Keep a fee comparison sheet.
Check current rates and thresholds with the Ministry of Finance.
Tax Registration, Substance and Mexican Reporting
Register for corporate tax, and VAT where applicable. Keep a lease, contracts and invoices matching your declared activity. Ask a Mexican tax adviser about personal residency and controlled foreign company style reporting. Don't assume any exemption.
Common Rejection Reasons and How Mexican Founders Avoid Them
Applications are usually declined for vague activity, unclear funds, thin documents or license mismatches. A Mexican entrepreneur avoids this with evidence of clients and suppliers and one consistent file.
Red Flags Banks Look For
Unclear ownership chains.
Cash-heavy or high-risk flows.
License says consulting, invoices show goods.
More detail: why some Dubai companies cannot open a bank account.
What to Do If Your Application Is Declined
Ask for the reason, fix the gap, then apply elsewhere with a stronger file. One founder added signed supplier contracts and won approval at a second bank within weeks.
Next Steps for Your Application
Opening a UAE Corporate Bank Account as a Mexican Entrepreneur works when your license, documents and business story align. Contact Dubai South Business Hub to set up your company, time your residency visa and prepare your bank application.
References
Frequently Asked Questions