Topic Summary
What a Failed Bank Account Application Means for Your Dubai Company
A failed bank account dubai application means the bank's compliance team has declined to onboard your company after reviewing its KYC file. The decision is not a ban; it is a rejection by one institution. You can address the documented deficiencies and apply to a different bank w
Common Reasons Banks Reject a Failed Bank Company Dubai File
Common Reasons Banks Reject a Failed Bank Company Dubai File
Requirements to Fix Before Reapplying for a Dubai Bank Account
Before reapplying after a failed bank account dubai rejection, you must update your business plan with specific product lines and counterparty details, complete your KYC document set, obtain any outstanding regulator approvals, and confirm VAT or corporate tax registration status
Failed Bank Dubai Cost: What Fixing the Problem Will Set You Back
The failed bank dubai cost of rectifying a rejection depends on whether you need to amend your license activity, obtain a secondary regulatory approval, or restructure the company. License amendment fees and regulatory approval costs vary by activity; base packages at Dubai South
Step-by-Step Guide to Reapplying After a Failed Bank Account Dubai Rejection
To reapply after a failed bank account dubai rejection: review the rejection letter, fix the identified document or activity gap, update your business plan, select a bank matched to your activity type, submit a complete KYC file, and attend the in-person interview. Never apply to
Which Banks in the UAE Suit Which Business Activity
UAE banks segment their SME onboarding by activity risk. Service, ICT, and consultancy companies generally find retail SME banks accessible. Trading companies benefit from banks with trade-finance desks. Regulated activities such as healthcare or financial services need a bank wh
Setting Up a New Dubai Company After a Failed Bank Account: When It Makes Sense to Start Fresh
Starting a new Dubai company after a failed bank account dubai rejection makes sense when the original structure, activity scope, shareholder mix, or company name, is itself the compliance risk. A fresh incorporation with a refined activity, updated documents, and a matched bank
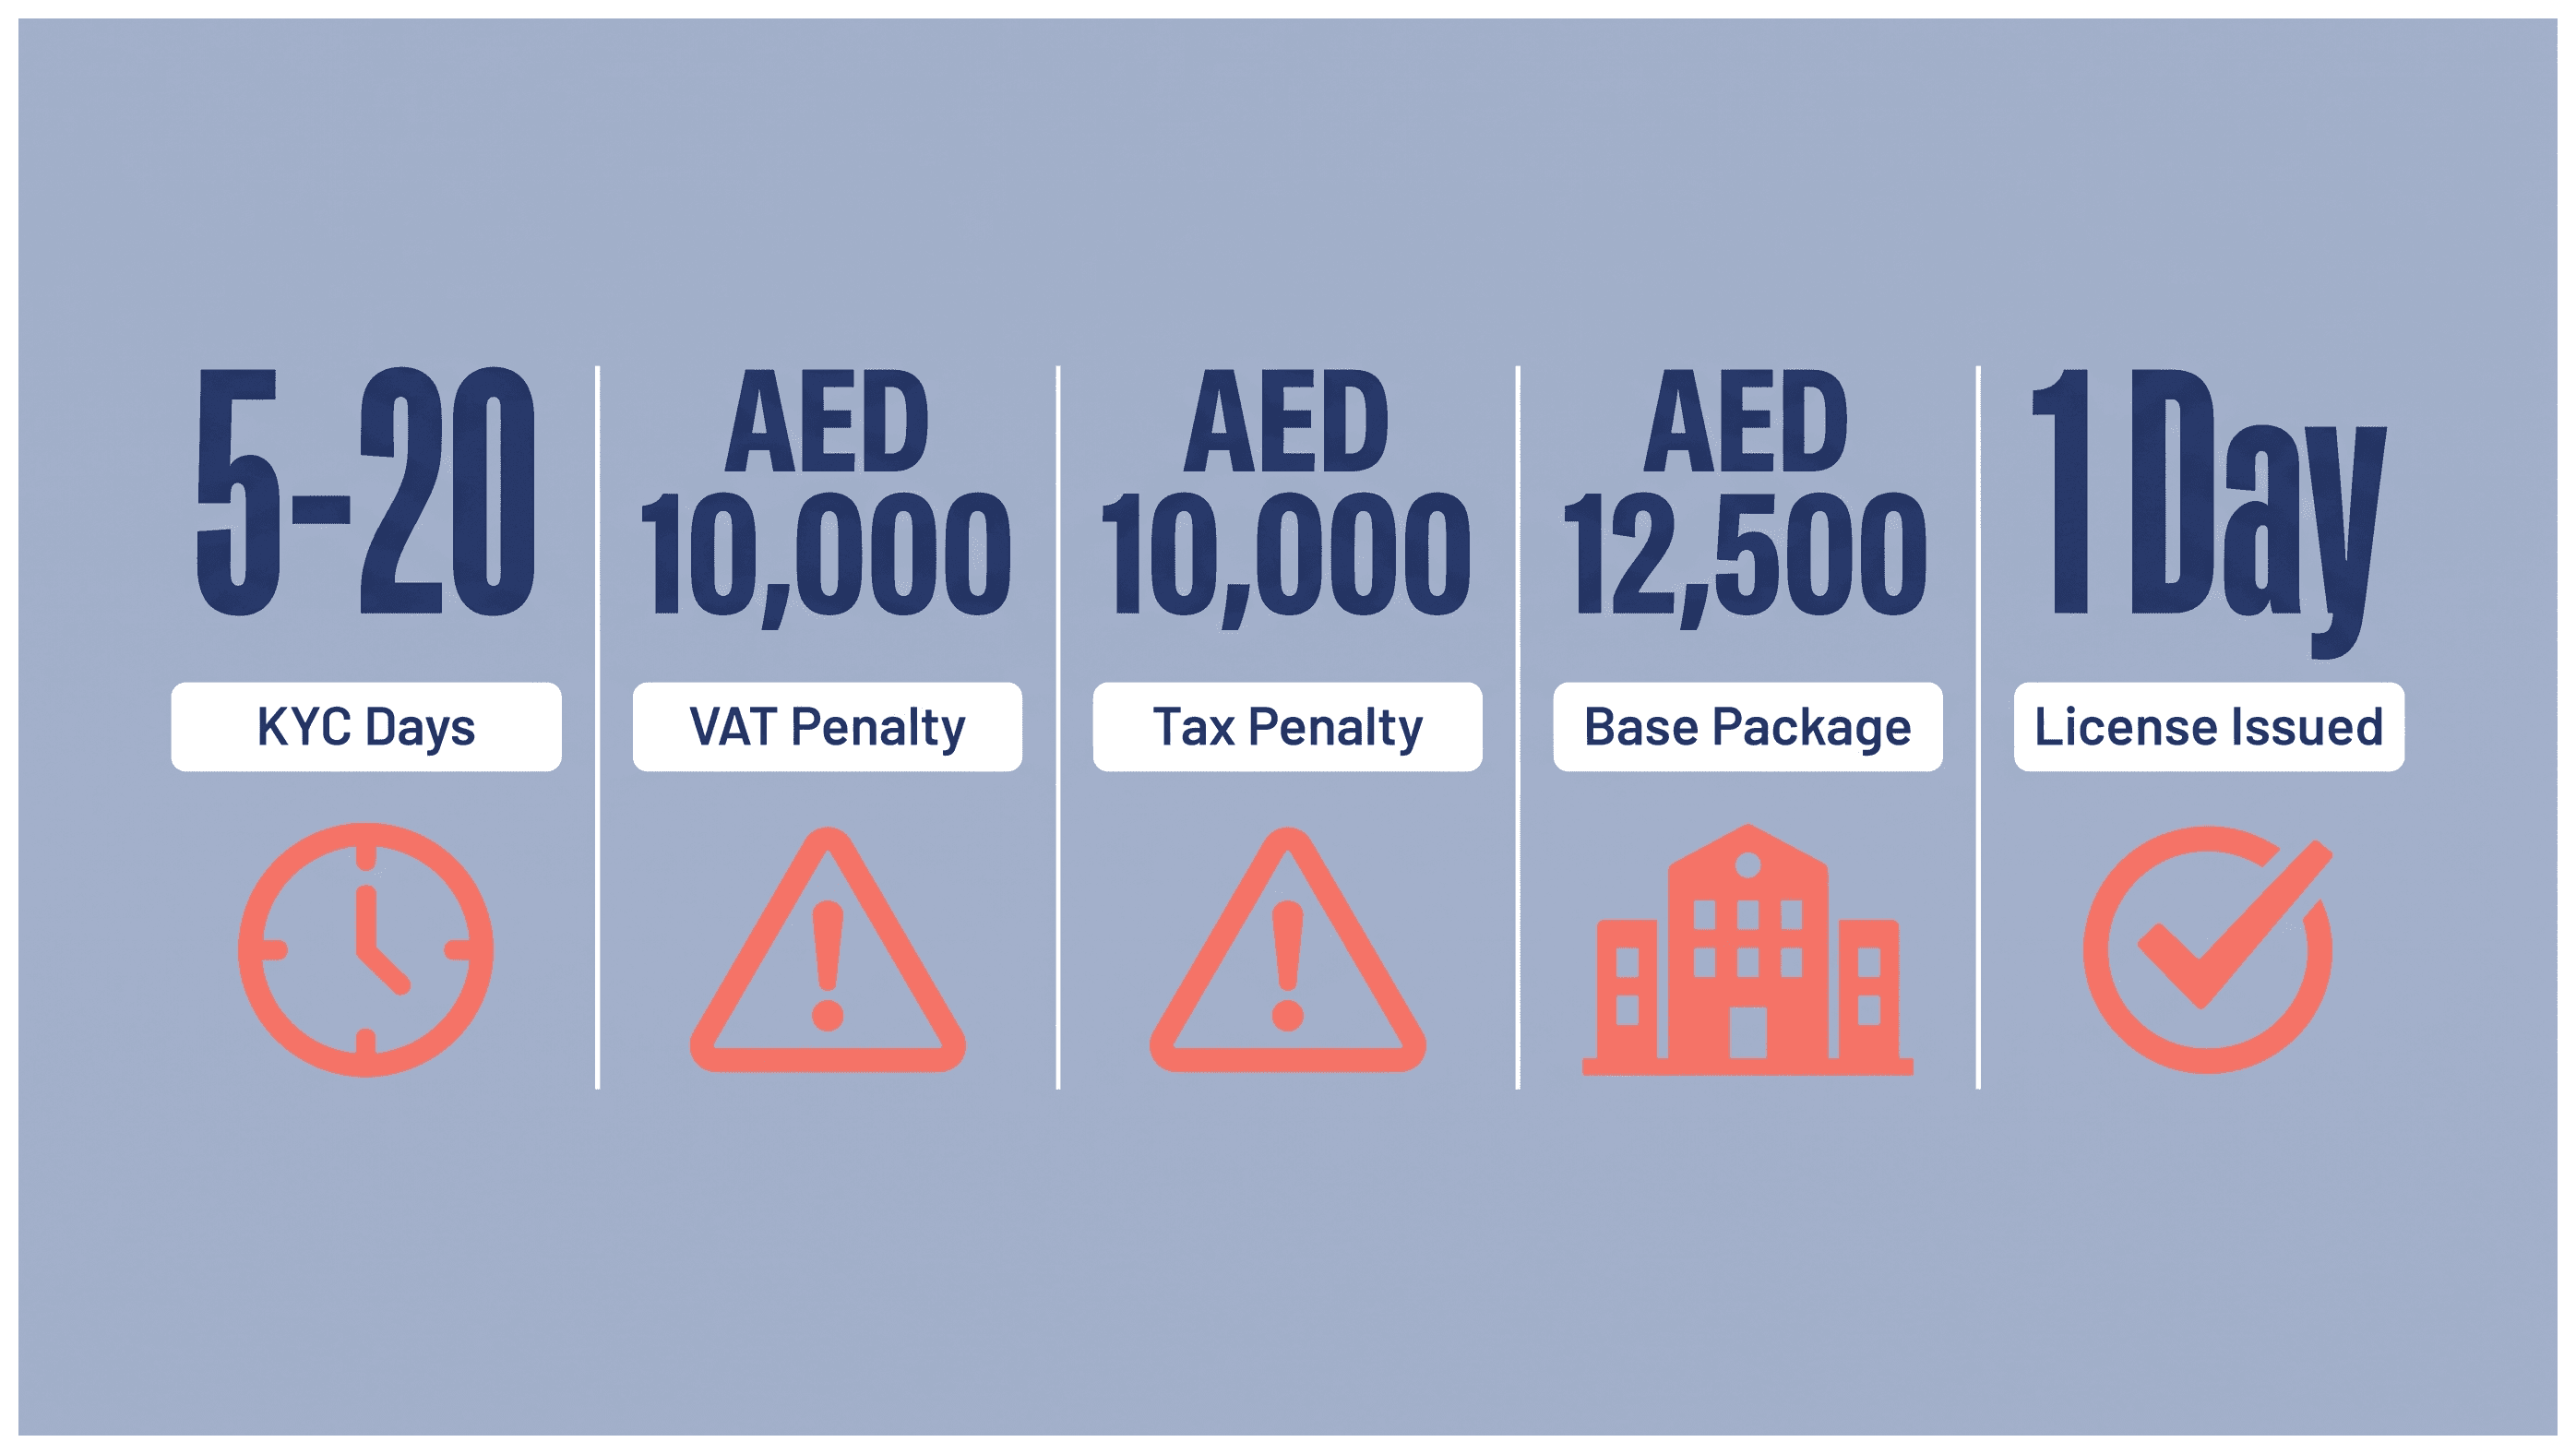
A failed bank account dubai application stops more new companies in their tracks than almost any other post-licensing hurdle. KYC review takes 5 to 20 working days (Central Bank of the UAE, 2026). Banks are required under UAE Federal Decree-Law No. 20 of 2018 to apply enhanced due diligence to higher-risk activities. Late VAT registration carries a flat AED 10,000 penalty (Federal Tax Authority, 2026). Corporate tax late registration triggers a separate AED 10,000 one-time penalty. Base packages at Dubai South Business Hub Free Zone start at AED 12,500, with a license issued in 1 business day on a complete file. This article explains what triggers a failed bank account dubai rejection, what it costs to fix, and the exact steps to reapply with the right bank for your activity type.
What a Failed Bank Account Application Means for Your Dubai Company
A failed bank account dubai application means the bank's compliance team has declined to onboard your company after reviewing its KYC file. The decision is not a ban; it is a rejection by one institution. You can address the documented deficiencies and apply to a different bank without losing your trade license.
How Banks Assess a New Dubai Company
Every new corporate applicant goes through a Know Your Customer (KYC) and Anti-Money Laundering (AML) review. The bank examines your trade license, memorandum and articles of association, shareholder passports, source-of-funds declaration, and business plan. A failed result means one or more elements did not meet the bank's internal risk threshold, it is not a Central Bank of the UAE blacklist entry, and it carries no legal consequence for your license.
Take a general trading company whose business plan listed "import and export of all goods" without specifying product categories or supplier countries. That file received an immediate rejection from two retail banks. After refining the plan to name specific product lines and named counterparty markets, the same company was approved at a third bank. The fix was not the license, it was the document quality.
Why the Trade License Itself Is Not Cancelled
A bank rejection has no legal effect on a free zone trade license. The licensing authority and the bank are entirely separate entities operating under different regulatory frameworks. Your license at Dubai South Business Hub Free Zone remains valid for 12 months from issuance regardless of any banking outcome. You retain the right to open a Dubai bank account online with any UAE-licensed bank at any time after a rejection.
Worth flagging: a failed bank account dubai rejection does not pause your VAT obligations. If your taxable turnover reaches AED 375,000, you must register with the Federal Tax Authority regardless of whether a bank account is open.
Common Reasons Banks Reject a Failed Bank Company Dubai File
The most common reasons for a failed bank company dubai rejection are a vague or high-risk business activity, an incomplete KYC document set, a shareholder nationality flagged as higher-risk by the bank's policy, no physical presence evidence, or missing VAT and tax registration where applicable.
Activity-Related Rejection Triggers
General trading, money services, cryptocurrency, and precious-metals activities attract enhanced due diligence at most retail banks, a vague description makes the file immediately suspect.
A business plan that does not name specific product categories, trading partners, or target markets is routinely declined. Banks need to model the transaction flow before approving an account.
Activities regulated by a secondary authority require proof of that approval before the bank will proceed. Healthcare activities licensed by the Dubai Health Authority (DHA) and financial services activities licensed by the relevant financial regulator are two common examples. Dubai South Business Hub Free Zone licenses the activity; the named regulator approves it separately.
A founder who listed "financial services consultancy" on the license without attaching proof of approval from the relevant financial regulator received a rejection. Once the approval letter was included in the resubmission, the same bank reversed its decision within 8 working days.
You can review the full range of business activities in Dubai available at Dubai South Business Hub Free Zone to confirm how your activity is classified before approaching a bank.
Document and Compliance Gaps That Cause Failure
Missing or expired passport copies, no utility bill or proof of residential address for each shareholder, and unsigned source-of-funds declarations are the most frequent document gaps in a failed bank company dubai file.
Banks require a detailed business plan, not a one-page summary, covering the revenue model, customer profile, and expected monthly transaction volumes.
Late VAT or corporate tax registration raises a compliance flag. Both carry a flat AED 10,000 penalty per entity from the Federal Tax Authority (tax.gov.ae, 2026). The corporate tax penalty is a one-time charge; the VAT penalty applies per registration event.
Requirements to Fix Before Reapplying for a Dubai Bank Account
Before reapplying after a failed bank account dubai rejection, you must update your business plan with specific product lines and counterparty details, complete your KYC document set, obtain any outstanding regulator approvals, and confirm VAT or corporate tax registration status with the Federal Tax Authority.
Document Checklist for a Reapplication
Valid trade license (original or certified copy)
Memorandum and articles of association, included in every Dubai South Business Hub Free Zone package
Share register, included in every package
Passport copies of all shareholders and Ultimate Beneficial Owners (UBOs), notarised where the bank requests it
Proof of residential address for each shareholder: a utility bill or bank statement dated within 3 months
Signed source-of-funds declaration for each shareholder
Detailed business plan of at least 4 pages, covering product specifics, named markets, and projected monthly transaction volumes
Any secondary regulatory approval letters relevant to the licensed activity
Dubai South Business Hub Free Zone Package Comparison
Package | What Is Included | Package Price |
|---|---|---|
0 Visa Package | Trade license, articles of association, share register, flexi-desk space, and lease agreement | AED 12,500 |
1 Visa Package | All above, plus one visa allocation (investor or partner visa) and establishment card | AED 16,350 |
2 Visa Package | All above, plus up to two visa allocations and establishment card (maximum two allocations available) | AED 18,200 |
Visa Processing | Entry permit, status change, medical, Emirates ID, and visa stamping, not included in any package price | Quoted separately |
License Issuance Timeline | Complete file required; timeline applies to all three packages | 1 business day |
Structural Changes That Improve Approval Odds
Narrowing a broad general trading activity to a defined product category reduces the bank's perceived risk profile significantly. A founder operating an ICT consultancy narrowed the activity from "information technology services" to "software implementation and training for logistics companies" and was approved by the first bank approached on reapplication. The change cost nothing beyond the license amendment fee, the underlying business was identical.
Adding a UAE-resident director or authorised signatory gives the bank a locally reachable contact and often lowers the risk rating. Ensuring the company's flexi-desk lease agreement is current and matches the address on the license removes another common objection. Both the flexi-desk space and the lease agreement are included in all packages when you set up a company at Dubai South Business Hub Free Zone, so there's no additional cost to produce this document.
Failed Bank Dubai Cost: What Fixing the Problem Will Set You Back
The failed bank dubai cost of rectifying a rejection depends on whether you need to amend your license activity, obtain a secondary regulatory approval, or restructure the company. License amendment fees and regulatory approval costs vary by activity; base packages at Dubai South Business Hub Free Zone start at AED 12,500.
Dubai South Business Hub Free Zone Package Pricing
0 Visa Package: AED 12,500, includes the license, articles of association, share register, flexi-desk space, and lease agreement. No visa allocation.
1 Visa Package: AED 16,350, adds one visa allocation (investor or partner visa) and the establishment card.
2 Visa Package: AED 18,200, adds up to two visa allocations and the establishment card. Two is the maximum available.
Visa processing (entry permit, status change, medical, Emirates ID, stamping) is quoted separately and is not included in any package price.
A solo founder who needed to amend their activity and reapply chose the 0 Visa Package at AED 12,500, then added visa processing separately once the bank account was open. That sequencing kept the upfront outlay predictable. You can model your own total using the cost of setting up a company in Dubai calculator.
Additional Costs to Factor In
License activity amendment fee: UNVERIFIED: <DSBH amendment fee>. Confirm before publishing.
Secondary regulatory approval costs vary widely by regulator and activity, budget separately and confirm directly with the relevant authority before committing.
Professional business-plan drafting services: UNVERIFIED: <market rate range in AED>. Confirm before publishing.
VAT late registration penalty: AED 10,000 flat (Federal Tax Authority, 2026).
Corporate tax late registration penalty: AED 10,000 flat, one time per entity.
Step-by-Step Guide to Reapplying After a Failed Bank Account Dubai Rejection
To reapply after a failed bank account dubai rejection: review the rejection letter, fix the identified document or activity gap, update your business plan, select a bank matched to your activity type, submit a complete KYC file, and attend the in-person interview. Never apply to multiple banks simultaneously.
Step 1: Diagnose the Rejection Before Acting
Request written confirmation of the rejection reason from the bank's relationship manager. Verbal feedback is not sufficient, you need a documented summary to act on.
Map each stated reason to the checklist in the Requirements section above. Identify whether the gap is a missing document, an activity description problem, or a structural issue with the company itself.
Determine the correct fix before spending anything: a document update costs almost nothing; an activity amendment costs more; a fresh incorporation costs the package price.
Banks are not legally required to disclose detailed rejection reasons, but most will provide a summary on request. If the relationship manager declines, escalate to the SME banking team in writing.
Step 2: Select the Right Bank for Your Activity
Retail banks with dedicated SME units are generally more receptive to newly licensed free zone companies in service and ICT activities. ICT and professional services are typically rated standard risk.
Trading companies, particularly those with a trading license in Dubai covering import/export, often find a smoother path with banks that have established trade-finance desks.
Healthcare and education companies should approach banks whose compliance teams are familiar with DHA or KHDA-regulated entities. The compliance officer will already understand the secondary approval process.
Never apply to multiple banks at the same time. A cluster of simultaneous applications can itself raise a red flag in the bank's risk system and make subsequent applications harder.
Step 3: Assemble and Submit the Complete KYC File
Use the document checklist in the Requirements section as your submission checklist, tick each item before sending anything.
Prepare a business plan of at least 4 pages covering product specifics, named markets, and projected monthly transaction volumes.
Attach any secondary regulatory approval letters before submission. Do not wait for the bank to ask for them.
Book the in-person appointment. Most UAE banks require at least one shareholder or authorised signatory to attend in person.
Follow up in writing after the interview and keep a record of every communication. KYC review typically takes 5 to 20 working days.
Is there any guarantee of approval after fixing the rejection reasons?
No guarantee of approval can be given regardless of document completeness. Banks retain the right to decline any application under their internal risk policies. Fixing the documented deficiencies materially improves the probability of approval, but the outcome is always the bank's decision.
Which Banks in the UAE Suit Which Business Activity
UAE banks segment their SME onboarding by activity risk. Service, ICT, and consultancy companies generally find retail SME banks accessible. Trading companies benefit from banks with trade-finance desks. Regulated activities such as healthcare or financial services need a bank whose compliance team recognises the relevant secondary regulator's approval, and a failed bank account dubai application is often caused by approaching the wrong bank type for the activity in question.
Lower-Risk Activities and Suitable Bank Profiles
ICT, professional services, education, and management consultancy are typically rated standard risk. Most UAE retail SME banks will consider these activities with a clean KYC file, a clear business plan, and a UAE-resident signatory. An ICT license in Dubai paired with a named client list and specific project descriptions gives a compliance officer a clear picture of the business model.
A software consultancy with a two-page client list and named project descriptions was approved by a major UAE retail bank within 12 working days of submission. The file was complete on first submission, no back-and-forth requests for additional documents. That outcome is achievable when the activity is low-risk and the documentation is thorough. For the current list of licensed banks in the UAE, check (Central Bank of the UAE, 2026).
Higher-Risk Activities and What Extra Evidence Banks Expect
General trading, commodity trading, precious metals, and money-related activities require enhanced due diligence under UAE Federal Decree-Law No. 20 of 2018.
Expect requests for supplier contracts or letters of intent, named customer lists, and import/export documentation from prior business history.
Financial services activities require the relevant regulatory approval letter. Dubai South Business Hub Free Zone licenses the activity; the named financial regulator approves it separately. Submit both documents together.
Healthcare companies must present DHA approval before most banks will proceed. Approaching a bank before that approval is in hand almost guarantees a failed bank account dubai outcome.
Setting Up a New Dubai Company After a Failed Bank Account: When It Makes Sense to Start Fresh
Starting a new Dubai company after a failed bank account dubai rejection makes sense when the original structure, activity scope, shareholder mix, or company name, is itself the compliance risk. A fresh incorporation with a refined activity, updated documents, and a matched bank strategy avoids carrying the history of a rejected file.
When to Amend Versus When to Reincorporate
Amend the existing license if the rejection was caused by a document gap or a business-plan deficiency. That's faster and cheaper than starting again. Consider a fresh incorporation if the company name, activity wording, or shareholder structure is itself the source of the bank's concern.
A company originally named after a sanctioned jurisdiction's geography was declined by three banks on name alone. A fresh incorporation under a neutral trading name resolved the issue without changing any other aspect of the business. The new license was issued in 1 business day on a complete file. Budget the relevant package: AED 12,500 for the 0 Visa option, AED 16,350 for 1 Visa
References
Frequently Asked Questions