Topic Summary
What Is Non-Qualifying Income Types Under UAE Corporate Tax and Why It Matters
Non-qualifying income types under UAE corporate tax are revenue streams a free zone company earns outside the categories listed in Cabinet Decision No. 100 of 2023. This income doesn't get the 0% rate. It's taxed at 9% above AED 375,000 and can put the company's Qualifying Free Zone Person (QFZP) status at risk.
Main Non-Qualifying Income Types Free Zone Companies Encounter
Main Non-Qualifying Income Types Free Zone Companies Encounter
The De Minimis Limit: How Much Non-Qualifying Income Is Tolerated
The de minimis rule lets a QFZP earn limited non-qualifying income types under UAE corporate tax without losing its 0% rate. Non-qualifying revenue must stay at or below 5% of total revenue or AED 5 million, whichever is lower.
Numbered Checklist to Identify Non-Qualifying Income in Your Books
To spot non-qualifying income types under UAE corporate tax, list every revenue stream, tag customers, match activities to the Cabinet Decision, then run the de minimis test. Repeat quarterly.
Consequences of Non-Qualifying Income for Your 0% Rate
Non-qualifying income types under UAE corporate tax are taxed at 9% above AED 375,000. A breach or another failed QFZP condition costs you the 0% rate for five periods.
Practical Ways to Keep Non-Qualifying Income Under Control
Keep non-qualifying income types under UAE corporate tax in check by screening customers early, billing work separately, and tracking the ratio monthly.
Where to Verify Non-Qualifying Income Rules With Official Sources
Verify non-qualifying income types under UAE corporate tax on the Federal Tax Authority portal and the Ministry of Finance website before each filing, since guidance changes.
More than 350,000 businesses are registered with the Federal Tax Authority (Federal Tax Authority, 2026). Any free zone company among them that earns income outside the qualifying categories pays 9% above AED 375,000, not 0%. This guide explains non-qualifying income types under UAE corporate tax for Dubai South Business Hub owners and finance managers. After reading, you'll be able to spot these revenue streams and test your de minimis position.
What Is Non-Qualifying Income Types Under UAE Corporate Tax and Why It Matters
Non-qualifying income types under UAE corporate tax are revenue streams a free zone company earns outside the categories listed in Cabinet Decision No. 100 of 2023. This income doesn't get the 0% rate. It's taxed at 9% above AED 375,000 and can put the company's Qualifying Free Zone Person (QFZP) status at risk.
How the Law Separates Qualifying From Non-Qualifying Revenue
Federal Decree-Law No. 47 of 2022 sets the 9% base rate. The 0% rate applies only to qualifying income of a Qualifying Free Zone Person. Anything not listed as qualifying is non-qualifying by default, and each revenue stream is tested separately.
Picture a Dubai South trading company. Sales to another free zone company can qualify. Sales to a mainland retailer usually don't.
Qualifying vs Non-Qualifying Income Types for Free Zone Companies
Feature | Typically Qualifying | Typically Non-Qualifying |
|---|---|---|
Customer type | Other free zone persons, and overseas customers for qualifying activities | Mainland customers and individuals, outside qualifying activities |
Activity type | Activities listed in Cabinet Decision No. 100 of 2023 | Banking, insurance, finance and leasing |
Property income | Commercial free zone property let to other free zone persons | Non-commercial immovable property |
Intellectual property income | Qualifying IP income up to the nexus-based amount | Royalties from non-qualifying IP |
Tax treatment | 0% for a QFZP | 9% above AED 375,000 |
Why Free Zone Owners Often Misjudge This Line
A free zone license alone doesn't make income qualifying. A consultancy that invoices a mainland client and assumes its free zone address covers the fee is a classic case. The regime is never 100% tax free.
Main Non-Qualifying Income Types Free Zone Companies Encounter
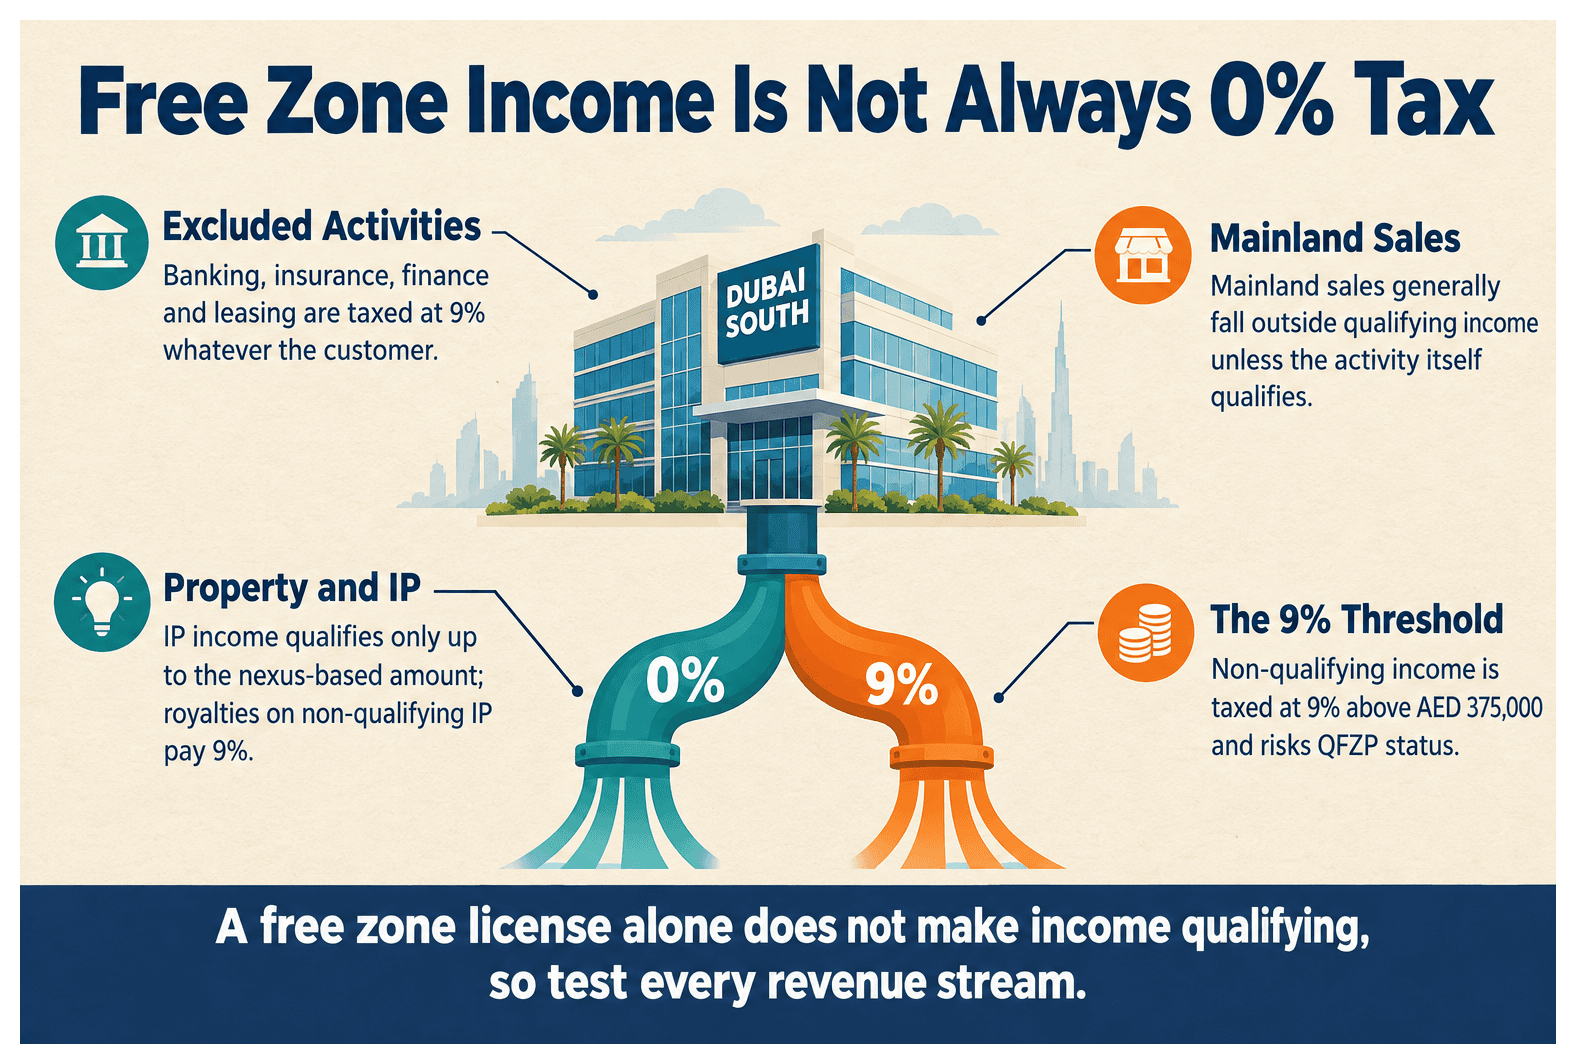
The main non-qualifying income types under UAE corporate tax include excluded activities, most mainland sales, dealings with individuals, non-qualifying property income and non-qualifying IP income. Banking, insurance, and finance and leasing are excluded activities, so their income is taxed at 9% whatever the customer.
Income From Excluded Activities
Equipment hire to another free zone entity is leasing, so it stays non-qualifying.
Check every licensed activity against the Cabinet Decision list.
See our guide to qualifying activities for UAE free zone corporate tax.
Mainland and Individual Customer Revenue
Mainland sales generally fall outside qualifying income unless the activity itself qualifies. Dealings with individuals follow the same logic. A Dubai South logistics firm storing goods for a mainland importer needs an activity-by-activity review. Our guide on corporate tax for free zone companies with mainland clients covers this.
Property and Intellectual Property Income
Non-commercial property income is non-qualifying.
IP income qualifies only up to the nexus-based amount.
Royalties on non-qualifying IP are taxed at 9%.
The De Minimis Limit: How Much Non-Qualifying Income Is Tolerated
The de minimis rule lets a QFZP earn limited non-qualifying income types under UAE corporate tax without losing its 0% rate. Non-qualifying revenue must stay at or below 5% of total revenue or AED 5 million, whichever is lower.
Calculating the 5% and AED 5 Million Tests
Revenue, not profit, is the measure. Say total revenue is AED 20 million. Five percent is AED 1 million, so your limit is AED 1 million, not AED 5 million.
Consequences of Crossing the Threshold
QFZP status is lost for that period and the next four.
All taxable income then falls under the standard regime.
One large quarter-end contract can trigger it.
Read how qualifying income works for a Dubai trading company.
Numbered Checklist to Identify Non-Qualifying Income in Your Books
To spot non-qualifying income types under UAE corporate tax, list every revenue stream, tag customers, match activities to the Cabinet Decision, then run the de minimis test. Repeat quarterly.
Step 1: Map Every Revenue Stream by Customer and Activity
Export a full financial year of invoices.
Tag customers as free zone, mainland, individual or overseas.
Step 2: Test Each Stream Against the Qualifying Rules
Compare each activity with the qualifying and excluded lists.
Flag property and IP income, and record your reasoning.
Step 3: Run the De Minimis Calculation and Record the Result
Total the non-qualifying revenue and apply the lower limit.
File the working papers before the return is due, within nine months of year-end. Corporate tax filing services in Dubai can help.
Consequences of Non-Qualifying Income for Your 0% Rate
Non-qualifying income types under UAE corporate tax are taxed at 9% above AED 375,000. A breach or another failed QFZP condition costs you the 0% rate for five periods.
Tax Cost Under the Standard Regime
A company with AED 2 million of non-qualifying profit pays 9% on the amount above AED 375,000, so AED 146,250. Qualifying and non-qualifying income must be accounted for separately.
Compliance Exposure Beyond Tax
Incorrect returns can trigger FTA penalties.
Audited financial statements must support your split.
Keep contracts proving customer status.
Practical Ways to Keep Non-Qualifying Income Under Control
Keep non-qualifying income types under UAE corporate tax in check by screening customers early, billing work separately, and tracking the ratio monthly.
Screen Customers and Contracts Early
Add a customer status field at onboarding.
Add clauses confirming free zone person status.
Track the Ratio Monthly and Plan Structure
If you sit at 4% in month nine, pause the mainland contract or move it into a separate entity. Dubai South Business Hub supports company formation, trade licenses and residency visa packages tied to your license, so your activities can match your real business.
Where to Verify Non-Qualifying Income Rules With Official Sources
Verify non-qualifying income types under UAE corporate tax on the Federal Tax Authority portal and the Ministry of Finance website before each filing, since guidance changes.
Federal Decree-Law No. 47 of 2022.
Cabinet Decision No. 100 of 2023 and Ministerial Decisions.
FTA guides and public clarifications.
Book a professional review if your mix is mixed, near 5%, or includes property or IP. Our UAE corporate tax guide is a good start.
Keeping Your 0% Rate Intact
Knowing your non-qualifying income types under UAE corporate tax lets you protect the 0% rate, stay under the de minimis limit, and avoid five periods at 9% above AED 375,000. Review your revenue split now, then speak with the Dubai South Business Hub team about license activities and structure that fit your income mix.
References
Frequently Asked Questions