Topic Summary
What Is Ugandan Nationals Banking UAE and How Does Business Banking Work
Ugandan nationals banking UAE means opening and operating a UAE bank account, usually a corporate account tied to a free zone company. Banks supervised by the Central Bank of the UAE verify the owner, the company and the source of funds before approving a Ugandan-owned business.
Which Documents and Conditions Does a Dubai Company Need From a Ugandan National
Which Documents and Conditions Does a Dubai Company Need From a Ugandan National
How East African Community Re-Export Routes Shape Your UAE Banking Profile
East African Community re-export routes link Uganda, Kenya and Tanzania through Dubai as a trading hub. Banks want to see your corridors, counterparties and payment flows, so a documented model makes approval easier.
Step-by-Step Process to Open a Corporate Account as a Ugandan National
Form a free zone company, prepare your KYC pack, choose a bank, submit, complete the compliance interview, fund the account and activate online banking. Most applications take 2 to 6 weeks.
How Much Does It Cost and How Long Does It Take to Bank in the UAE as a Ugandan Owner
Costs for Ugandan nationals banking UAE include opening fees, minimum balances, monthly maintenance and transfer fees, all in AED. Timelines run 2 to 6 weeks. Confirm current figures with each bank.
Regulations in the UAE on Tax, Compliance and Banking for Ugandan Owners
UAE banks follow Central Bank AML rules, and companies must meet Federal Tax Authority requirements, including corporate tax registration and VAT where thresholds apply. Keep records, reconcile regularly and answer bank requests promptly.
Common Mistakes Ugandan Owners Make When Banking in the UAE
Common Mistakes include applying without a clear plan, choosing a mismatched license activity, hiding source of funds, relying on one bank and ignoring compliance. Each causes delays or declines.
Ugandan nationals banking UAE starts with forming a free zone company and opening a corporate account with a licensed bank. Most applications take 2 to 6 weeks.
The UAE has more than 40 licensed commercial banks [1], and over 70% of new Dubai South Business Hub Free Zone applications come from founders who never visit during formation. Yet roughly 40% of first-time founders still face a delay or decline at the bank stage. This guide shows you how to avoid that.
What Is Ugandan Nationals Banking UAE and How Does Business Banking Work
Ugandan nationals banking UAE means opening and operating a UAE bank account, usually a corporate account tied to a free zone company. Banks supervised by the Central Bank of the UAE verify the owner, the company and the source of funds before approving a Ugandan-owned business.
Corporate Accounts Versus Personal Accounts
A corporate account sits under the trade license. It receives buyer payments and pays suppliers. A personal account usually needs a residence visa and Emirates ID. Picture a Kampala coffee exporter who forms a Dubai South company and opens an AED account to collect buyer payments. Keep personal money out of it.
How the Central Bank Shapes Account Approval
The Central Bank of the UAE sets anti-money-laundering (AML) and know-your-customer (KYC) expectations. Banks run risk-based reviews, so a clear model speeds things up. One bank asked a new Ugandan-owned trading company for a signed supplier contract before approving anything. Expect similar requests for any Dubai company with a Ugandan national as owner.
Why Ugandan Owners Choose a Dubai Free Zone Company
Full foreign ownership, with a trade license banks recognise.
Remote formation, so you can run a UAE business from Uganda.
Residency visa packages tied to the license.
A logistics-friendly location near Al Maktoum International Airport.
Which Documents and Conditions Does a Dubai Company Need From a Ugandan National
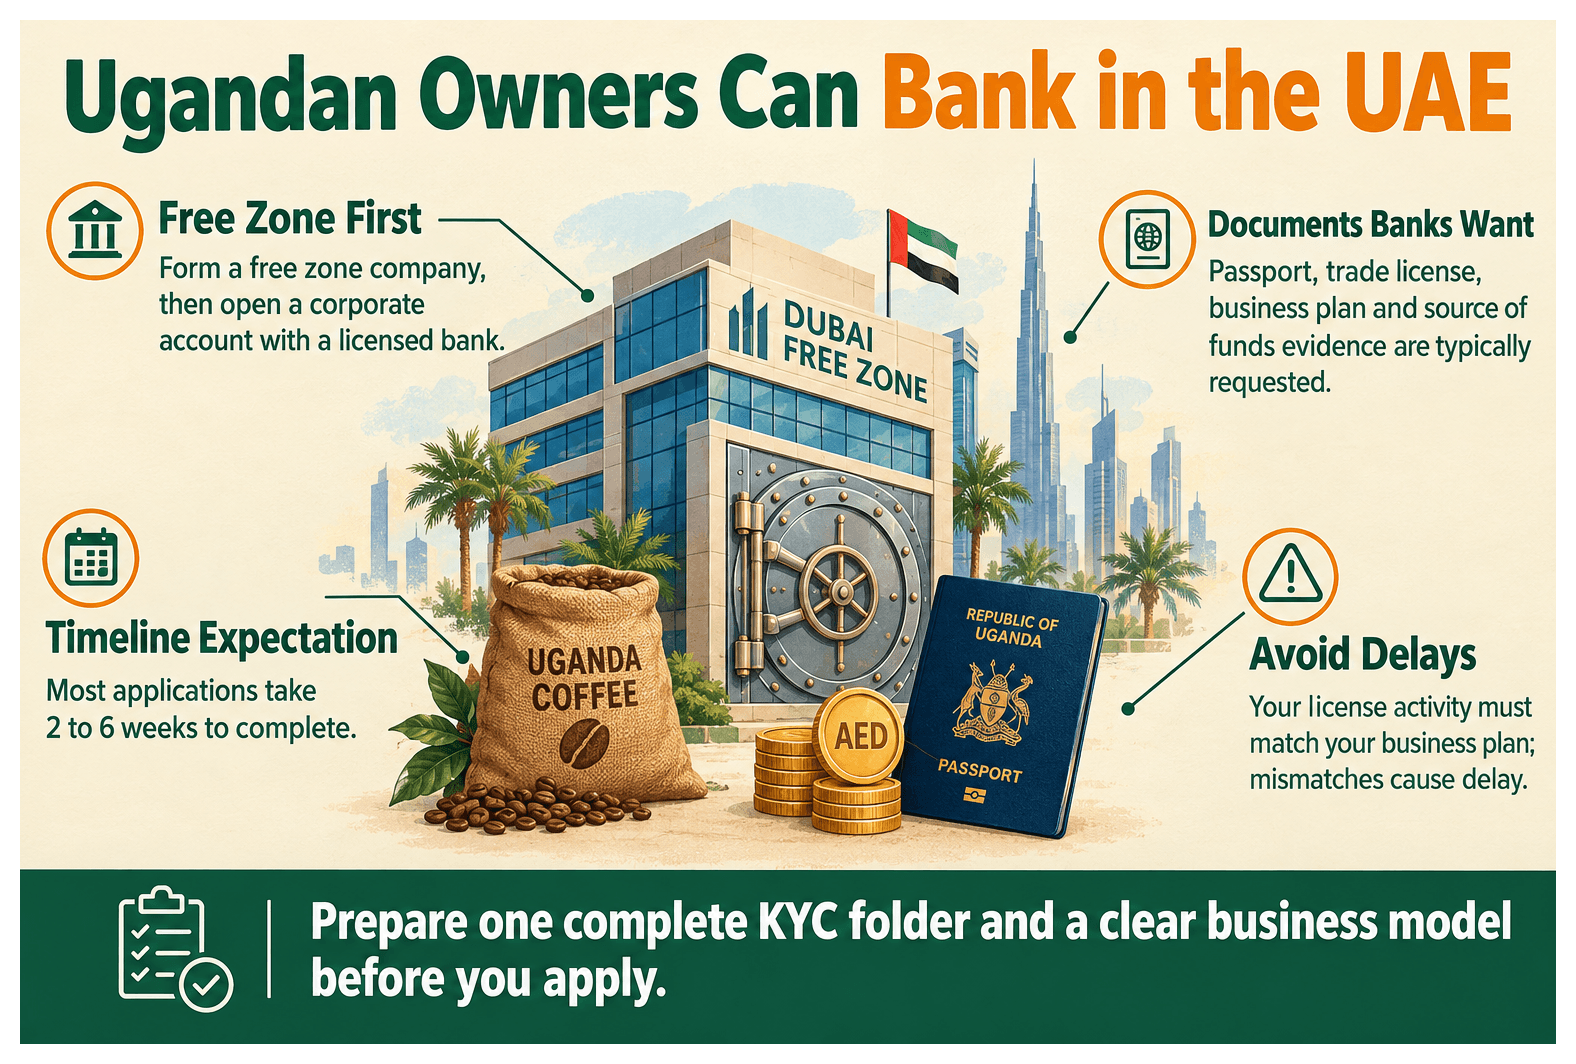
Banks typically ask a Ugandan owner for a valid passport, proof of address, the trade license, incorporation documents, a business plan and source of funds evidence. Some also want supplier or buyer contracts and a residence visa for signatories.
Personal and Company Documents Checklist
Passport, Ugandan proof of address and references.
Trade license, memorandum of association and share certificate.
Lease or flexi-desk agreement.
Attested or notarised Ugandan documents where requested.
Build one digital KYC folder before you apply.
Source of Funds and Business Plan Evidence
A Ugandan agri-trader might show 12 months of Kampala statements and two buyer contracts. Add a one-page plan covering products, buyers, countries and monthly volumes. Your license activity must match that plan. A mismatch is a common cause of delay.
Residency Visa and Emirates ID Considerations
Some banks accept non-resident owners for corporate accounts. You can add a personal account once the visa lands. See the UAE investor visa for Ugandan nationals guide for steps.
How East African Community Re-Export Routes Shape Your UAE Banking Profile
East African Community re-export routes link Uganda, Kenya and Tanzania through Dubai as a trading hub. Banks want to see your corridors, counterparties and payment flows, so a documented model makes approval easier.
Mapping the Trade Corridors Banks Expect to See
Dubai handles more than AED 200 billion in trade each year [2]. A typical flow: goods bought in Asia, held in Dubai South, then shipped to Mombasa and Entebbe, with USD payments settled through your Dubai account. Name your ports, forwarders and currencies (AED, USD, UGX).
Documenting Counterparties and Payment Flows
Keep invoices, bills of lading and customs declarations ready.
Avoid third-party payments you can't explain.
Use identical supplier names across contracts.
Share a counterparty list with country and goods type.
Banks apply enhanced due diligence to higher-risk corridors, so this matters.
Linking Banking to Your Trading Company Setup
Align license activity, lease and bank profile before submitting. Our guides on setting up a company in Dubai South and what Ugandan founders need to know cover the groundwork.
Step-by-Step Process to Open a Corporate Account as a Ugandan National
Form a free zone company, prepare your KYC pack, choose a bank, submit, complete the compliance interview, fund the account and activate online banking. Most applications take 2 to 6 weeks.
Step 1: Reserve Your Company Name and Form the Company
Run the company name check first. Pick a license activity that matches your trade model. One founder checked three names and held the license in under a week.
Step 2: Prepare the KYC Pack and Choose a Bank
Match the bank to your volumes and currencies. A founder might shortlist one bank for USD trade payments and another for low-fee local transactions. Fees change, so note the date you checked.
Step 3: Submit, Interview and Activate the Account
Apply online or via a relationship manager. Expect questions on counterparties and funds. One bank asked for a supplier invoice and buyer contract; the founder sent both the same day. Then deposit, set signatory rules and activate online banking. For a wider view, read how to open a business bank account in Dubai.
How Much Does It Cost and How Long Does It Take to Bank in the UAE as a Ugandan Owner
Costs for Ugandan nationals banking UAE include opening fees, minimum balances, monthly maintenance and transfer fees, all in AED. Timelines run 2 to 6 weeks. Confirm current figures with each bank.
Indicative UAE Corporate Bank Account Costs and Timelines in AED (with Date Checked)
Feature | Fee or Stage | Indicative AED Range and Date Checked |
|---|---|---|
Account opening fee | One-off setup charge | AED 0 to 1,000 (checked May 2026) |
Minimum balance requirement | Average monthly balance | AED 10,000 to 100,000 (checked May 2026) |
Monthly maintenance fee | Recurring account charge | AED 0 to 250 (checked May 2026) |
International transfer fee | Per outgoing transfer | AED 50 to 150 (checked May 2026) |
Typical approval timeline | Application to activation | 2 to 6 weeks (checked May 2026) |
These ranges are indicative only. Banks set their own figures.
Timeline From Application to Active Account
One owner with a full KYC pack got approval in 2 weeks. Another waited 6 weeks after the bank asked for extra contracts. Incomplete source of funds evidence causes most delays.
Estimating Your Full Setup Budget
Combine license, visa and bank costs, plus a contingency for re-submission. The cost calculator gives a personalised AED total.
Regulations in the UAE on Tax, Compliance and Banking for Ugandan Owners
UAE banks follow Central Bank AML rules, and companies must meet Federal Tax Authority requirements, including corporate tax registration and VAT where thresholds apply. Keep records, reconcile regularly and answer bank requests promptly.
AML, KYC and Ongoing Bank Reviews
Banks review accounts periodically.
Dormant or inconsistent accounts can be flagged.
Write clear transaction narratives.
One founder answered a bank's invoice request after a large USD inflow within a day, because records were ready.
A UAE Corporate Tax and VAT Basics for Ugandan-Owned Companies
Corporate tax applies from 2023 under Federal Decree-Law No. 47 of 2022, at 9% above AED 375,000 of taxable income. Qualifying free zone income can attract 0%, but only if conditions are met. It isn't automatic, and your company isn't simply tax free. VAT registration becomes mandatory above AED 375,000 in taxable supplies.
Uganda-Side Reporting and Cross-Border Transfers
Ugandan residents may carry their own reporting and tax duties, so take local advice. Keep a transfer log so both banks can trace funds between Kampala and Dubai.
Common Mistakes Ugandan Owners Make When Banking in the UAE
Common Mistakes include applying without a clear plan, choosing a mismatched license activity, hiding source of funds, relying on one bank and ignoring compliance. Each causes delays or declines.
Application Mistakes That Trigger Declines
Vague descriptions and missing contracts.
Listing "general trading" with one product line.
Applying to several banks with different stories.
Operating Mistakes After the Account Opens
Mixing personal and business funds.
Missing the minimum balance. One founder paid penalties for three months unnoticed.
Ignoring document update requests.
How to Avoid Them With Expert Support
Pair formation with a guided application and keep a back-up bank. Our guide to opening a UAE corporate bank account as an Ugandan entrepreneur goes deeper.
Next Steps: What Should You Do Next to Start Banking in the UAE as a Ugandan Owner
To start Ugandan nationals banking UAE, check your name, form your Dubai South company, prepare your KYC pack, estimate costs and apply to a bank that fits your corridors.
Your 30-Day Action Plan
Week 1: name check and license selection.
Week 2: formation and KYC pack.
Weeks 3 and 4: bank application and interview.
Where to Get Guided Support
Run the name check, get your AED estimate, then book a consultation for formation and a residency visa package tied to your license. Start today.
References
Frequently Asked Questions


