Topic Summary
What Is a UAE Company Overdraft Facility and Why It Matters
A UAE company overdraft facility is a revolving credit line attached to a corporate current account that lets the business spend beyond its balance up to an approved limit. Interest is charged only on the amount used, which makes it a flexible working capital facility in the UAE for covering short-term cash gaps. It's the first product most companies ask for after reading about getting your first credit facility as a Dubai company .
Which Requirements Must a Free Zone Company Meet to Qualify
Which Requirements Must a Free Zone Company Meet to Qualify
Which Regulations in the UAE Govern a UAE Company Overdraft Facility
The Central Bank of the UAE regulates bank lending, including credit risk, exposure rules, and cheque and insolvency frameworks. Banks also apply AML (anti-money laundering) and KYC (know your customer) checks, and corporate tax and VAT records feed into credit assessment. Each bank then sets its own pricing and security policy for a UAE company overdraft facility.
Step-by-Step Guide to Get a UAE Company Overdraft Facility
To get a UAE company overdraft facility: open a corporate account, build six months of activity, prepare documents, choose banks, submit a request, negotiate pricing and security, sign the facility letter, and activate the limit. Following these ordered steps typically moves you from application to drawdown within two to six weeks.
How Much Does It Cost and How Long Does It Take to Get a Business Overdraft in Dubai
Costs include interest of roughly EIBOR plus 3-8% annually, an arrangement fee often 0.5-1% of the limit, and annual renewal fees. Approval typically takes two to six weeks once documents are complete. Fees vary by bank, so confirm current AED figures and the quote date in writing before you accept a business overdraft in Dubai.
Which Mistakes Should You Avoid When Applying for a Working Capital Facility in the UAE
Common mistakes include applying before building account history, requesting an oversized limit, submitting incomplete financials, ignoring personal credit issues, and relying on one bank. Each triggers declines or weak pricing. Preparing a clean forecast and approaching two or three banks improves your odds on any working capital facility in the UAE.
What Should You Do Next to Secure a UAE Company Overdraft Facility
Start by confirming your license and corporate account are active, run your numbers through the cost calculator, gather twelve months of records, and approach two or three banks. A properly structured request improves approval odds and your negotiating power on pricing.
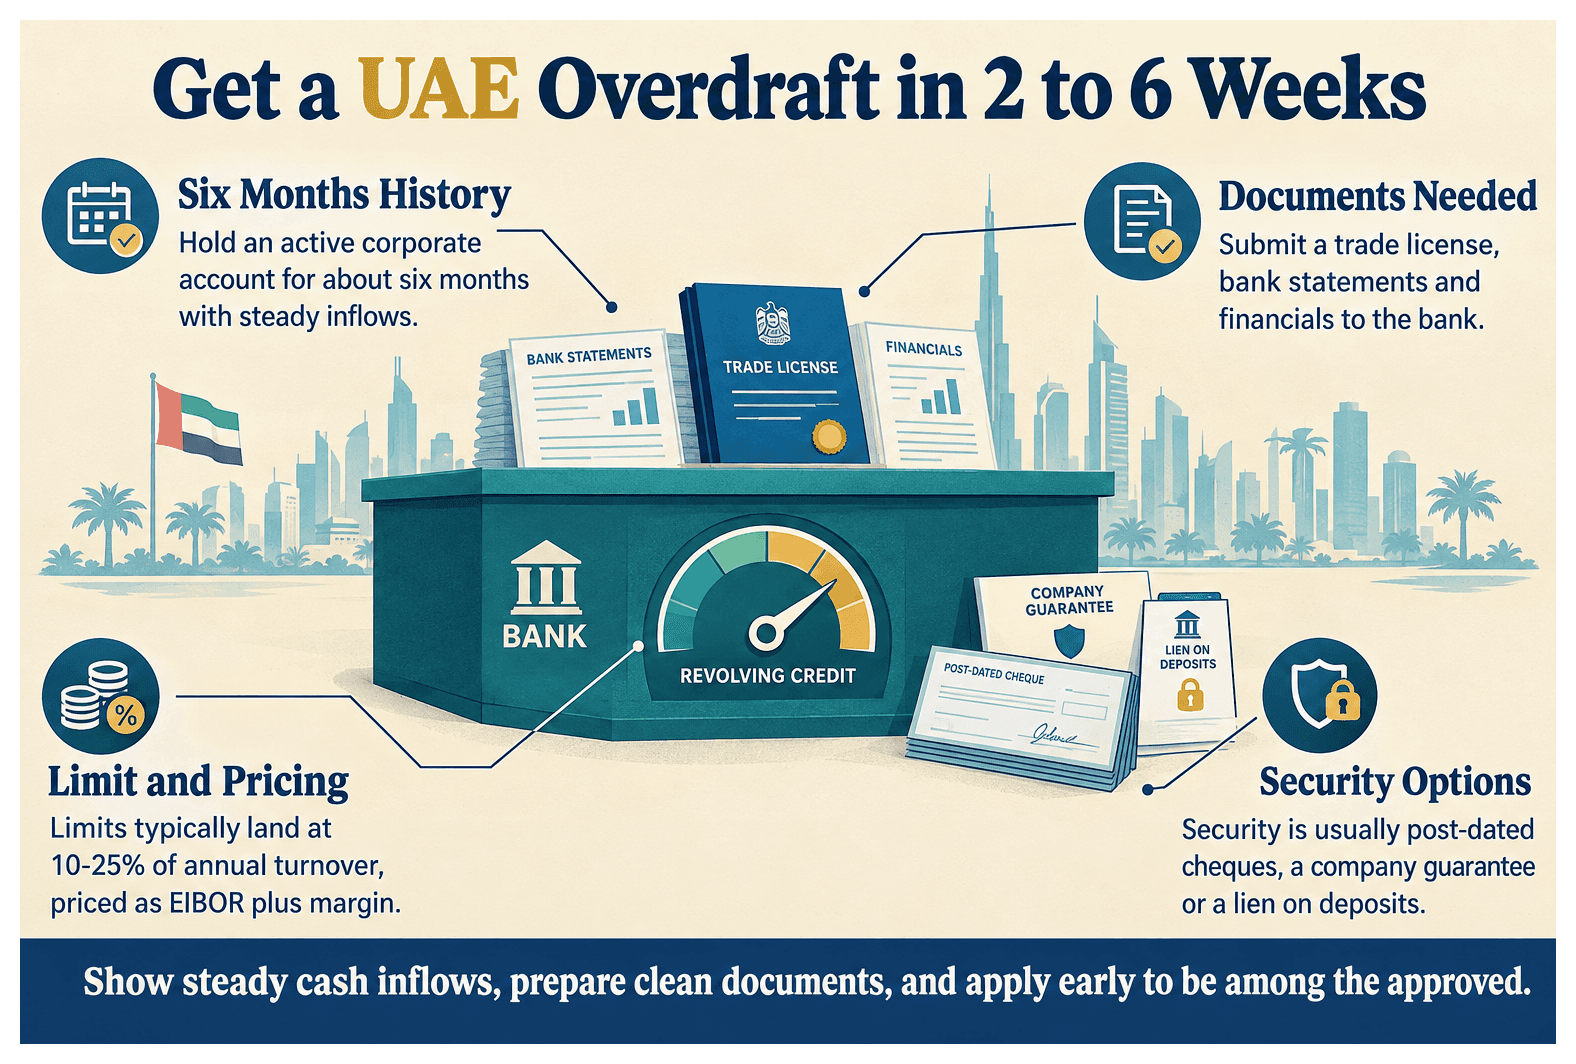
You get a UAE company overdraft facility by holding an active corporate account for about six months, showing steady inflows, and submitting a trade license, bank statements and financials to the bank. Approval usually takes 2 to 6 weeks and is priced as a margin over EIBOR (the Emirates Interbank Offered Rate).
The UAE banking sector holds over AED 4 trillion in assets, yet fewer than 30% of small business owners in Dubai secure bank credit on the first attempt (Central Bank of the UAE, 2026). This guide is for owners who want to be in that 30%.
What Is a UAE Company Overdraft Facility and Why It Matters
A UAE company overdraft facility is a revolving credit line attached to a corporate current account that lets the business spend beyond its balance up to an approved limit. Interest is charged only on the amount used, which makes it a flexible working capital facility in the UAE for covering short-term cash gaps. It's the first product most companies ask for after reading about getting your first credit facility as a Dubai company.
How a Business Overdraft in Dubai Works
The bank sets a limit against your current account and reviews it annually. Interest accrues daily on the drawn balance only. Limits typically land at 10-25% of annual turnover, priced as EIBOR plus a margin.
Picture a Dubai South trading company with AED 150,000 in monthly inflows. It receives an AED 100,000 limit to bridge 60-day customer payment delays. Security is usually post-dated cheques, a company guarantee or a lien on deposits.
Overdraft vs Term Loan vs Trade Finance
Overdrafts suit recurring short gaps. Term loans suit asset purchases. Trade finance suits import and export cycles. A services firm might use an overdraft for payroll timing while a term loan funds equipment.
Overdraft vs Term Loan vs Trade Finance for UAE Companies (indicative AED figures, as of May 2026)
Feature | Business Overdraft | Term Loan | Trade Finance |
|---|---|---|---|
Typical limit or amount in AED | AED 50,000 to AED 500,000 (10-25% of turnover) | AED 100,000 to AED 2 million, fixed amount | Sized per shipment or purchase order |
Interest basis (EIBOR plus margin) | EIBOR plus margin, on drawn balance only | EIBOR plus margin, on the full amount | Commission and interest per transaction |
Arrangement fee and date quoted | 0.5-1% of limit (May 2026, confirm with bank) | Often 1% of amount (May 2026, confirm with bank) | Per-transaction fees (May 2026, confirm with bank) |
Security required | Post-dated cheques, guarantee or deposit lien | Asset charge, guarantee or cheques | The underlying goods and documents |
Best use case | Payroll timing, 45-60 day receivable gaps | Equipment, fit-out, expansion | Import and export cycles |
Which Requirements Must a Free Zone Company Meet to Qualify
Banks generally require a valid trade license, six to twelve months of account history, consistent turnover, audited or management financials, and clean credit records for the company and owners. Free zone companies must also show real operations, such as contracts, invoices and a lease, before a bank extends unsecured credit. That's the gate for any business overdraft in Dubai.
Documents Banks Ask For
Trade license, MOA, and lease or flexi-desk agreement.
Six to twelve months of bank statements.
Financial statements, VAT returns and corporate tax registration.
Passports, Emirates IDs and residency visas of shareholders.
Turnover thresholds often start around AED 1 million a year, though each bank differs. One consultancy I'd point to as a model submitted 12 months of statements and three client contracts.
Credit Score and Al Etihad Credit Bureau Checks
The bank pulls reports on you and the company from Al Etihad Credit Bureau. Bounced personal cheques and missed payments hurt approval. A founder who cleared a small card arrear before applying avoided a decline, so check your scores first and clear liabilities.
Why Trade License and Residency Matter
An active license with a residency visa package signals substance. A Dubai South Business Hub Free Zone license and visas help establish a verifiable UAE presence. Plan the budget with the cost calculator, then run the company name check before opening your account. Our guide to opening a corporate bank account for your Dubai free zone company covers the next move.
Which Regulations in the UAE Govern a UAE Company Overdraft Facility
The Central Bank of the UAE regulates bank lending, including credit risk, exposure rules, and cheque and insolvency frameworks. Banks also apply AML (anti-money laundering) and KYC (know your customer) checks, and corporate tax and VAT records feed into credit assessment. Each bank then sets its own pricing and security policy for a UAE company overdraft facility.
Central Bank Oversight and Lending Standards
With over 40 licensed commercial banks, limits differ widely. Prudential rules cap exposure and require provisioning, but banks decide limits internally. Two banks can offer the same company very different limits.
Tax and Compliance Records Banks Review
UAE corporate tax registration and filings (Federal Tax Authority).
VAT returns to verify AED turnover.
Economic substance evidence and periodic KYC refresh.
Declines often follow a gap here. See why UAE banks reject new company account applications.
Step-by-Step Guide to Get a UAE Company Overdraft Facility
To get a UAE company overdraft facility: open a corporate account, build six months of activity, prepare documents, choose banks, submit a request, negotiate pricing and security, sign the facility letter, and activate the limit. Following these ordered steps typically moves you from application to drawdown within two to six weeks.
Step 1: Open and Seed the Corporate Account
Open it once your license is issued.
Route all client receipts through it. One startup ran every invoice through one account for six months.
Keep balances above the minimum, often AED 5,000 to AED 25,000.
Step 2: Prepare Financials and Cash Flow Forecast
Build a 12-month forecast and receivables ageing.
State the purpose clearly, such as a 45-day payment gap.
Size the limit to 1-2 months of operating costs.
Step 3: Submit the Application and Negotiate Terms
Compare margin, arrangement fee and security across banks.
Ask about renewal and early closure fees.
Use leverage: moving payroll to the bank can lower the arrangement fee.
Step 4: Sign, Activate and Monitor
Read facility letter covenants carefully.
Track utilisation against the annual review cycle.
Set a calendar alert for renewal documents.
For wider lending criteria, read business loan requirements in Dubai.
How Much Does It Cost and How Long Does It Take to Get a Business Overdraft in Dubai
Costs include interest of roughly EIBOR plus 3-8% annually, an arrangement fee often 0.5-1% of the limit, and annual renewal fees. Approval typically takes two to six weeks once documents are complete. Fees vary by bank, so confirm current AED figures and the quote date in writing before you accept a business overdraft in Dubai.
Typical Fees and Pricing in AED
Cost item | Indicative figure (as of May 2026) |
|---|---|
Interest margin | EIBOR plus 3-8% a year |
Arrangement fee | 0.5-1% of limit (AED 500 to AED 1,000 on AED 100,000) |
Annual renewal fee | Varies by bank, confirm in writing |
Early closure fee | Varies by bank, confirm in writing |
Budget your setup costs first with the cost calculator, and check minimum balance rules for business accounts.
Timeline From Application to Drawdown
Document review takes 3-7 days, the credit committee 1-3 weeks, and documentation 3-5 days. File on a Monday and the limit could be live in four weeks.
Which Mistakes Should You Avoid When Applying for a Working Capital Facility in the UAE
Common mistakes include applying before building account history, requesting an oversized limit, submitting incomplete financials, ignoring personal credit issues, and relying on one bank. Each triggers declines or weak pricing. Preparing a clean forecast and approaching two or three banks improves your odds on any working capital facility in the UAE.
Application and Documentation Errors
Figures that don't match between statements and financials.
An expired license or lease.
An unreconciled VAT return, a classic cause of decline.
Using the Overdraft the Wrong Way
Treating it as permanent capital.
Staying maxed out, which hurts renewal. Keep utilisation under about 70%.
Mixing personal expenses with company spending.
One firm that sat at full utilisation every month moved to a term loan instead.
What Should You Do Next to Secure a UAE Company Overdraft Facility
Start by confirming your license and corporate account are active, run your numbers through the cost calculator, gather twelve months of records, and approach two or three banks. A properly structured request improves approval odds and your negotiating power on pricing.
Build Your Banking Readiness Checklist
Active license, visa, account and records.
Consistent company name, confirmed with the name check before bank KYC.
At least six months of history.
Get Set Up With Dubai South Business Hub
A Dubai South Business Hub Free Zone license with a residency visa package gives you a bank-ready base. Open the cost calculator, bundle your license and visa, then open the account and start building history.
Conclusion
A UAE company overdraft facility rewards businesses that show account history, clean financials and a clear funding purpose. Prepare early, compare banks, and treat the overdraft as short-term working capital, not permanent funding. Use the Dubai South Business Hub cost calculator and name check to plan your setup, then build the track record you need.
References
Frequently Asked Questions