Topic Summary
Do UAE Banks Reject New Company Account Applications? The Reason Behind It
Yes, banks decline applicants mainly because of compliance risk. They follow Central Bank of the UAE anti-money-laundering rules, so unclear ownership, vague activity or missing documents lead to a no. It's about risk, not the license itself.
Do UAE Banks Reject New Company Account Applications: Top Reasons
Do UAE Banks Reject New Company Account Applications: Top Reasons
Bank-by-Bank Expectations for Free Zone Companies
Each bank has its own risk appetite. Emirates NBD, FAB and ADCB favour established profiles, Mashreq and RAKBank suit SMEs, and Wio offers a digital route. Dubai South Business Hub free zone companies are eligible applicants at these banks.
Step-by-Step Guide to Avoid Account Rejection in the UAE
Choose a bank matching your profile, align documents, define your activity, evidence funds, show substance and submit once. This is how you stop UAE banks rejecting new company account applications from your side.
Realistic Timelines and Costs
Expect one to four weeks for a complete file, and six or more for complex ownership. Costs are mainly minimum balances and monthly fees.
What to Do After a Rejection
Ask for feedback, fix the gaps, wait a sensible period and reapply at a better-fit bank. Don't send multiple applications at once.
Next Steps for Your Application
Do UAE banks reject new company account applications? Yes, but mostly for avoidable reasons: mismatched documents, unclear ownership, vague activity and thin proof. Match the right bank, submit a clean file and answer quickly. Speak with the DSBH team about banking support for your Dubai South Business Hub company before you submit.
Roughly 40% of first-time Dubai founders report a delayed or declined corporate account at least once [1]. Over 40 licensed banks operate in the UAE (Central Bank of the UAE, 2025) [2]. So why do UAE banks reject new company account applications? This guide is for free zone owners who want approval first time. You'll get the real reasons, bank expectations and a clear plan. A complete file typically clears in 2 to 4 weeks [3].
Do UAE Banks Reject New Company Account Applications? The Reason Behind It
Yes, banks decline applicants mainly because of compliance risk. They follow Central Bank of the UAE anti-money-laundering rules, so unclear ownership, vague activity or missing documents lead to a no. It's about risk, not the license itself.
Defining Account Rejection
Rejection is a formal decline or an indefinite hold, often with no detailed reason. A license is only the starting point. Compliance teams decide, not relationship managers alone. Picture a new consulting company that submits a license and passport copies only, then waits weeks for a generic decline.
The Compliance Framework
AML/CFT (anti-money-laundering and counter-terrorism financing) duties, KYC (know your customer) and UBO (ultimate beneficial owner) checks set the baseline. Banks also want your source of funds and expected transaction flows. One founder who couldn't evidence his initial capital deposit was declined on the spot. Banks err on the side of declining, because the Central Bank of the UAE penalises weak verification.
Do UAE Banks Reject New Company Account Applications: Top Reasons
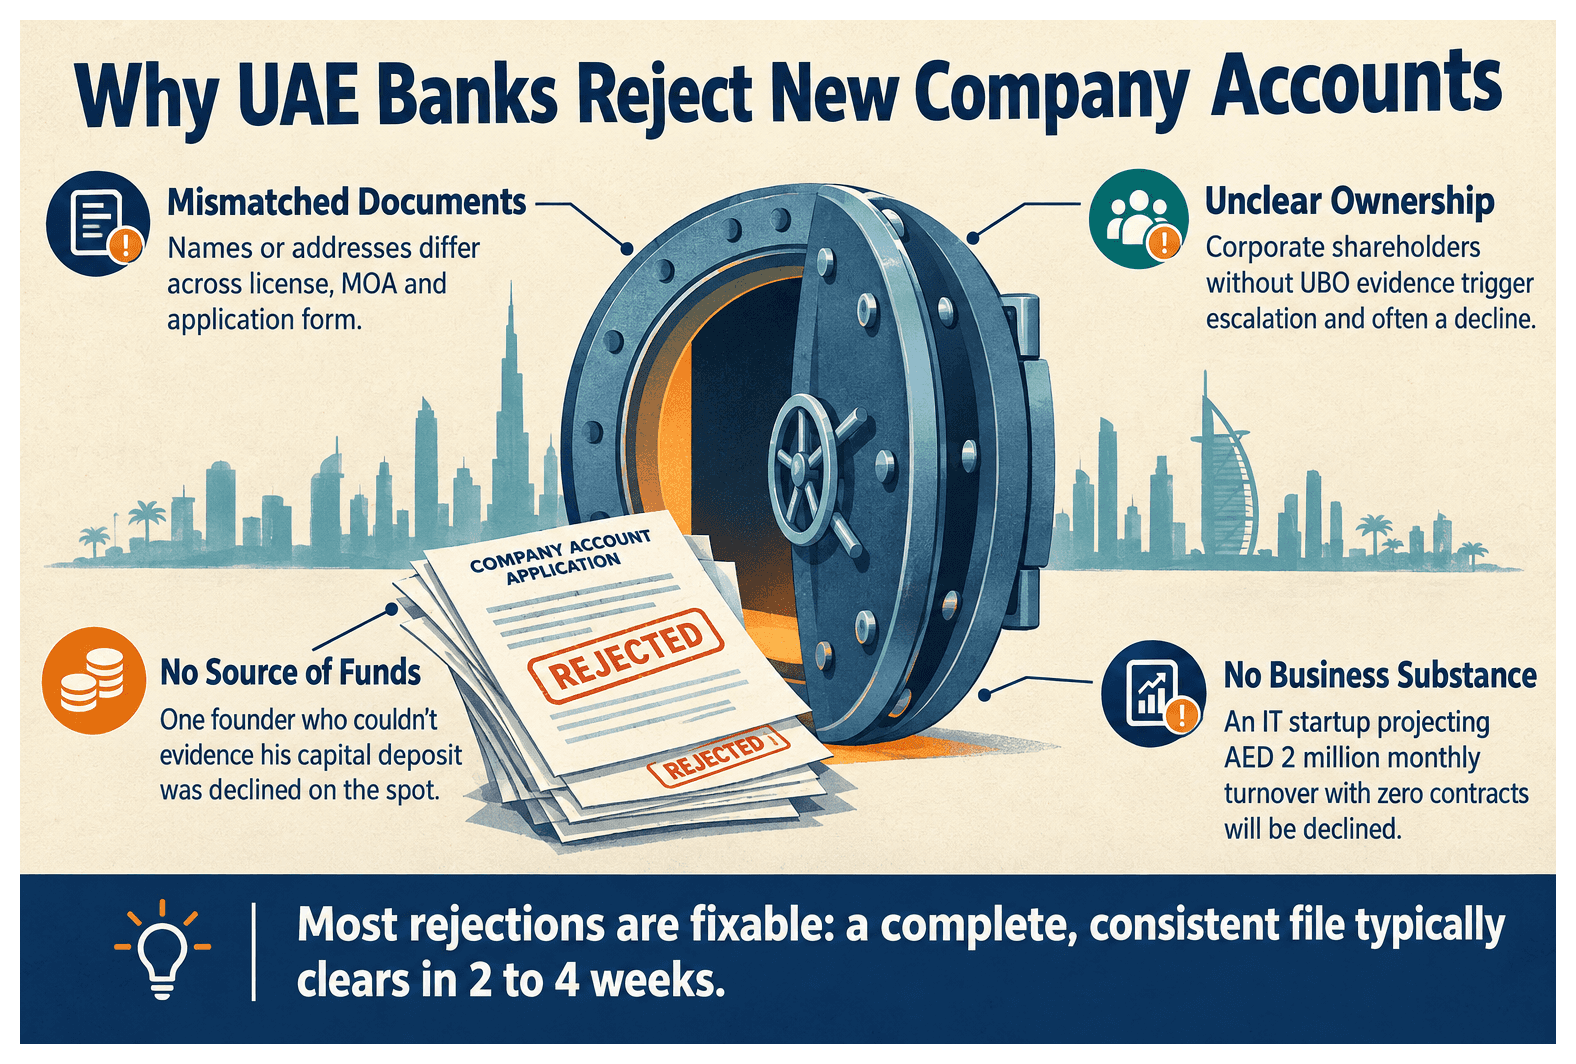
The most common reasons are mismatched documents, unclear UBO details, vague or high-risk activity, no source-of-funds proof and no business substance. Most are fixable before you apply. See UAE business bank account rejection common reasons for more.
Incomplete or Mismatched Documentation
Names or addresses differ across license, MOA and form.
Passports are expired or the lease proof is missing.
Phone or email details are wrong.
One founder listed a different phone number on the form than on the MOA. Verification failed and the file closed silently.
UAE Banks Compared for New Free Zone Company Accounts
Feature | Traditional Banks (Emirates NBD, FAB, ADCB) | SME and Digital Banks (Mashreq, RAKBank, Wio) |
|---|---|---|
Typical review depth | Deep due diligence, fuller business plans | Lighter review for simple structures |
Indicative timeline | 2 to 6 weeks with a complete file | Days to a few weeks |
Preferred applicant profile | Trading history, contracts, higher balances | Startups, small consultancies, single shareholders |
Onboarding method | Often face-to-face meetings | Branch, relationship manager or online (Wio) |
Minimum balance flexibility | Generally higher thresholds | Often lower, SME-focused tiers |
Unclear Ownership and Business Activity
Corporate shareholders without UBO evidence trigger escalation. So does "general trading" with no named customers or suppliers. Crypto, precious metals and cash-heavy trade face enhanced due diligence. An offshore holding with no organogram is a classic decline.
Lack of Business Substance and Source-of-Funds Proof
No website, invoices or signed contracts.
Projections that don't match the activity.
No statements backing your capital.
An IT startup projecting AED 2 million monthly turnover with zero contracts will be declined. Banks read that as unrealistic.
Bank-by-Bank Expectations for Free Zone Companies
Each bank has its own risk appetite. Emirates NBD, FAB and ADCB favour established profiles, Mashreq and RAKBank suit SMEs, and Wio offers a digital route. Dubai South Business Hub free zone companies are eligible applicants at these banks.
Traditional banks want supplier contracts and a clear UBO chart, then reward them with faster review. SME and digital banks still run full KYC. A single-shareholder consultancy can be approved in days, while a multi-shareholder entity needs manual review. Read what UAE banks look for in a startup application.
Step-by-Step Guide to Avoid Account Rejection in the UAE
Choose a bank matching your profile, align documents, define your activity, evidence funds, show substance and submit once. This is how you stop UAE banks rejecting new company account applications from your side.
Prepare one consistent pack. License, MOA, share certificate, lease, passports, Emirates IDs, UBO chart. Match every name, phone and email. See documents UAE banks require from a new company.
Show substance. Describe customers, suppliers and countries. Attach two signed client agreements and a simple website.
Document funds and pick the bank. Provide statements or sale proceeds. Apply to one bank at a time, with a fallback ready.
Respond fast. Answer queries within 24 to 48 hours and keep your phone reachable. DSBH banking support can align your documents first.
Realistic Timelines and Costs
Expect one to four weeks for a complete file, and six or more for complex ownership. Costs are mainly minimum balances and monthly fees.
How Long Each Stage Takes
Stages run from document review to screening, interview and activation. A clean single-shareholder file clears in about two weeks. A multi-layer structure took six. Delays usually trace to missing papers or slow replies.
Balance Requirements and Ongoing Fees
Minimums differ by bank and account type.
Fees apply below the threshold.
Confirm current figures with each bank.
What to Do After a Rejection
Ask for feedback, fix the gaps, wait a sensible period and reapply at a better-fit bank. Don't send multiple applications at once.
One founder found an address mismatch, corrected it and passed on the second try. Another, declined by a traditional bank, succeeded at an SME bank after adding client contracts. Read about setting up a Dubai company after a bank rejection.
Next Steps for Your Application
Do UAE banks reject new company account applications? Yes, but mostly for avoidable reasons: mismatched documents, unclear ownership, vague activity and thin proof. Match the right bank, submit a clean file and answer quickly. Speak with the DSBH team about banking support for your Dubai South Business Hub company before you submit.
References
Frequently Asked Questions