Topic Summary
What Is Opening a UAE Corporate Bank Account as a Brazilian Entrepreneur and Why It Matters
Opening a UAE corporate bank account as a Brazilian entrepreneur means getting a licensed bank to onboard your free zone company under Central Bank KYC and anti-money-laundering rules. You can then invoice clients, pay suppliers, run payroll and keep business money separate from personal funds.
Documents and Licensing Prerequisites Brazilian Founders Must Prepare
Documents and Licensing Prerequisites Brazilian Founders Must Prepare
Choosing the Right Bank and Account Structure for Your Brazilian Company
Choose a bank by expected turnover, currencies, transaction countries and onboarding preference. Traditional banks suit larger balances and trade finance, while digital banks suit lean startups. Compare minimum balances, fees and remittance costs for your UAE corporate bank account before applying.
Step-by-Step Guide to Opening a UAE Corporate Bank Account as a Brazilian Entrepreneur
To start, obtain your license, shortlist banks, assemble KYC documents, apply, attend compliance interviews, fund the account and activate online banking. Align your license activity with real operations to avoid delays.
Fees, Timelines and Compliance Obligations to Budget For
Budget for maintenance fees, minimum balances and transfer charges, which differ by bank. Timelines run from days to several weeks. Confirm every charge in the bank's current tariff before applying.
Why Banks Decline Applications and How to Avoid Rejection
Banks commonly decline over unclear ownership, mismatched license activity, weak source-of-funds evidence or inconsistent documents. Answer compliance questions fully and promptly to protect your UAE corporate bank account application.
Your Next Step
Opening a UAE corporate bank account as a Brazilian entrepreneur comes down to a matching license, a consistent KYC pack and the right bank. Speak with Dubai South Business Hub to secure your license and residency visa package, then follow the steps above.
The UAE has more than 40 licensed commercial banks supervised by the Central Bank of the UAE [1]. Yet roughly 40% of first-time founders hit a delay or decline before approval. Opening a UAE corporate bank account as a Brazilian entrepreneur is manageable once you know what to prepare first. This guide covers documents, sequence, costs and rejection triggers.
What Is Opening a UAE Corporate Bank Account as a Brazilian Entrepreneur and Why It Matters
Opening a UAE corporate bank account as a Brazilian entrepreneur means getting a licensed bank to onboard your free zone company under Central Bank KYC and anti-money-laundering rules. You can then invoice clients, pay suppliers, run payroll and keep business money separate from personal funds.
How UAE Banking Regulation Shapes Your Application
The Central Bank of the UAE enforces AML/CFT requirements, and banks apply risk-based due diligence. Ownership and source of funds get scrutinised. Each bank also sets its own appetite and minimum balances. Picture a São Paulo software consultant whose company is approved quickly because the activity and client base are documented clearly.
Why a Corporate Account Matters for Brazilian Founders
Receive payments and settle in AED, USD or EUR.
Run payroll and use your visa quota.
Support VAT and corporate tax compliance.
Build the banking history that credit needs.
An import-export founder paying Asian suppliers in USD from a company account avoids routing money through personal accounts. See multiple currency corporate bank accounts in the UAE.
Documents and Licensing Prerequisites Brazilian Founders Must Prepare
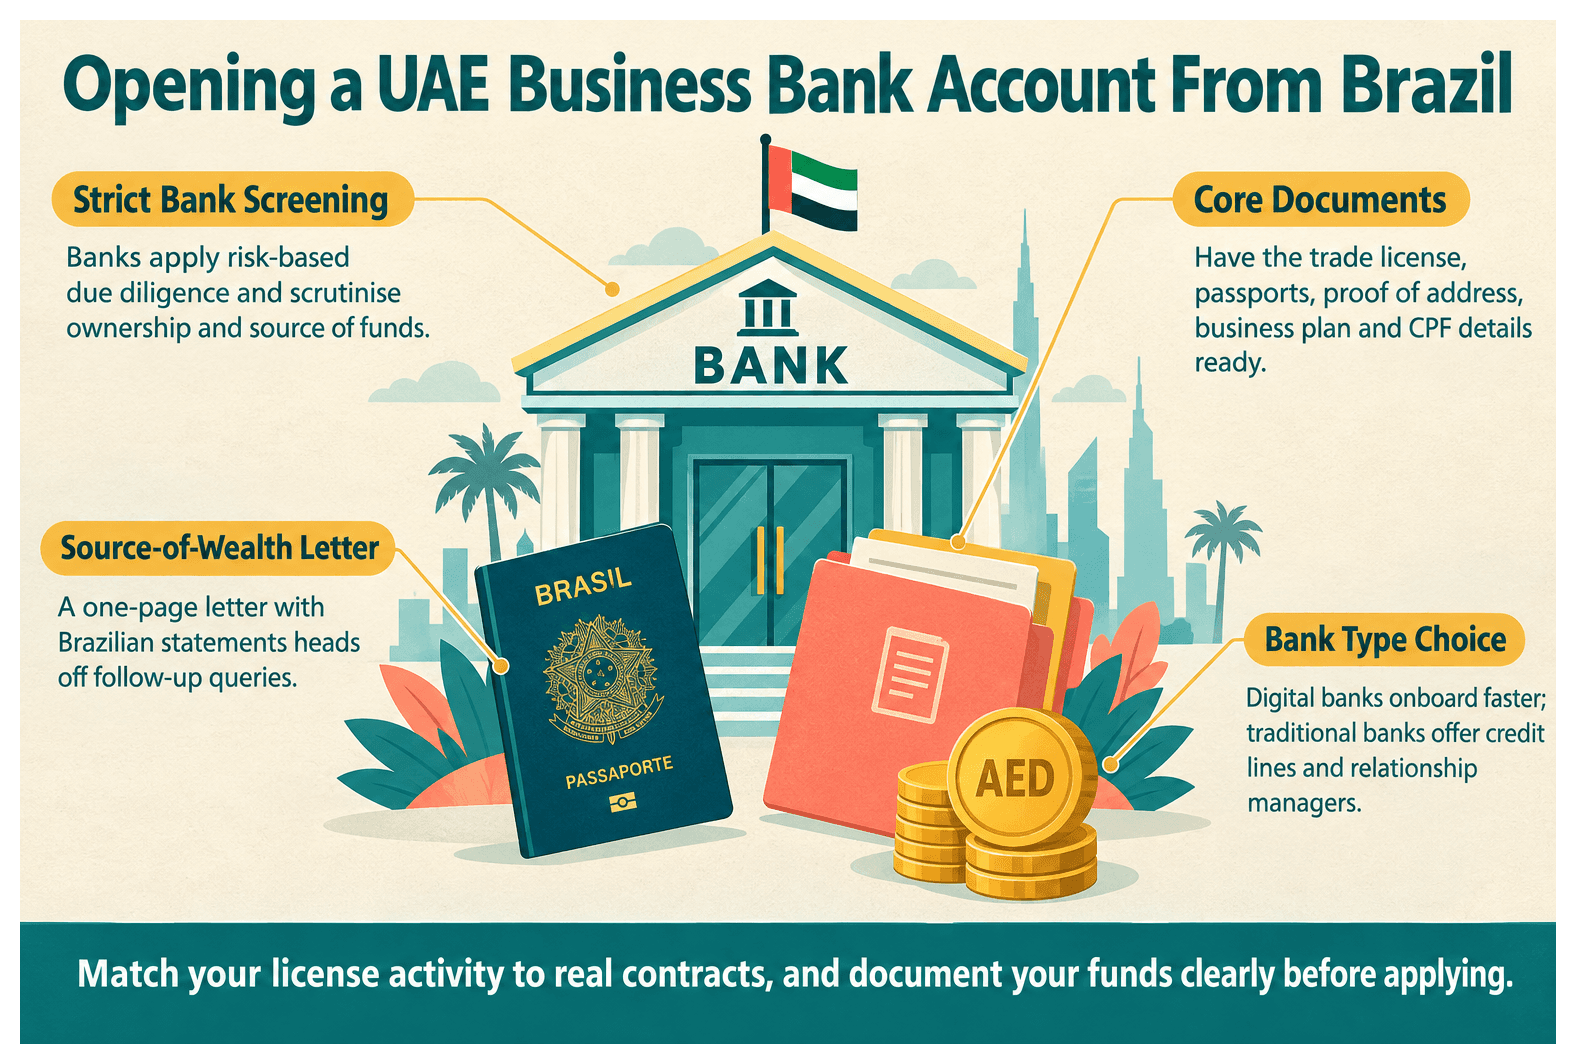
Banks typically want a valid free zone trade license, incorporation papers, shareholder passports, proof of address, a business plan and source-of-funds evidence. A Brazilian founder should also have CPF details ready, plus translated or attested records where requested.
Core Corporate and Personal Documents
Trade license, articles, share certificate and lease or flexi-desk agreement.
Passport copies, Brazilian proof of address and a professional profile.
Bank statements and tax records showing source of funds.
A one-page source-of-wealth letter with Brazilian statements heads off follow-up queries. Review the documents UAE banks require from a new company.
Traditional Banks Versus Digital Business Banks for Brazilian Founders
Feature | Traditional Bank | Digital Business Bank |
|---|---|---|
Onboarding speed | Slower, with in-depth compliance review | Faster, mostly online |
Minimum balance expectations | Higher average balances expected | Lower or flexible thresholds |
Trade finance and credit access | Full trade finance and credit lines | Limited credit products |
Relationship manager support | Dedicated manager | App and chat support |
Best fit for turnover level | Established, higher-volume firms | Lean startups and consultancies |
Licensing Through Dubai South Business Hub Free Zone
Your license activity must match your real contracts and invoices. Dubai South Business Hub Free Zone offers full foreign ownership, no UAE sponsor requirement and residency visa packages tied to the license. A Brazilian logistics founder, for instance, would pick an activity that fits Dubai South's aviation and logistics ecosystem.
Residency Status and Emirates ID Considerations
The Federal Authority for Identity, Citizenship, Customs and Port Security (ICP) issues residence and Emirates ID records, which many banks prefer. Some banks onboard earlier with limited terms. Read about corporate bank account for non-residents in the UAE if you apply from Brazil first.
Choosing the Right Bank and Account Structure for Your Brazilian Company
Choose a bank by expected turnover, currencies, transaction countries and onboarding preference. Traditional banks suit larger balances and trade finance, while digital banks suit lean startups. Compare minimum balances, fees and remittance costs for your UAE corporate bank account before applying.
Multi-Currency and Brazil-Related Payment Needs
Hold AED, USD and EUR to cut conversion losses.
Ask how the bank handles BRL transfers and compliance queries.
Match account features to your invoicing currency.
Consider a founder billing Brazilian clients in USD while paying UAE costs in AED. Cross-border payment context is available from the World Bank.
Step-by-Step Guide to Opening a UAE Corporate Bank Account as a Brazilian Entrepreneur
To start, obtain your license, shortlist banks, assemble KYC documents, apply, attend compliance interviews, fund the account and activate online banking. Align your license activity with real operations to avoid delays.
Secure your license. Incorporate with Dubai South Business Hub Free Zone and confirm activity wording. See opening a corporate bank account after licensing.
Submit your KYC pack. Send one complete, consistent package with sample contracts supporting projected revenue.
Complete the compliance review. Answer questions quickly, provide Emirates ID where required, then fund the account and set signatories.
Fees, Timelines and Compliance Obligations to Budget For
Budget for maintenance fees, minimum balances and transfer charges, which differ by bank. Timelines run from days to several weeks. Confirm every charge in the bank's current tariff before applying.
After opening, the Federal Tax Authority handles VAT and corporate tax registration. Reconcile monthly statements from day one so filings stay simple. Details are in Dubai South banking requirements.
Why Banks Decline Applications and How to Avoid Rejection
Banks commonly decline over unclear ownership, mismatched license activity, weak source-of-funds evidence or inconsistent documents. Answer compliance questions fully and promptly to protect your UAE corporate bank account application.
Why do UAE banks reject corporate account applications?
Most rejections trace to a license activity that doesn't match client contracts, unexplained funds, or details that differ across documents. One founder was declined when the bank couldn't verify a client, then approved after resubmitting contracts. More in why UAE banks reject corporate account applications.
Before reapplying, ask for the reason category, fix the gap, and update your source-of-wealth letter.
Your Next Step
Opening a UAE corporate bank account as a Brazilian entrepreneur comes down to a matching license, a consistent KYC pack and the right bank. Speak with Dubai South Business Hub to secure your license and residency visa package, then follow the steps above.
References
Frequently Asked Questions