Topic Summary
What Is UAE VAT Voluntary Disclosure: How to Fix an Error in a Filed Return
UAE VAT voluntary disclosure is the formal route for correcting an error in a VAT return you've already filed. You submit Form VAT 211 through the EmaraTax portal, declare the corrected figures, and settle any extra tax due. It applies when the error is too large for a simple adjustment in your next return.
When You Can Correct a VAT Return Error Without Filing a Disclosure
When You Can Correct a VAT Return Error Without Filing a Disclosure
Common Errors in Filed Returns That Trigger a Disclosure
The usual triggers are unreported sales, wrongly claimed input VAT, incorrect zero-rating, missed reverse charge entries, and non-compliant invoices. Most come from bookkeeping or system mapping, not intent. Each still needs a formal correction once you find an error in a filed return.
Step-by-Step Guide to UAE VAT Voluntary Disclosure: How to Fix an Error in a Filed Return
Log in to EmaraTax, open your VAT account, and select Voluntary Disclosure (VAT 211). Enter original and corrected figures, explain the cause, upload evidence, and submit. Then pay any extra tax and penalties.
Penalties and Deadlines When You Fix an Error in a Filed Return
Penalties depend on the error and timing. The FTA applies fixed penalties for incorrect returns plus percentage penalties on unpaid tax. Early disclosure limits exposure. Rules were amended by Cabinet Decision, so check the schedule on tax.gov.ae before submitting.
Practical Safeguards for Free Zone Finance Teams
Prevent repeat disclosures with a pre-filing review. Reconcile the ledger to invoices, check zero-rating evidence, verify reverse charge entries, and have a second person approve each VAT201. Free zone companies remain subject to UAE VAT, and designated zone treatment covers only qualifying goods.
Your Next Step
UAE VAT voluntary disclosure: how to fix an error in a filed return comes down to three decisions: quantify the error, choose between adjustment and Form VAT 211, and disclose quickly. Review your last four VAT201 returns this week. If you find a discrepancy, file on EmaraTax or speak with a Dubai South Business Hub adviser.
More than 350,000 UAE businesses are VAT-registered (Federal Tax Authority, 2025), and each will eventually spot a wrong figure in a filed VAT201. This guide explains UAE VAT voluntary disclosure: how to fix an error in a filed return, when you need it, and what it costs. It's written for free zone owners and finance managers.
What Is UAE VAT Voluntary Disclosure: How to Fix an Error in a Filed Return
UAE VAT voluntary disclosure is the formal route for correcting an error in a VAT return you've already filed. You submit Form VAT 211 through the EmaraTax portal, declare the corrected figures, and settle any extra tax due. It applies when the error is too large for a simple adjustment in your next return.
How the Federal Tax Authority Defines a Voluntary Disclosure
A registrant who finds an error has a legal duty to tell the FTA. Under the UAE VAT Law and its Executive Regulation, you do that on Form VAT 211, not by refiling the VAT201.
Picture a free zone trading company that under-declared AED 60,000 of taxable sales. At the 5% standard rate, that's AED 3,000 of unpaid VAT, and it files a VAT 211 to correct it.
Why a Filed Return Can't Simply Be Edited
Once submitted, a VAT201 is locked. One finance manager we'd describe as typical hunts for an edit button, finds none, and learns the fix must go through VAT 211. That's deliberate: corrections leave an audit trail, and the FTA treats voluntary action more favourably than errors it finds first. See our guide to VAT return filing for Dubai companies.
Next-Return Adjustment vs Voluntary Disclosure (VAT 211)
Feature | Next-Return Adjustment | Voluntary Disclosure (VAT 211) |
|---|---|---|
When it applies | Net error below AED 10,000 and not deliberate | Net error at or above AED 10,000, or any deliberate error |
Where it is filed | Inside your next VAT201 on EmaraTax | Separate Form VAT 211 on EmaraTax |
Error size | Small, netted across the same period | Large, such as AED 150,000 of unreported reverse charge |
Penalty exposure | Generally none if adjusted correctly | Penalties apply, but are limited by early disclosure |
Record to keep | Internal note and workings for the adjustment | Submission confirmation, workings, payment reference |
When You Can Correct a VAT Return Error Without Filing a Disclosure
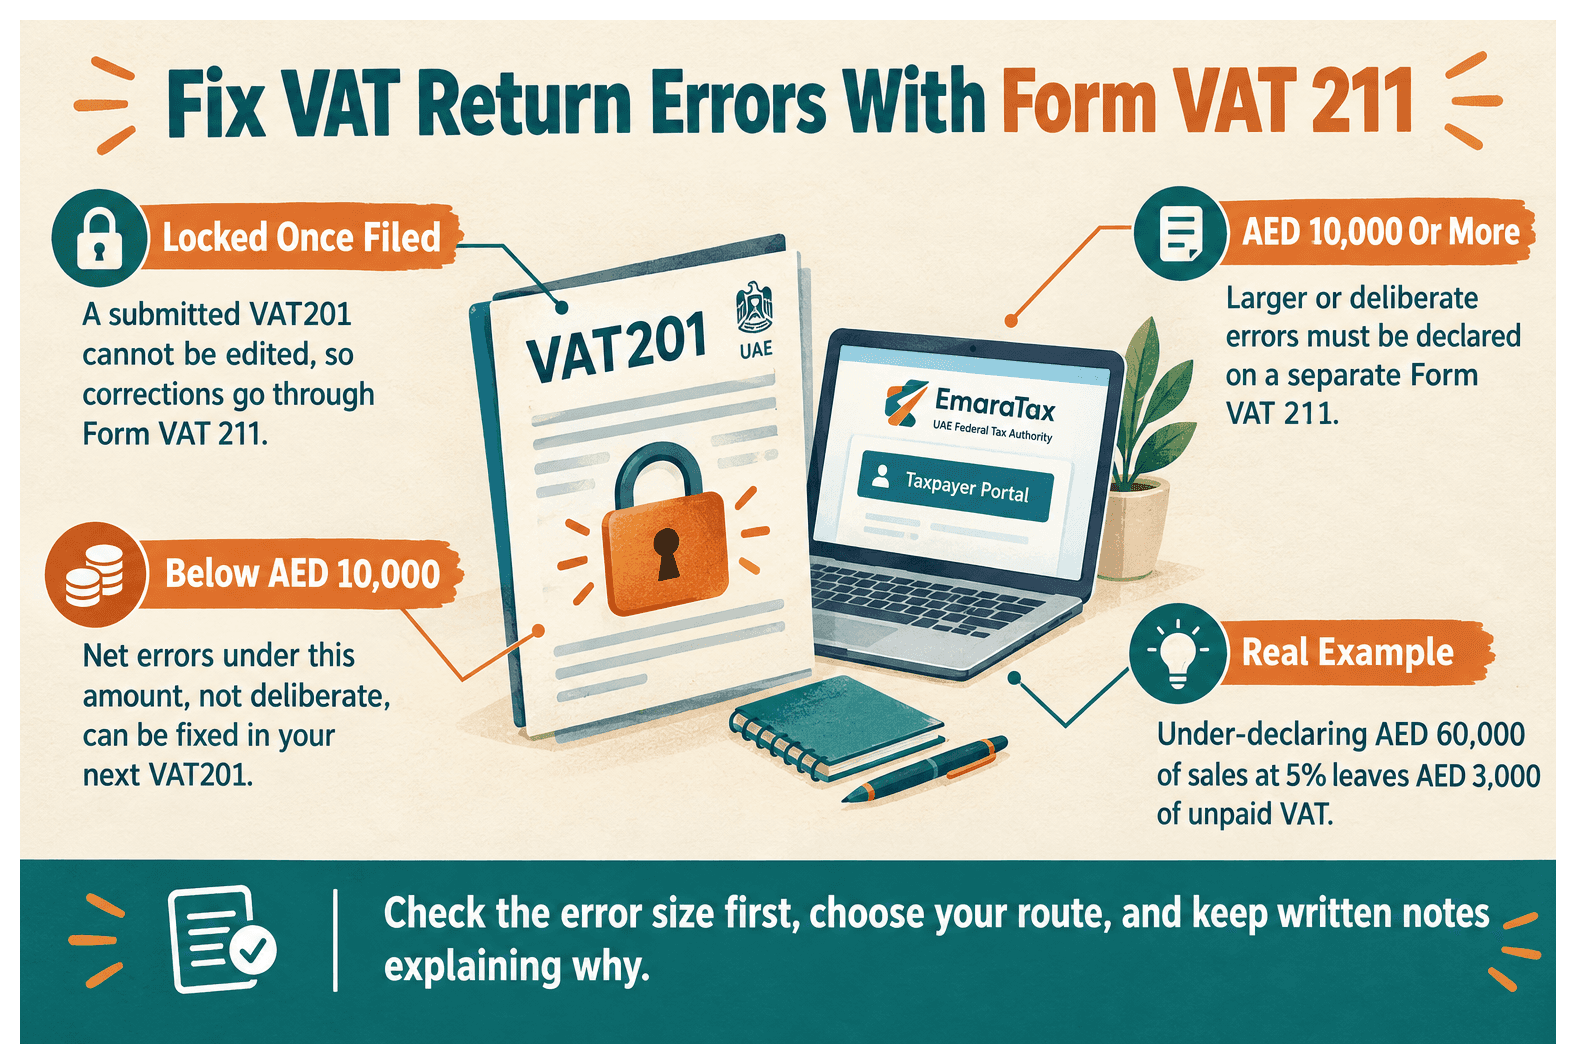
Not every mistake needs a voluntary disclosure. Under FTA rules, errors with a net value below AED 10,000 can usually be corrected in your next VAT201. Larger errors, or any you know were deliberate, must go through Form VAT 211. Confirm the current threshold on tax.gov.ae first.
The Next-Return Adjustment for Minor Errors
Net over- and under-declarations within the same period.
A consultancy that over-claimed AED 3,200 of input VAT adjusts it next return.
Errors That Always Require Form VAT 211
Net errors above the threshold.
Returns already under FTA audit, which are handled differently.
Missed reverse charge VAT on AED 150,000 of imported services.
Write down why you chose your route. You'll want that note if the FTA asks.
Common Errors in Filed Returns That Trigger a Disclosure
The usual triggers are unreported sales, wrongly claimed input VAT, incorrect zero-rating, missed reverse charge entries, and non-compliant invoices. Most come from bookkeeping or system mapping, not intent. Each still needs a formal correction once you find an error in a filed return.
Output Tax Mistakes
Sales omitted from the return.
A designated zone goods supplier zero-rating a mainland sale that's actually 5% standard-rated.
Input Tax Mistakes
Claiming VAT on client entertainment, which isn't recoverable.
Recording import VAT twice.
Documentation and Invoice Gaps
Supplier invoices without a Tax Registration Number (TRN) lead to disallowed input tax. Reconcile invoices to ledgers before filing, and check the tax invoice requirements.
Step-by-Step Guide to UAE VAT Voluntary Disclosure: How to Fix an Error in a Filed Return
Log in to EmaraTax, open your VAT account, and select Voluntary Disclosure (VAT 211). Enter original and corrected figures, explain the cause, upload evidence, and submit. Then pay any extra tax and penalties.
Step 1: Quantify the Error
Rebuild the period from the ledger. A finance team reconciling Q2 sales to invoices finds an AED 18,500 VAT shortfall. That's above AED 10,000, so VAT 211 it is.
Step 2: Open Form VAT 211 on EmaraTax
Sign in as an authorised user, pick the VAT account, start the disclosure, and choose the tax period.
Step 3: Enter Corrected Figures and Explanation
Show original versus corrected boxes. Give a short, factual reason and attach supporting documents.
Step 4: Submit and Settle Payment
Pay the extra tax and any penalty using the payment reference.
Keep the confirmation for at least five years.
If you overpaid, ask for an offset or VAT refund.
Penalties and Deadlines When You Fix an Error in a Filed Return
Penalties depend on the error and timing. The FTA applies fixed penalties for incorrect returns plus percentage penalties on unpaid tax. Early disclosure limits exposure. Rules were amended by Cabinet Decision, so check the schedule on tax.gov.ae before submitting.
Fixed and Percentage Penalties
Fixed penalties rise for repeat errors.
Percentage penalties accrue on unpaid tax.
A prompt AED 18,500 disclosure costs less than the same amount found in audit.
Why Speed Matters
Disclose when you find the error. Waiting lets percentage penalties compound, and disclosure after the FTA announces an audit may not carry the same benefit. More in VAT penalties and how to avoid them.
Practical Safeguards for Free Zone Finance Teams
Prevent repeat disclosures with a pre-filing review. Reconcile the ledger to invoices, check zero-rating evidence, verify reverse charge entries, and have a second person approve each VAT201. Free zone companies remain subject to UAE VAT, and designated zone treatment covers only qualifying goods.
Build a Pre-Filing Review Routine
Maker-checker sign-off on every return.
Ledger totals reconciled to VAT201 boxes.
A three-day review window before each deadline, as a Dubai South logistics firm might adopt.
Keep Clean Records and Link Corporate Tax
A disclosure that raises taxable sales also raises revenue for corporate tax. Check whether a corporate tax return amendment is needed, and store disclosure files with their documents.
Your Next Step
UAE VAT voluntary disclosure: how to fix an error in a filed return comes down to three decisions: quantify the error, choose between adjustment and Form VAT 211, and disclose quickly. Review your last four VAT201 returns this week. If you find a discrepancy, file on EmaraTax or speak with a Dubai South Business Hub adviser.
References
Frequently Asked Questions