Tax Treaty Between the UAE and France: What It Means for Your Company
Topic Summary
What Is the Tax Treaty UAE France and Why It Matters
The tax treaty uae france is a bilateral double tax agreement that decides which country may tax dividends, interest, royalties and business profits when income crosses the border. It prevents double taxation and sets a dispute procedure. The uae france double tax agreement has applied since 1990, so always check the current text.
What the UAE France Double Tax Agreement Covers
What the UAE France Double Tax Agreement Covers
France Company Dubai Tax Position for a Free Zone License
A France company Dubai tax position depends on where the business is managed and who owns it. A Dubai South Business Hub Free Zone company is a UAE taxable person, and French rules can still reach the owner, so treaty relief works alongside French domestic law.
How French Founders Claim Treaty Benefits
To claim relief, confirm residency, obtain a UAE tax residence certificate from the FTA, gather proof of substance, file with the Direction Générale des Finances Publiques (DGFiP), and keep records. Match each claim to its income type.
Residency Evidence That Backs a Treaty Claim
Residency evidence shows authorities where you live and work: a residence visa via the ICP (Federal Authority for Identity, Citizenship, Customs and Port Security) or GDRFA (General Directorate of Residency and Foreigners Affairs, Dubai), an Emirates ID, a tenancy contract, utility bills and travel records.
Treaty Risks and Compliance Traps for French Owners
The main risks are claiming relief without proof, treating the UAE company as a shell, and ignoring French anti-avoidance rules. A documented office, genuine management and consistent records reduce them. The tax treaty uae france won't shield a weak structure.
Treaty Quick Reference for French Free Zone Owners
Use the table above to check your position before dividends, fees or royalties move between your Dubai free zone company and France. The uae france double tax agreement rewards preparation.
The UAE's 9% corporate tax applies only to taxable profit above AED 375,000 (Federal Tax Authority, 2026), yet French founders still ask whether profit gets taxed twice. This guide explains the tax treaty uae france for owners of a Dubai South Business Hub free zone company: what it covers, where it stops, and how to claim relief.
What Is the Tax Treaty UAE France and Why It Matters
The tax treaty uae france is a bilateral double tax agreement that decides which country may tax dividends, interest, royalties and business profits when income crosses the border. It prevents double taxation and sets a dispute procedure. The uae france double tax agreement has applied since 1990, so always check the current text.
What the Agreement Actually Does
It splits taxing rights by income type and gives relief through credit or exemption. Picture a French founder whose free zone company invoices a Paris client, then pays a dividend home. The treaty tells both states who taxes what. The UAE sits on a network of over 140 such treaties, as covered in our guide to double tax treaties and your UAE company. Planning a wider move? Start with moving to Dubai from France.
Why French Founders Should Care
France taxes residents on worldwide income, so tie-break rules matter. A founder who keeps a Paris home and spends long stretches there may still count as French resident. Relief isn't automatic. You claim it, with proof.
What the UAE France Double Tax Agreement Covers
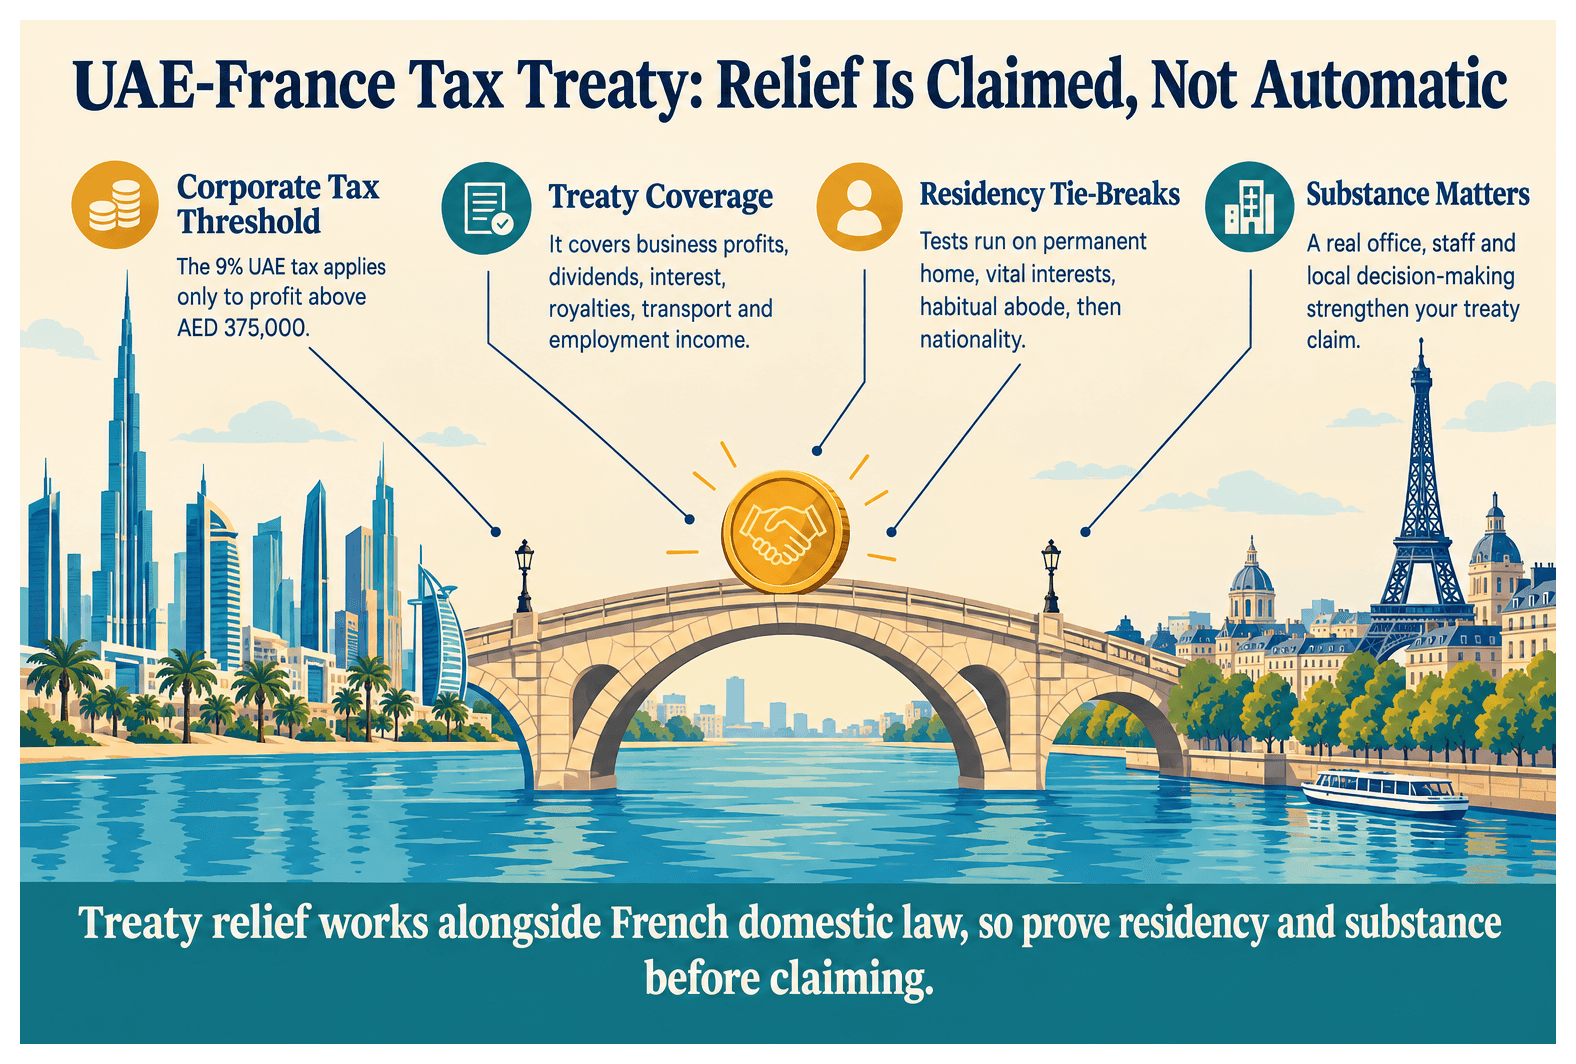
The uae france double tax agreement covers income and corporate taxes in both states. It addresses business profits, dividends, interest, royalties, shipping and air transport, and employment income, and it defines residency through tie-break rules.
Taxes and Income Types Included
Business profits: taxed where the permanent establishment sits.
Dividends, interest, royalties: rates may be capped. Confirm exact rates in the treaty text.
Transport and employment income: dedicated articles apply.
Think of a French-owned trading company in the free zone selling to EU buyers. Each revenue stream maps to a different article.
Who Qualifies as a Treaty Resident
Tie-breaks look at permanent home, centre of vital interests, habitual abode, then nationality. French nationality alone doesn't decide anything. A founder splitting time between Dubai and Lyon is tested on where family and economic ties are strongest. Companies also need a UAE tax residence certificate. For the French side, read whether setting up in Dubai changes your French tax position.
France Company Dubai Tax Position for a Free Zone License
A France company Dubai tax position depends on where the business is managed and who owns it. A Dubai South Business Hub Free Zone company is a UAE taxable person, and French rules can still reach the owner, so treaty relief works alongside French domestic law.
How Federal Decree-Law No. 47 of 2022 Interacts With the Treaty
Federal Decree-Law No. 47 of 2022 introduced UAE corporate tax, administered by the FTA. Qualifying free zone persons may access 0% on qualifying income, while other income is taxed at 9%. It isn't a blanket exemption. A company with both income lines in one year gets both treatments. The treaty and domestic law are read together. See tax benefits for Dubai free zone companies.
Dubai Free Zone French Owners and Substance
A real office, staff and local decision-making strengthen a claim.
A flexi-desk-only consultant invites challenge. An active office with local management doesn't.
Licenses come with residency visa packages and 100% foreign ownership.
How French Founders Claim Treaty Benefits
To claim relief, confirm residency, obtain a UAE tax residence certificate from the FTA, gather proof of substance, file with the Direction Générale des Finances Publiques (DGFiP), and keep records. Match each claim to its income type.
Map each income stream to a treaty article. Dividends and service fees from one company are treated differently.
Check your tie-break position before filing.
Apply for the UAE tax residence certificate through the FTA portal, after corporate tax registration. Request it before declaring a dividend.
Declare foreign income and accounts to the DGFiP, attaching credit claims and proof.
Keep documents ready in French or with translation.
Review the position every year.
Compare structures in Dubai company against a French SAS or SARL.
Residency Evidence That Backs a Treaty Claim
Residency evidence shows authorities where you live and work: a residence visa via the ICP (Federal Authority for Identity, Citizenship, Customs and Port Security) or GDRFA (General Directorate of Residency and Foreigners Affairs, Dubai), an Emirates ID, a tenancy contract, utility bills and travel records.
Visa, Emirates ID and Address Proof
ICP is the federal body for residency and identity.
GDRFA processes Dubai residency.
Emirates ID links to your permit.
A license-linked visa package supports it all.
Days Spent and Centre of Life
Keep a calendar of days in France versus the UAE, plus passport stamps. Family and economic ties count too. A founder with a lease, Emirates ID and school-age children in Dubai tells a consistent story.
UAE France Treaty Key Facts for Free Zone Owners
Feature | Treaty Topic | Practical Effect |
|---|---|---|
Business profits | Permanent establishment test | Profits taxed where the business is based, 9% UAE rate above AED 375,000 |
Dividends | Dividend article | Capped or reallocated rate; confirm in treaty text before payout |
Interest and royalties | Interest and royalty articles | Reduced withholding possible with a residence certificate |
Residency tie-break | Home, vital interests, habitual abode, nationality | Decides which state treats you as resident |
Proof and filing | FTA certificate, DGFiP forms | Relief is granted only on documented claims |
Treaty Risks and Compliance Traps for French Owners
The main risks are claiming relief without proof, treating the UAE company as a shell, and ignoring French anti-avoidance rules. A documented office, genuine management and consistent records reduce them. The tax treaty uae france won't shield a weak structure.
Substance and Place of Effective Management
Where decisions are really taken matters. If your director signs everything from Paris, French authorities may argue management sits in France. Board minutes and contracts should reflect UAE decision-making.
Corporate Law Duties Under the Code de Commerce
A retained French entity follows the Code de Commerce for accounts and filings.
A French SAS billing a Dubai affiliate must price at arm's length.
Take French advice on controlled foreign company rules.
Treaty Quick Reference for French Free Zone Owners
Use the table above to check your position before dividends, fees or royalties move between your Dubai free zone company and France. The uae france double tax agreement rewards preparation.
Next Move for Your Company
Review your structure before any payout. The tax treaty uae france is one layer beside Federal Decree-Law No. 47 of 2022 and French domestic rules, and relief depends on genuine residency, substance and correct filings. Use the Business Activities and Cost Calculator to set up or buy a license with Dubai South Business Hub Free Zone, then confirm your position with a French tax adviser. Related read: start a business in Dubai from France.
References
tax-treaty-between-the-uae-and-france-what-it-means-for-your-company