VAT Obligations for French Entrepreneurs With a Dubai Company
Topic Summary
What Are the VAT Obligations of a French-Owned Dubai Company?
VAT obligations for a French-owned Dubai company cover registration with the Federal Tax Authority (FTA), charging 5% VAT, zero-rating qualifying exports, filing returns and keeping records. Federal Decree-Law No. 47 of 2022 sets the corporate tax framework, while VAT rules sit under the UAE VAT law and apply to a DSBH license holder like any UAE business.
VAT Registration Thresholds for a French-Owned Free Zone Company
VAT Registration Thresholds for a French-Owned Free Zone Company
Zero-Rating for Exports: What French Founders Can Claim
Zero-rating means 0% VAT on qualifying exports while you still recover input VAT. Goods must leave the UAE with customs and shipping evidence on file. For a France entrepreneur UAE VAT claim, documentation decides everything.
Step-by-Step Guide to VAT Registration and Filing
Register on the FTA portal, upload your license and identity documents, receive your Tax Registration Number (TRN), issue compliant invoices, then file within 28 days of period end.
Documents and Identity Details Needed for VAT Registration
VAT registration needs your trade license, passport, Emirates ID, constitutional documents and a bank letter. Ready documents avoid rejections on the FTA portal.
How UAE VAT Interacts With French Tax and Reporting
UAE VAT is separate from French tax. The Direction Générale des Finances Publiques (DGFiP) decides your French tax residency, and the UAE-France Double Tax Treaty allocates income taxing rights. It doesn't remove VAT duties.
VAT Compliance Comparison for French-Owned DSBH Companies
Here's a quick reference for the VAT obligations French Dubai company owners should check against current FTA figures.
In 2026, more than 350,000 businesses are VAT-registered in the UAE [1], and a late registration costs a fixed AED 10,000 [2]. The rate is 5% [3], mandatory registration starts at AED 375,000 [2], and returns fall due within 28 days [2]. This guide explains the VAT obligations French Dubai company owners face, so you can register, invoice and file correctly.
What Are the VAT Obligations of a French-Owned Dubai Company?
VAT obligations for a French-owned Dubai company cover registration with the Federal Tax Authority (FTA), charging 5% VAT, zero-rating qualifying exports, filing returns and keeping records. Federal Decree-Law No. 47 of 2022 sets the corporate tax framework, while VAT rules sit under the UAE VAT law and apply to a DSBH license holder like any UAE business.
How UAE VAT Works for a DSBH License Holder
Free zone status doesn't exempt you automatically. A Lyon-based consultant invoicing UAE clients charges 5% once registered with the FTA (Federal Tax Authority, 2025). That's the baseline for any UAE VAT France founder.
Why French Founders Often Get This Wrong
They assume French logic applies (20% rate, other thresholds).
They confuse free zone corporate benefits with VAT treatment.
They register late: a Paris e-commerce founder paid the AED 10,000 penalty.
Planning your move? Read start a business in Dubai from France first.
VAT Registration Thresholds for a French-Owned Free Zone Company
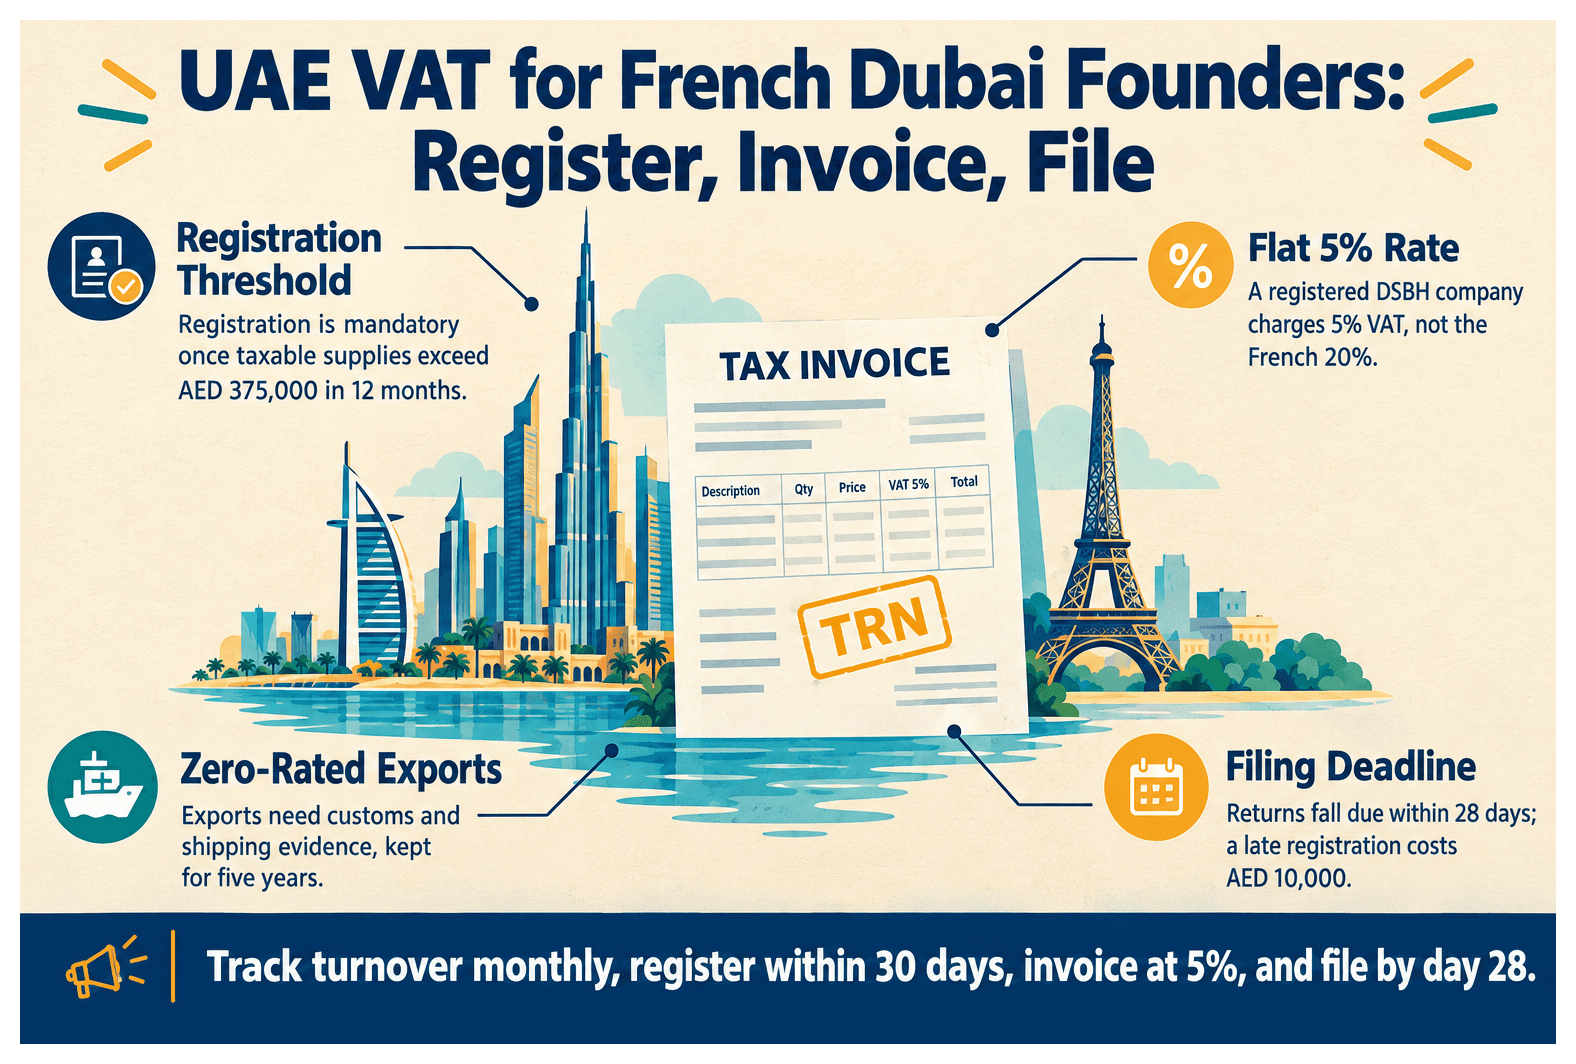
Registration is mandatory once taxable supplies exceed AED 375,000 in the previous 12 months, or you expect them to within 30 days. Voluntary registration starts at AED 187,500. For Dubai free zone VAT French founders, track rolling turnover monthly.
Mandatory limit: AED 375,000.
Voluntary limit: AED 187,500.
A founder billing AED 40,000 monthly crosses the limit in under ten months.
You've 30 days to register once you cross it.
Voluntary registration makes sense when you reclaim 5% input VAT on heavy early inventory. Zero-rated supplies still count toward the threshold, a mistake I see often. Details are in when to register your Dubai company for VAT.
Zero-Rating for Exports: What French Founders Can Claim
Zero-rating means 0% VAT on qualifying exports while you still recover input VAT. Goods must leave the UAE with customs and shipping evidence on file. For a France entrepreneur UAE VAT claim, documentation decides everything.
A DSBH trader shipping electronics to a Marseille distributor zero-rates the sale with an export declaration, bill of lading and invoice. Keep them five years. See trade between France and the UAE.
Services need a written contract and a recipient outside the UAE. A Paris client receiving design work delivered from Dubai can qualify, but if conditions fail, 5% applies (Ministry of Finance, 2025).
Step-by-Step Guide to VAT Registration and Filing
Register on the FTA portal, upload your license and identity documents, receive your Tax Registration Number (TRN), issue compliant invoices, then file within 28 days of period end.
Create your FTA e-services account and link the DSBH license.
Submit registration with expected turnover, for example AED 600,000, and receive your TRN.
Issue tax invoices showing the TRN and a 5% VAT line in AED. See invoicing your first client.
File quarterly or monthly by day 28. The first late filing costs AED 1,000. Read VAT return filing for Dubai companies.
Documents and Identity Details Needed for VAT Registration
VAT registration needs your trade license, passport, Emirates ID, constitutional documents and a bank letter. Ready documents avoid rejections on the FTA portal.
Trade license and memorandum.
Passport and Emirates ID.
Bank details and contact information.
The Identity, Citizenship, Customs and Port Security authority (ICP) issues Emirates IDs. The General Directorate of Residency and Foreigners Affairs (GDRFA) handles Dubai visas. A passport and visa spelling mismatch can stall approval, so match names everywhere.
How UAE VAT Interacts With French Tax and Reporting
UAE VAT is separate from French tax. The Direction Générale des Finances Publiques (DGFiP) decides your French tax residency, and the UAE-France Double Tax Treaty allocates income taxing rights. It doesn't remove VAT duties.
A French-resident founder who files UAE VAT correctly must still declare worldwide income. Keep a French SAS alongside, and you report both structures, plus Code de Commerce duties. Compare 5% UAE VAT with France's 20% standard rate. Check whether setting up in Dubai changes your French tax position.
VAT Compliance Comparison for French-Owned DSBH Companies
Here's a quick reference for the VAT obligations French Dubai company owners should check against current FTA figures.
UAE VAT Key Facts for French-Owned DSBH Companies
Item | UAE VAT Rule |
|---|---|
Mandatory registration threshold | AED 375,000 in taxable supplies over 12 months |
Voluntary registration threshold | AED 187,500, useful to reclaim early input VAT |
Standard and export rates | 5% standard, 0% on qualifying exports |
Return filing deadline | 28 days after period end, with payment |
Penalty and records | AED 10,000 late registration; keep records five years |
Budget compliance into setup. Model license and visa costs in the Business Activities and Cost Calculator, comparing trading with consultancy. See what a Dubai company costs a French founder.
Next Steps for Your DSBH Company
The VAT obligations French Dubai company founders carry are manageable. Register past AED 375,000, zero-rate exports with evidence, file on time and keep French reporting separate. Use the Business Activities and Cost Calculator, then set up or buy a license with DSBH. Also see our Moving to Dubai France pillar.
References
vat-obligations-for-french-entrepreneurs-with-a-dubai-company