Topic Summary
What Is It to Use Wise or Payoneer Instead of a UAE Bank Account?
To use Wise or Payoneer instead of a UAE bank account means collecting and sending business payments through a fintech platform rather than a local corporate account. It can work for small cross-border receipts, but it rarely replaces a corporate account for payroll, visas and licensing.
Limits of Trying to Use Wise or Payoneer Instead of a UAE Bank Account
Limits of Trying to Use Wise or Payoneer Instead of a UAE Bank Account
When Wise or Payoneer Make Sense Alongside a UAE Account
Wise or Payoneer work as a complement, not a replacement. Use them to receive foreign currency, pay overseas suppliers or collect marketplace income, then settle to your UAE account for payroll, rent and tax. Learn more about accepting international payments from a UAE company.
Step-by-Step Guide to Opening a UAE Corporate Account
To open a corporate account: secure your license, prepare KYC documents, pick a bank, submit a clear profile, attend the interview and fund the account. Clean files usually clear in 2 to 4 weeks, so there's little reason to use Wise or Payoneer instead of a UAE bank account long term.
Which UAE Banks to Approach for Your Free Zone Company
Emirates NBD, Mashreq, RAKBank, FAB, ADCB and Wio all serve free zone companies. Match the bank to your activity and turnover rather than applying everywhere, since multiple rejections can complicate later applications.
How to Avoid Rejection When You Apply
Avoid rejection by submitting a complete file, matching your profile to your license, disclosing owners and source of funds, and limiting simultaneous applications. Keep contracts ready so the bank can verify your model.
Your Next Step
You can use Wise or Payoneer instead of a UAE bank account only for limited cross-border receipts. Payroll, visas, license fees and client trust need a UAE corporate account, and the best setup combines both. Contact Dubai South Business Hub banking support to prepare your documents, shortlist a bank and apply with confidence.
More than 40 licensed banks operate in the UAE [1], yet roughly 40% of first-time founders see a corporate account delayed or declined once [2]. That pushes many toward fintech. This guide is for free zone owners deciding whether to use Wise or Payoneer instead of a UAE bank account, and what to do next.
What Is It to Use Wise or Payoneer Instead of a UAE Bank Account?
To use Wise or Payoneer instead of a UAE bank account means collecting and sending business payments through a fintech platform rather than a local corporate account. It can work for small cross-border receipts, but it rarely replaces a corporate account for payroll, visas and licensing.
How Wise and Payoneer Actually Work
Wise gives you multi-currency balances with local details and conversion at the mid-market rate plus a disclosed fee. Payoneer focuses on marketplace and client payouts, then withdraws to a bank. Both are payment platforms, not commercial banks, so you get no chequebook, trade finance or standard UAE corporate IBAN.
Picture a Dubai South Business Hub consultancy invoicing a UK client in GBP through Wise details. It converts to USD at a disclosed fee, which beats the 1-3% spread some traditional banks charge.
Why Founders Consider Them First
Onboarding is faster than bank due diligence.
Entry costs are low, often with no minimum balance.
They bridge the 2 to 4 weeks a clean bank file takes.
Non-resident owners feel safer avoiding rejection.
Say you're waiting on a bank decision. Payoneer can receive that first client deposit. Just don't confuse a bridge with a foundation.
Limits of Trying to Use Wise or Payoneer Instead of a UAE Bank Account
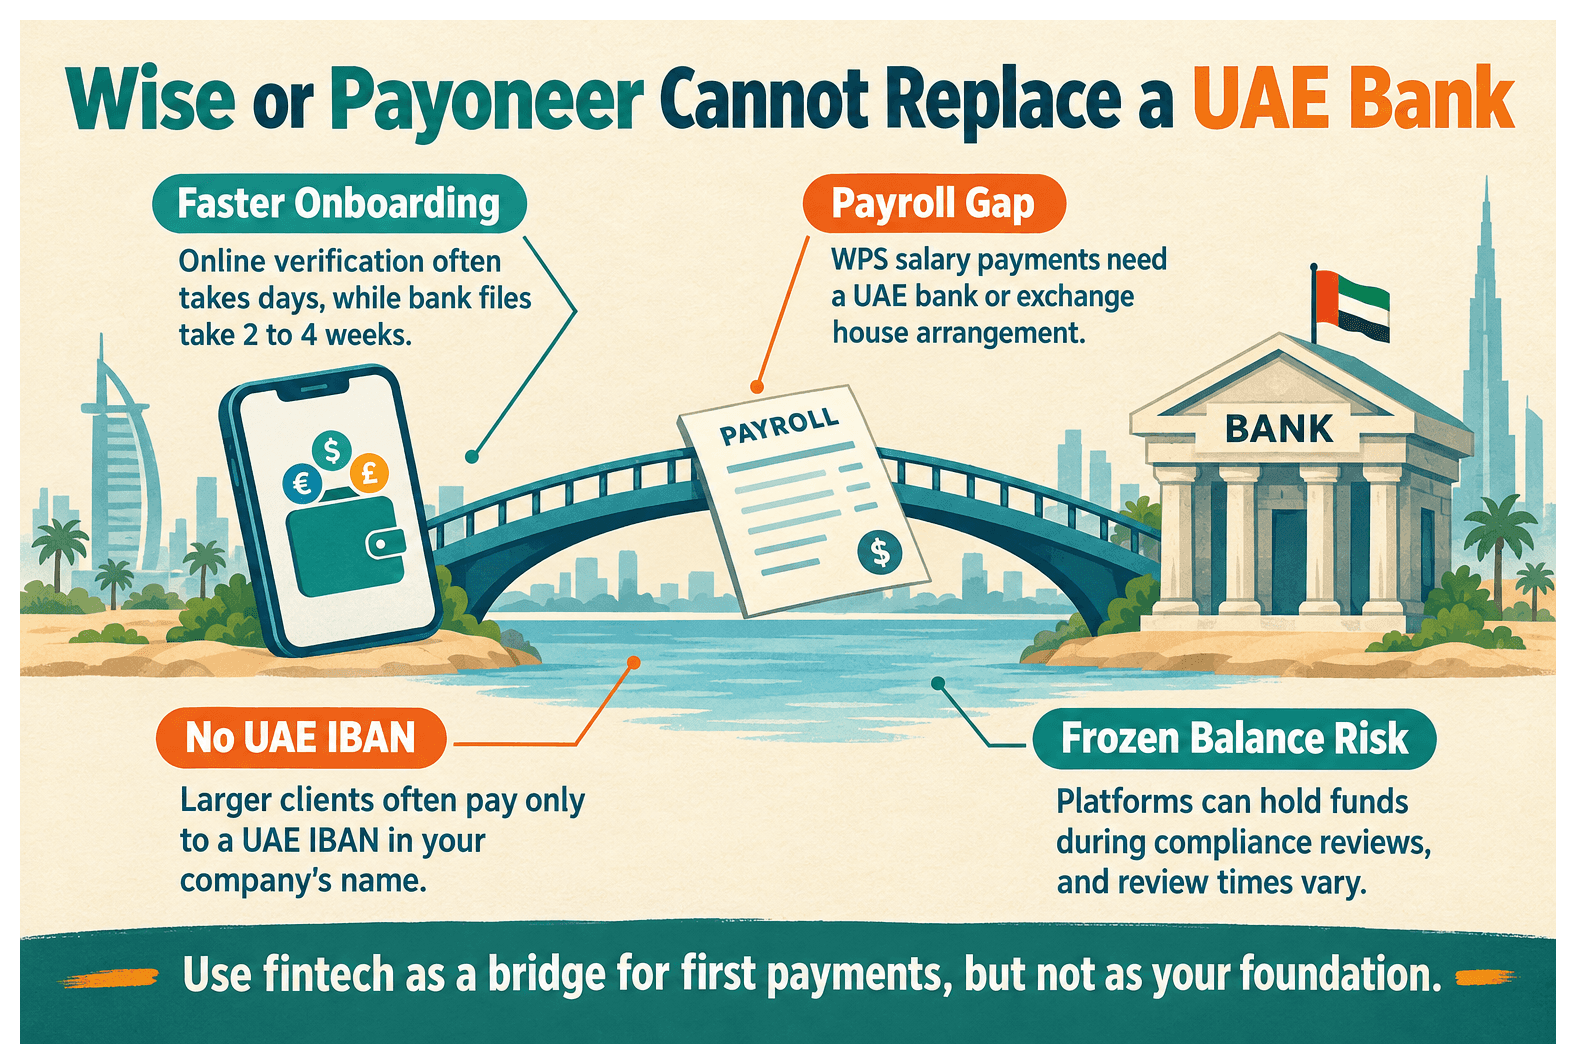
Wise and Payoneer fall short for free zone companies because they usually can't handle WPS payroll, visa and license fees, local cheques or credit. Some counterparties and authorities also expect a UAE account in the company's name.
Payroll, Visas and Government Payments
Salaries through the Wages Protection System (WPS) need a UAE bank or exchange house arrangement. Visa fees, establishment cards and license renewals typically run through UAE bank channels too. Picture three visa holders needing monthly salary transfers that a fintech wallet can't route. The private sector workforce exceeds 5.5 million people [3], so authorities expect this to be routine. Confirm current requirements with your free zone first.
Wise or Payoneer vs UAE Corporate Bank Account
Feature | Wise or Payoneer | UAE Corporate Bank Account |
|---|---|---|
Onboarding speed | Online verification, often within days | 2 to 4 weeks for clean files, plus compliance interview |
Payroll and WPS support | Generally not available | Supported for visa-holding staff |
Foreign currency receipts | Local details in several currencies, disclosed fees | SWIFT receipts, FX spreads of 1-3% at some banks |
Credit and trade finance | Usually none | Overdrafts, merchant acquiring, trade finance by eligibility |
Acceptance by UAE clients and authorities | Often queried or refused | Standard 23-character UAE IBAN in your company's name |
Client Trust, Credit and Compliance
Larger clients often pay only to a UAE IBAN.
Overdrafts and trade finance are rarely offered.
Banks query funds routed through third parties.
One statement trail eases corporate tax records with the Federal Tax Authority.
A logistics firm's anchor client once rejected non-UAE payment details outright. That's common.
Risk of Frozen Balances and Account Closures
Platforms can hold funds during compliance reviews, and review times vary. A trading company with USD held for several days can miss a supplier deadline. Keep contracts and source-of-funds documents ready, and don't let all revenue sit on one platform.
When Wise or Payoneer Make Sense Alongside a UAE Account
Wise or Payoneer work as a complement, not a replacement. Use them to receive foreign currency, pay overseas suppliers or collect marketplace income, then settle to your UAE account for payroll, rent and tax. Learn more about accepting international payments from a UAE company.
Best-Fit Use Cases
Receive USD, EUR or GBP without a foreign account.
Pay freelancers abroad in local currency.
Collect marketplace payouts via Payoneer.
Cover the gap before your bank account goes live.
An e-commerce brand might withdraw Payoneer payouts weekly to its UAE account. That's a sensible setup.
Cost and Currency Comparison
A firm receiving USD 20,000 monthly can lose USD 200 to 600 at a 1-3% spread. Compare incoming SWIFT fees, conversion and withdrawal charges. Multiple currency corporate bank accounts in the UAE can narrow the gap, and the World Bank tracks remittance cost trends.
Step-by-Step Guide to Opening a UAE Corporate Account
To open a corporate account: secure your license, prepare KYC documents, pick a bank, submit a clear profile, attend the interview and fund the account. Clean files usually clear in 2 to 4 weeks, so there's little reason to use Wise or Payoneer instead of a UAE bank account long term.
Step 1: Prepare Your License and KYC Documents
Trade license, MOA, share certificate, lease or flexi-desk agreement.
Passports, Emirates ID if available, proof of address.
A valid free zone license is often the primary document, and a residence visa isn't always needed (see this guide).
Step 2: Write a Clear Business Profile
Describe your activity, markets, clients, expected monthly turnover and transaction countries. Match it to your licensed activity. A consulting firm might list three contracts and USD 30,000 monthly inflows. Inconsistent profiles cause most delays.
Step 3: Choose, Submit and Follow Up
Shortlist 2 to 3 banks.
Answer queries within 24 hours.
Attend the interview, then fund the account.
Keep fintech secondary.
Our free zone bank account guide covers more detail, and the Central Bank of the UAE supervises all licensed banks.
Which UAE Banks to Approach for Your Free Zone Company
Emirates NBD, Mashreq, RAKBank, FAB, ADCB and Wio all serve free zone companies. Match the bank to your activity and turnover rather than applying everywhere, since multiple rejections can complicate later applications.
Traditional Banks Compared
Bank | Typical fit |
|---|---|
Emirates NBD, FAB | Established or higher-volume firms |
Mashreq, ADCB | Trade and SME services |
RAKBank | Small businesses and start-ups |
Confirm current minimum balances and fees directly with each bank.
Digital Banks Such as Wio
Wio offers app-based management and faster onboarding. Check foreign currency and transfer limits. A startup could run daily operations on Wio and keep a traditional bank for trade finance. See also business bank account options.
How to Avoid Rejection When You Apply
Avoid rejection by submitting a complete file, matching your profile to your license, disclosing owners and source of funds, and limiting simultaneous applications. Keep contracts ready so the bank can verify your model.
Common Reasons Applications Stall
Incomplete or inconsistent documents.
Unclear source of funds.
License activity doesn't match the described business.
No physical presence, unexplained.
One application stalled because stated turnover differed from the contracts supplied.
Practical Tips from Consultants
Compile contracts and invoices first, and keep your website and LinkedIn consistent with your profile. If you use Wise or Payoneer instead of a UAE bank account temporarily, disclose it accurately in KYC. Dubai South Business Hub banking support can prepare the file.
Your Next Step
You can use Wise or Payoneer instead of a UAE bank account only for limited cross-border receipts. Payroll, visas, license fees and client trust need a UAE corporate account, and the best setup combines both. Contact Dubai South Business Hub banking support to prepare your documents, shortlist a bank and apply with confidence.
References
Frequently Asked Questions