Topic Summary
Know What Banks Actually Check
Pakistani founders face no nationality bar, but banks apply enhanced due diligence under AML and KYC rules. Expect questions about your business activity, ownership and where your capital came from.
Gather Core Company Documents First
Prepare your trade license, incorporation certificate, share certificate, lease or flexi-desk agreement, articles of association and signatory resolution. Your activity description should match your license.
Prove Your Source of Funds
Add six months of statements, income proof from Pakistan and a CV showing relevant experience. If funding comes from a business sale, include the sale agreement and tax filings.
Compare Traditional and Digital Banks
Conventional and Islamic banks suit larger balances, trade finance and dedicated relationship managers. Digital business banks usually onboard faster and often have lower minimum balances.
Open the Dirham Account First
Start with a dirham account and add USD or other currencies as your invoices grow. This helps you avoid repeated conversion margins.
Apply to Two Banks in Parallel
Submitting to two banks at once reduces the risk of delay if one declines or requests more information. Include a realistic turnover forecast, and plan for a timeline longer than you expect.
Match Invoices to Your Licensed Activity
A mismatch between your actual invoices and your licensed activity will trigger a compliance query. Make sure your business plan and license describe the same work.
The UAE has over 40 licensed banks and 50+ free zones [1]. About 40% of first-time founders still face a delay or decline once [2]. Opening a UAE corporate bank account as a Pakistani entrepreneur is manageable when you know what banks check. This guide covers documents, steps, costs and rejection fixes.
What Is Opening a UAE Corporate Bank Account as a Pakistani Entrepreneur and Why It Matters
Opening a UAE corporate bank account as a Pakistani entrepreneur means registering your licensed company's finances with a bank regulated by the Central Bank of the UAE. You receive client payments, pay suppliers and staff, and stay compliant.
Definition and Regulatory Context
The account sits in the company's name, separate from your personal funds. There's no nationality bar, but expect enhanced due diligence under AML and KYC rules. Picture a Pakistani IT consultant who needs a dirham account to invoice Dubai clients.
Why the Account Matters for Your Business
It supports VAT and corporate tax registration.
It pays visa fees, rent and salaries properly.
It builds a record for later credit.
Free zone applications rose 34% year-on-year (UAE Central Bank, 2026). Read our guide to a Dubai bank account for foreigners.
Documents Pakistani Entrepreneurs Need for Corporate Account Approval
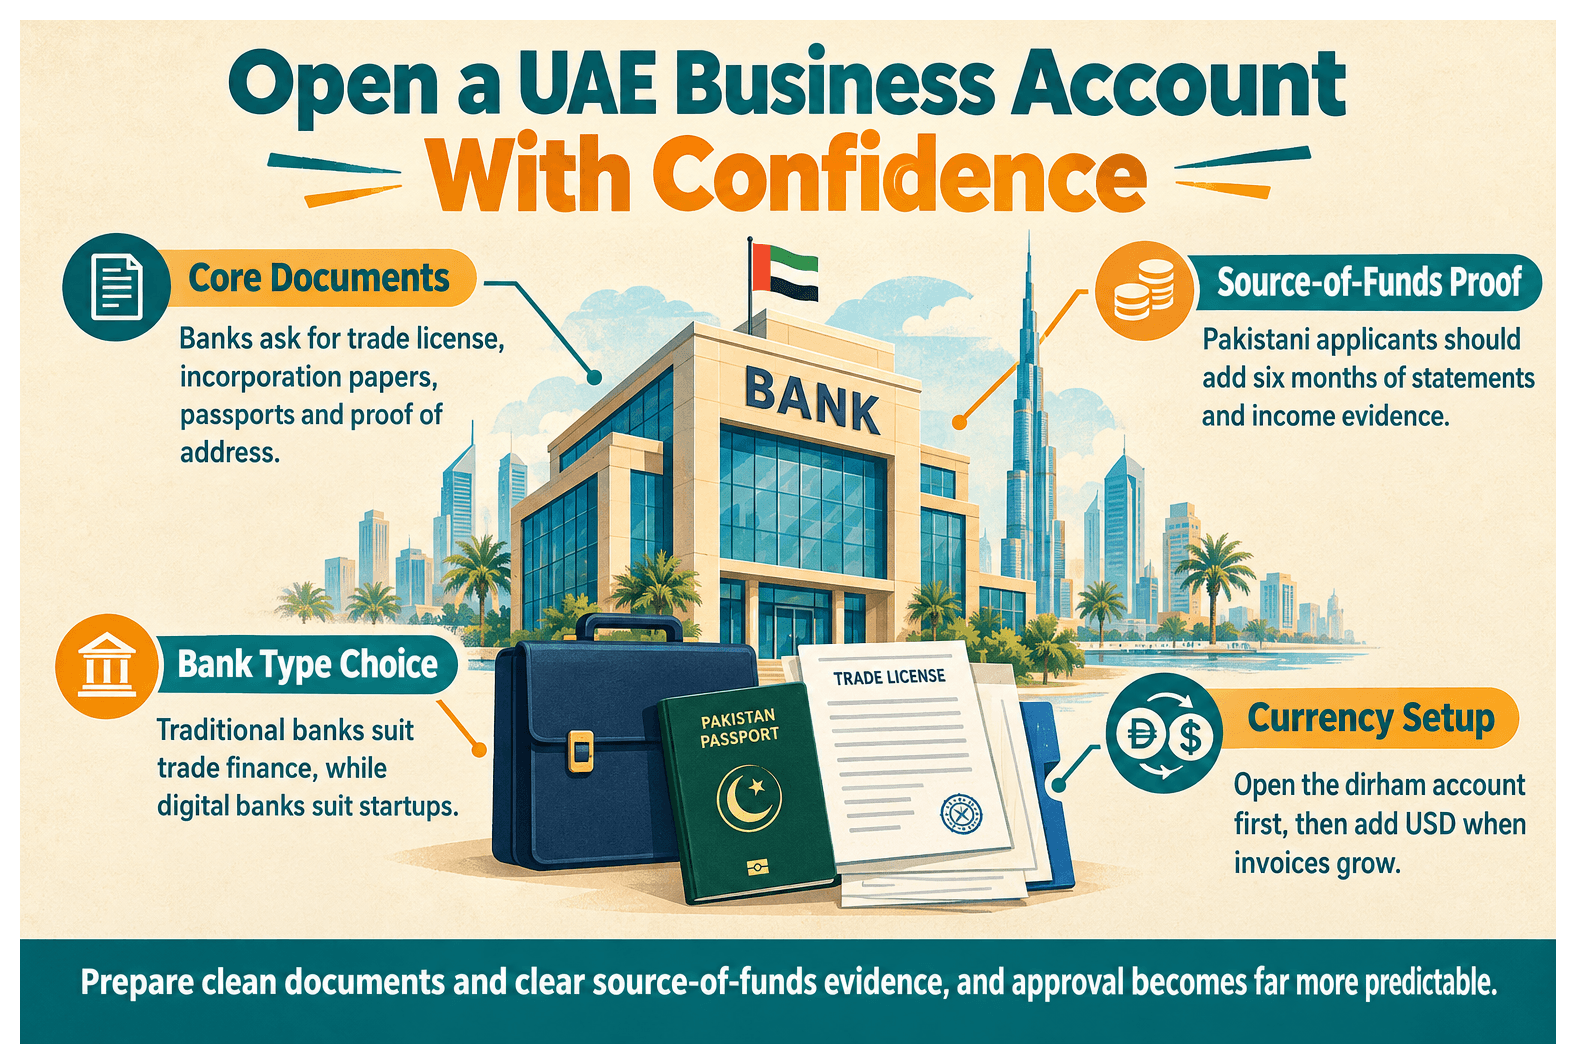
Banks ask for the trade license, incorporation papers, shareholder passports, visa or Emirates ID where available, proof of address and a business plan. Pakistani applicants should add source-of-funds evidence, because compliance teams scrutinise capital origin.
Company Documents Banks Request
Trade license, incorporation certificate and share certificate
Lease or flexi-desk agreement
Articles of association and signatory resolution
An activity description matching your license
Over 40 banks accept a free zone license as the primary document. A consultancy whose invoices differ from its licensed activity will get a compliance query.
Bank Types Compared for Pakistani Founders
Feature | Conventional or Islamic Bank | Digital Business Bank |
|---|---|---|
Onboarding speed | Several weeks with manual review | Online submission, usually quicker |
Minimum balance | Higher thresholds with shortfall fees | Often lower, AED 0 at select banks |
Trade finance access | Letters of credit and guarantees | Limited or unavailable |
Multi-currency options | Sub-accounts added on request | App-based currency tools |
Relationship manager access | Dedicated manager common | Chat and support desk |
Personal and Source-of-Funds Evidence
Passport, visa copy and Emirates ID once issued
Six months of statements and income proof from Pakistan
A CV showing relevant experience
A founder funding the company from a Karachi business sale should submit the sale agreement and tax filings. See banking requirements for Dubai free zone companies.
Choosing the Right Bank and Account Type for Pakistani Founders
Compare minimum balance, fees, onboarding speed and currency options. Traditional banks suit larger balances and trade finance, while digital banks suit startups. Match the bank's risk appetite to your activity and Pakistan-linked flows.
Conventional, Islamic and Digital Banks Compared
Dubai Islamic Bank offers Sharia-compliant accounts, and RAKBANK business banking suits new licensees.
When to Add a Multi-Currency Account
Open the dirham account first.
Add USD when invoices grow.
Avoid repeated conversion margins.
Over 40% of UAE companies transact in two or more currencies.
Step-by-Step Process for Opening a UAE Corporate Bank Account as a Pakistani Entrepreneur
Get your trade license, gather documents, pick a bank, submit KYC and source-of-funds evidence, attend any interview, then fund the account. Most founders underestimate the timeline by three weeks.
Step 1: Secure Your License and Visa Documents
Complete formation, start visa processing and collect certified documents. You can apply before your residence visa.
Step 2: Shortlist Banks and Submit the Application
Apply to two banks in parallel, with a realistic turnover forecast.
Step 3: Complete Compliance Review and Activate
Answer queries within a day, attend video verification, then deposit and set up signatories.
Costs, Minimum Balances and Timelines to Budget For
Budget for opening fees, monthly charges and a minimum balance. One-off fees run AED 0 to AED 2,000 at mainstream banks, so allow several weeks.
Typical Fees and Balance Requirements
Opening fee, monthly fee and transaction fees
Shortfall penalties below the minimum balance
Lower thresholds at digital banks
See corporate bank account costs in Dubai.
Tax Registration Linked to the Account
You'll supply your IBAN when registering for VAT with the Federal Tax Authority. Keep records aligned with your license activity, and don't assume blanket exemption, as qualifying conditions apply.
Common Rejection Reasons and How to Avoid Them
Banks decline unclear activities, weak funding evidence, inconsistent documents or unrealistic forecasts. Align your license with your plan and document your capital.
Compliance Red Flags Banks Watch For
Vague activity descriptions
Shell-like structures with no UAE substance
Unexplained cash or third-party funding
Practical Fixes if Your Application Is Declined
Ask for the reason, fix that gap and reapply. One founder added signed client contracts and succeeded elsewhere. Read why some Dubai companies cannot open a bank account.
Why Dubai South Business Hub Free Zone Simplifies Corporate Banking
Dubai South Business Hub Free Zone provides trade licenses, residency visa packages and guided partner-bank introductions. That reduces paperwork errors and speeds onboarding for Pakistani founders.
Licensing and Visa Packages That Match Bank Needs
Bank-ready license documents
Visa packages tied to your license
Clear activity descriptions
Partner Bank Access for New Licensees
Guided introductions cover Dubai Islamic Bank corporate account opening and RAKBANK, with faster document pre-screening.
Your Next Move
Opening a UAE corporate bank account as a Pakistani entrepreneur is straightforward when your license, documents and funding evidence match. Pick a bank that fits your balance profile, budget for fees, and answer queries quickly. Contact Dubai South Business Hub Free Zone to form your company, secure your license and visa package, and get guided to your account.
References
Frequently Asked Questions