Topic Summary
What Is Source of Funds: What UAE Banks Accept as Proof and Why It Matters
Source of funds is the documented origin of the money you deposit into or use through a UAE business account. Banks accept contracts, invoices, audited financials, salary or dividend records, sale agreements and investor documents. The evidence must match your declared activity, shareholder profile and expected turnover.
Which Documents Count as Source of Funds: What UAE Banks Accept as Proof
Which Documents Count as Source of Funds: What UAE Banks Accept as Proof
Step-by-Step Guide to Preparing Source of Funds Proof Before You Apply
Define your funding origin, collect matching documents, align them with your license activity, certify foreign papers, write a short letter and submit one organised file. A complete file typically clears in two to four weeks.
How Different UAE Banks Review Source of Funds Evidence
All banks apply Central Bank due diligence, but appetite and speed differ. Always confirm current requirements directly with each bank.
Common Source of Funds Mistakes That Trigger Rejection
Banks most often reject files for mismatched names, undocumented cash, vague plans, expired documents and unexplained third-party transfers. Explaining unusual transactions in writing prevents most avoidable declines.
How DSBH Supports Your Source of Funds: What UAE Banks Accept as Proof
DSBH helps Dubai South Business Hub companies prepare bank-ready files by reviewing documents, aligning license activities with funding evidence and guiding applications. Final decisions always rest with each bank.
Your Next Step
Source of funds: what UAE banks accept as proof comes down to traceable, consistent, recent evidence. Map each source, match documents, certify foreign papers and explain anything unusual. Speak with DSBH about banking guidance alongside your license and visa package, so your file is ready before you apply.
Roughly 40% of first-time Dubai founders report a delayed or declined corporate account, and weak funding evidence is a common trigger [1]. This guide covers source of funds: what UAE banks accept as proof, so free zone owners can submit one clean file. The UAE has more than 40 licensed commercial banks [1], and free zone account applications rose 34% year-on-year in 2026 [1]. Compliance teams are busier, and they're stricter.
What Is Source of Funds: What UAE Banks Accept as Proof and Why It Matters
Source of funds is the documented origin of the money you deposit into or use through a UAE business account. Banks accept contracts, invoices, audited financials, salary or dividend records, sale agreements and investor documents. The evidence must match your declared activity, shareholder profile and expected turnover.
Source of Funds Versus Source of Wealth
Source of funds explains where specific money comes from, such as a client payment or shareholder injection. Source of wealth explains how you built your net worth, such as career earnings, a business exit or inheritance.
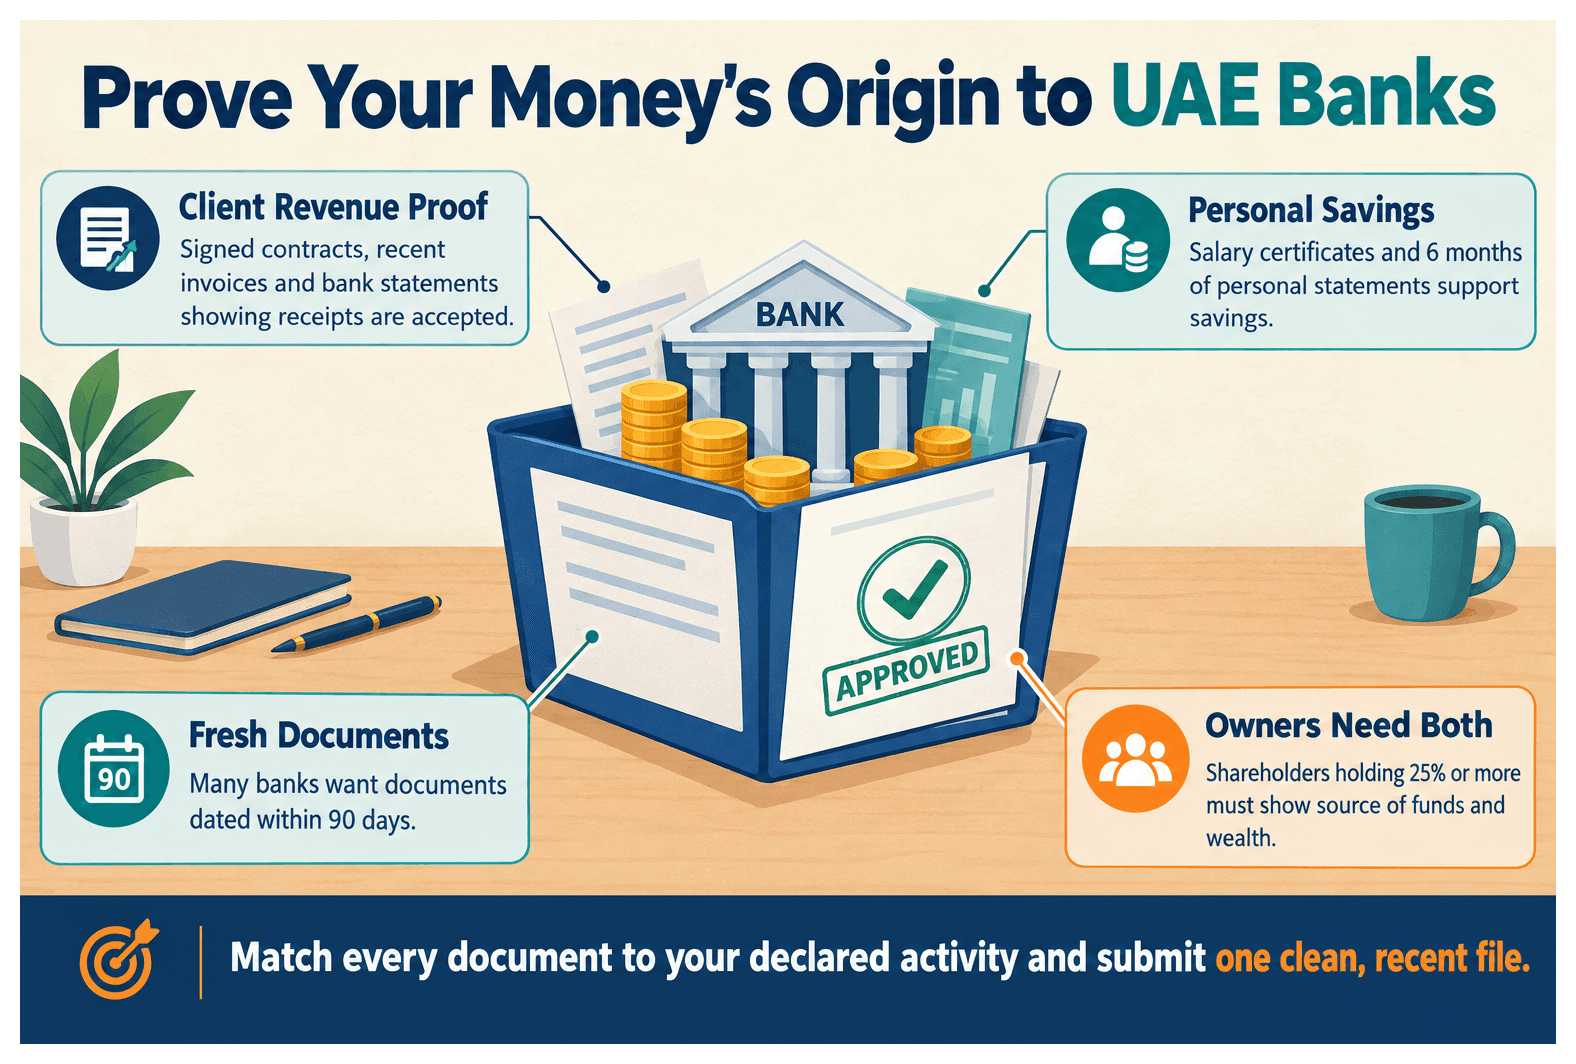
Banks usually ask for both, especially from shareholders holding 25% or more, who are treated as beneficial owners [1]. Say a consultant deposits AED 150,000 as share capital. She shows salary history and statements for wealth, plus a transfer record for the exact funds.
Common Funding Types and the Proof UAE Banks Accept
Funding Type | Accepted Proof |
|---|---|
Client revenue | Signed contracts, recent invoices and bank statements showing receipts |
Personal savings | Salary certificates and 6 months of personal statements |
Business or property sale | Sale agreement plus proof the money was received |
Investor funding | Subscription agreement and investor KYC (identity checks) |
Gift or inheritance | Legal documents, donor ID and a gift letter |
Why UAE Banks Ask for Proof
Banks follow Central Bank of the UAE anti-money-laundering and KYC rules, and they must document due diligence. Proof lets compliance risk-rate you before approval.
A trading company declaring AED 2 million monthly turnover with no contracts gets escalated for enhanced review. It's a predictable outcome. For more on typical declines, read why UAE banks reject corporate account applications.
Which Documents Count as Source of Funds: What UAE Banks Accept as Proof
UAE banks accept documents that trace money to a verifiable, lawful origin. Each should be recent, correctly named and consistent with your declared activity. The full documents UAE banks require from a new company list goes further.
Business Income Evidence
Signed client contracts and invoices matching your license activity.
Six months of statements from any existing company.
Audited or management accounts for established firms.
VAT registration papers where applicable.
Many banks want documents dated within 90 days. A software agency, for instance, presents three contracts, invoices and a prior-company statement showing steady revenue.
Personal Wealth and Capital Evidence
Salary certificates, payslips and personal statements.
Share, property or business sale agreements with proof of receipt.
Gift or inheritance letters with legal documents and donor ID.
Dividend vouchers from earlier holdings.
Foreign-language papers usually need certified English or Arabic translation.
Investor and Loan Funding Evidence
Shareholder loans need an agreement with repayment logic the bank can follow. Angel or venture money needs a signed subscription agreement and the investor's ID. UAE startups raised over USD 1.5 billion across venture and angel rounds [2], so banks see this often. See funding sources for a UAE startup for options.
Step-by-Step Guide to Preparing Source of Funds Proof Before You Apply
Define your funding origin, collect matching documents, align them with your license activity, certify foreign papers, write a short letter and submit one organised file. A complete file typically clears in two to four weeks.
Step 1: Map Every Funding Source
List capital, loans, revenue and investor funds separately.
Assign documents to each source.
Flag gaps before the bank does.
Step 2: Match Proof to Your License Activity
Align your Dubai South Business Hub license activity with contracts.
Keep plan, website and turnover consistent.
Name expected clients and payment countries.
Step 3: Certify, Translate and Organise
Attest foreign documents where required.
Translate non-English or non-Arabic papers.
Match file names to passports and license records.
Step 4: Add a Source of Funds Letter and Submit
Write one page covering origin, amounts and document numbers.
Submit through your relationship manager or portal.
Answer queries within 24 to 48 hours.
The wider process is covered in how to open a business bank account in the UAE.
How Different UAE Banks Review Source of Funds Evidence
All banks apply Central Bank due diligence, but appetite and speed differ. Always confirm current requirements directly with each bank.
Traditional Banks: Emirates NBD, FAB and ADCB
Detailed review of ownership, projections and counterparties.
Higher minimum balances for larger structures.
Timelines often run 2 to 6 weeks.
Mashreq, RAKBank and Wio for Startups and SMEs
Mashreq and RAKBank are commonly considered by smaller free zone firms.
Wio offers digital onboarding with its own checks.
Policies change, so verify first.
A small consultancy might try a digital bank for speed while preparing a fuller file for a traditional one. Banks judge activity clarity, ownership transparency and funding evidence, as outlined in what UAE banks look for in a startup application.
Common Source of Funds Mistakes That Trigger Rejection
Banks most often reject files for mismatched names, undocumented cash, vague plans, expired documents and unexplained third-party transfers. Explaining unusual transactions in writing prevents most avoidable declines.
Inconsistent or Incomplete Documents
Names that differ between passport, license and statements.
Outdated statements or missing pages.
Unsigned contracts with unclear counterparties.
Unexplained Cash, Third-Party Funds and High-Risk Links
Large cash deposits without evidence raise AML flags, and links to higher-risk jurisdictions trigger enhanced checks. A family-funded injection gets approved once a gift letter and donor ID arrive. Compare your file against banking requirements for Dubai free zone companies.
How DSBH Supports Your Source of Funds: What UAE Banks Accept as Proof
DSBH helps Dubai South Business Hub companies prepare bank-ready files by reviewing documents, aligning license activities with funding evidence and guiding applications. Final decisions always rest with each bank.
Pre-Application File Review
Check names, dates and translations.
Spot missing evidence per shareholder.
Align license wording with projections.
Banking Support Alongside Your License and Visa
Formation, trade license and residency visa packages are handled together, with banking guidance once license and Emirates ID steps finish. No approval can be guaranteed, so plan for two to four weeks.
Your Next Step
Source of funds: what UAE banks accept as proof comes down to traceable, consistent, recent evidence. Map each source, match documents, certify foreign papers and explain anything unusual. Speak with DSBH about banking guidance alongside your license and visa package, so your file is ready before you apply.
References
Frequently Asked Questions